Brendon McQueen left Columbia University in 2009 with a film degree and twelve student loans. The degree suggested a future full of stories. The loans had already supplied a plot: roughly $120,000 owed, a bewildering set of obligations, and a graduate trying to work out where to begin. Higher education had taught him to make a film. Its financing arrangements now required him to assemble a rather less entertaining picture.
He could see the size of the problem. Seeing its constituent parts was harder. Which account belonged where? What was due? What could he change? Those were ordinary questions, yet answering them seemed to require an unreasonable amount of detective work. The practical irritation became the beginning of Tuition.io, the company he co-founded and led until 2016.
His story is interesting partly because the original ambition was so specific. A borrower wanted to understand his own loans. From that modest starting point came a business that would help employers contribute to their workers’ education debt. Somewhere between the personal dashboard and the benefits department, McQueen found a second customer for the same problem.
A personal problem, before it became a product.
A film degree meets the paperwork department
Before loan software, there were cameras, scripts and the work of getting a production made. McQueen wrote, directed and produced the 2009 short Skip Rocks. His film background matters because he later described it as preparation for building a company: work with little prescribed structure, where progress depended on taking action before every uncertainty had been resolved.
“It’s all on you,” he said of filmmaking in 2013. A short sentence, and an unusually economical account of the producer’s predicament. There is always another person to persuade, another piece to arrange, another gap between the imagined result and the resources in hand. He saw a familiar challenge when he moved into technology.
His university years had also included editing the Columbia Observer. He described turning a small literary publication into a glossy magazine, with interviews involving figures such as architect Frank Gehry and Electronic Arts co-founder Bing Gordon. Even before Tuition.io, there was an interest in how information reached an audience. The medium would change; the question of whether anyone could use what was in front of them would persist.
Columbia’s account of his early startup years contains a less polished version of entrepreneurship than the ceremonial kind. McQueen was working another job, raising a family and trying to build without much capital. Confidence, in that telling, was something exercised under inconvenient conditions. A founder’s biography can make the leap look clean. The days themselves apparently contained rather more juggling.
Make the unpleasant thing easier to use
Tuition.io’s early proposition was to bring a borrower’s loans into a single view. Its FinovateFall 2012 demonstration described a dashboard, graphical comparisons and tailored plans for navigating repayment options. Steve Pomerantz was co-founder; Richard Wolpert was chairman. Yodlee supplied a technology partnership. McQueen’s personal frustration was becoming a product with colleagues and an operating structure around it.
The public beta arrived in January 2013. Borrowers could inspect balances and interest rates, set reminders and consider repayment plans. The service brought information together while borrowers continued making payments to their loan providers. That distinction was practical: a clearer map could help someone navigate, even before the mapmaker handled the money.
The design choices were deliberate. McQueen wanted an experience that people could follow without acquiring a new vocabulary first. Student debt was already an unwelcome guest; there seemed little reason to give it an incomprehensible website as a companion. An early optimization feature asked questions about the borrower’s circumstances and goals, then suggested possible next steps.
He also resisted charging the people he hoped to help. In the launch period, the platform was free for borrowers, with possible referral income when an appropriate private consolidation made sense. The commercial question sat in plain view: how could a useful service support itself while serving customers whose budgets were already spoken for? His early product decisions had to answer both halves.
“Even though it was so ugly, people loved it.”
Brendon McQueen, on an early version, 2012
That recollection of an early version is a useful antidote to the immaculate startup origin story. People could value relief from confusion before the interface became elegant. His later emphasis on design grew around a need that users had already recognized. The polish had a job to do.
The audience refused to follow the script
One early surprise came from borrowers with substantial incomes. McQueen had expected people facing tight finances to make up much of the audience. Instead, established professionals were asking how to accelerate repayment, including questions about putting thousands of dollars toward their loans each month. The desire for clarity extended across very different household circumstances.
The discovery widened the product’s meaning. Someone trying to reduce a payment and someone trying to finish faster might need different answers, but both needed to understand the accounts first. A film can lose its audience by assuming too much background knowledge. A financial dashboard can commit the same offence, with a rather more expensive ticket price.
By April 2013, McQueen said users had brought more than $500 million in aggregate debt onto the platform. This measured the loans represented there, rather than money Tuition.io had lent or debt it had erased. The distinction helps explain the business at that stage: it was organizing a large set of existing obligations.
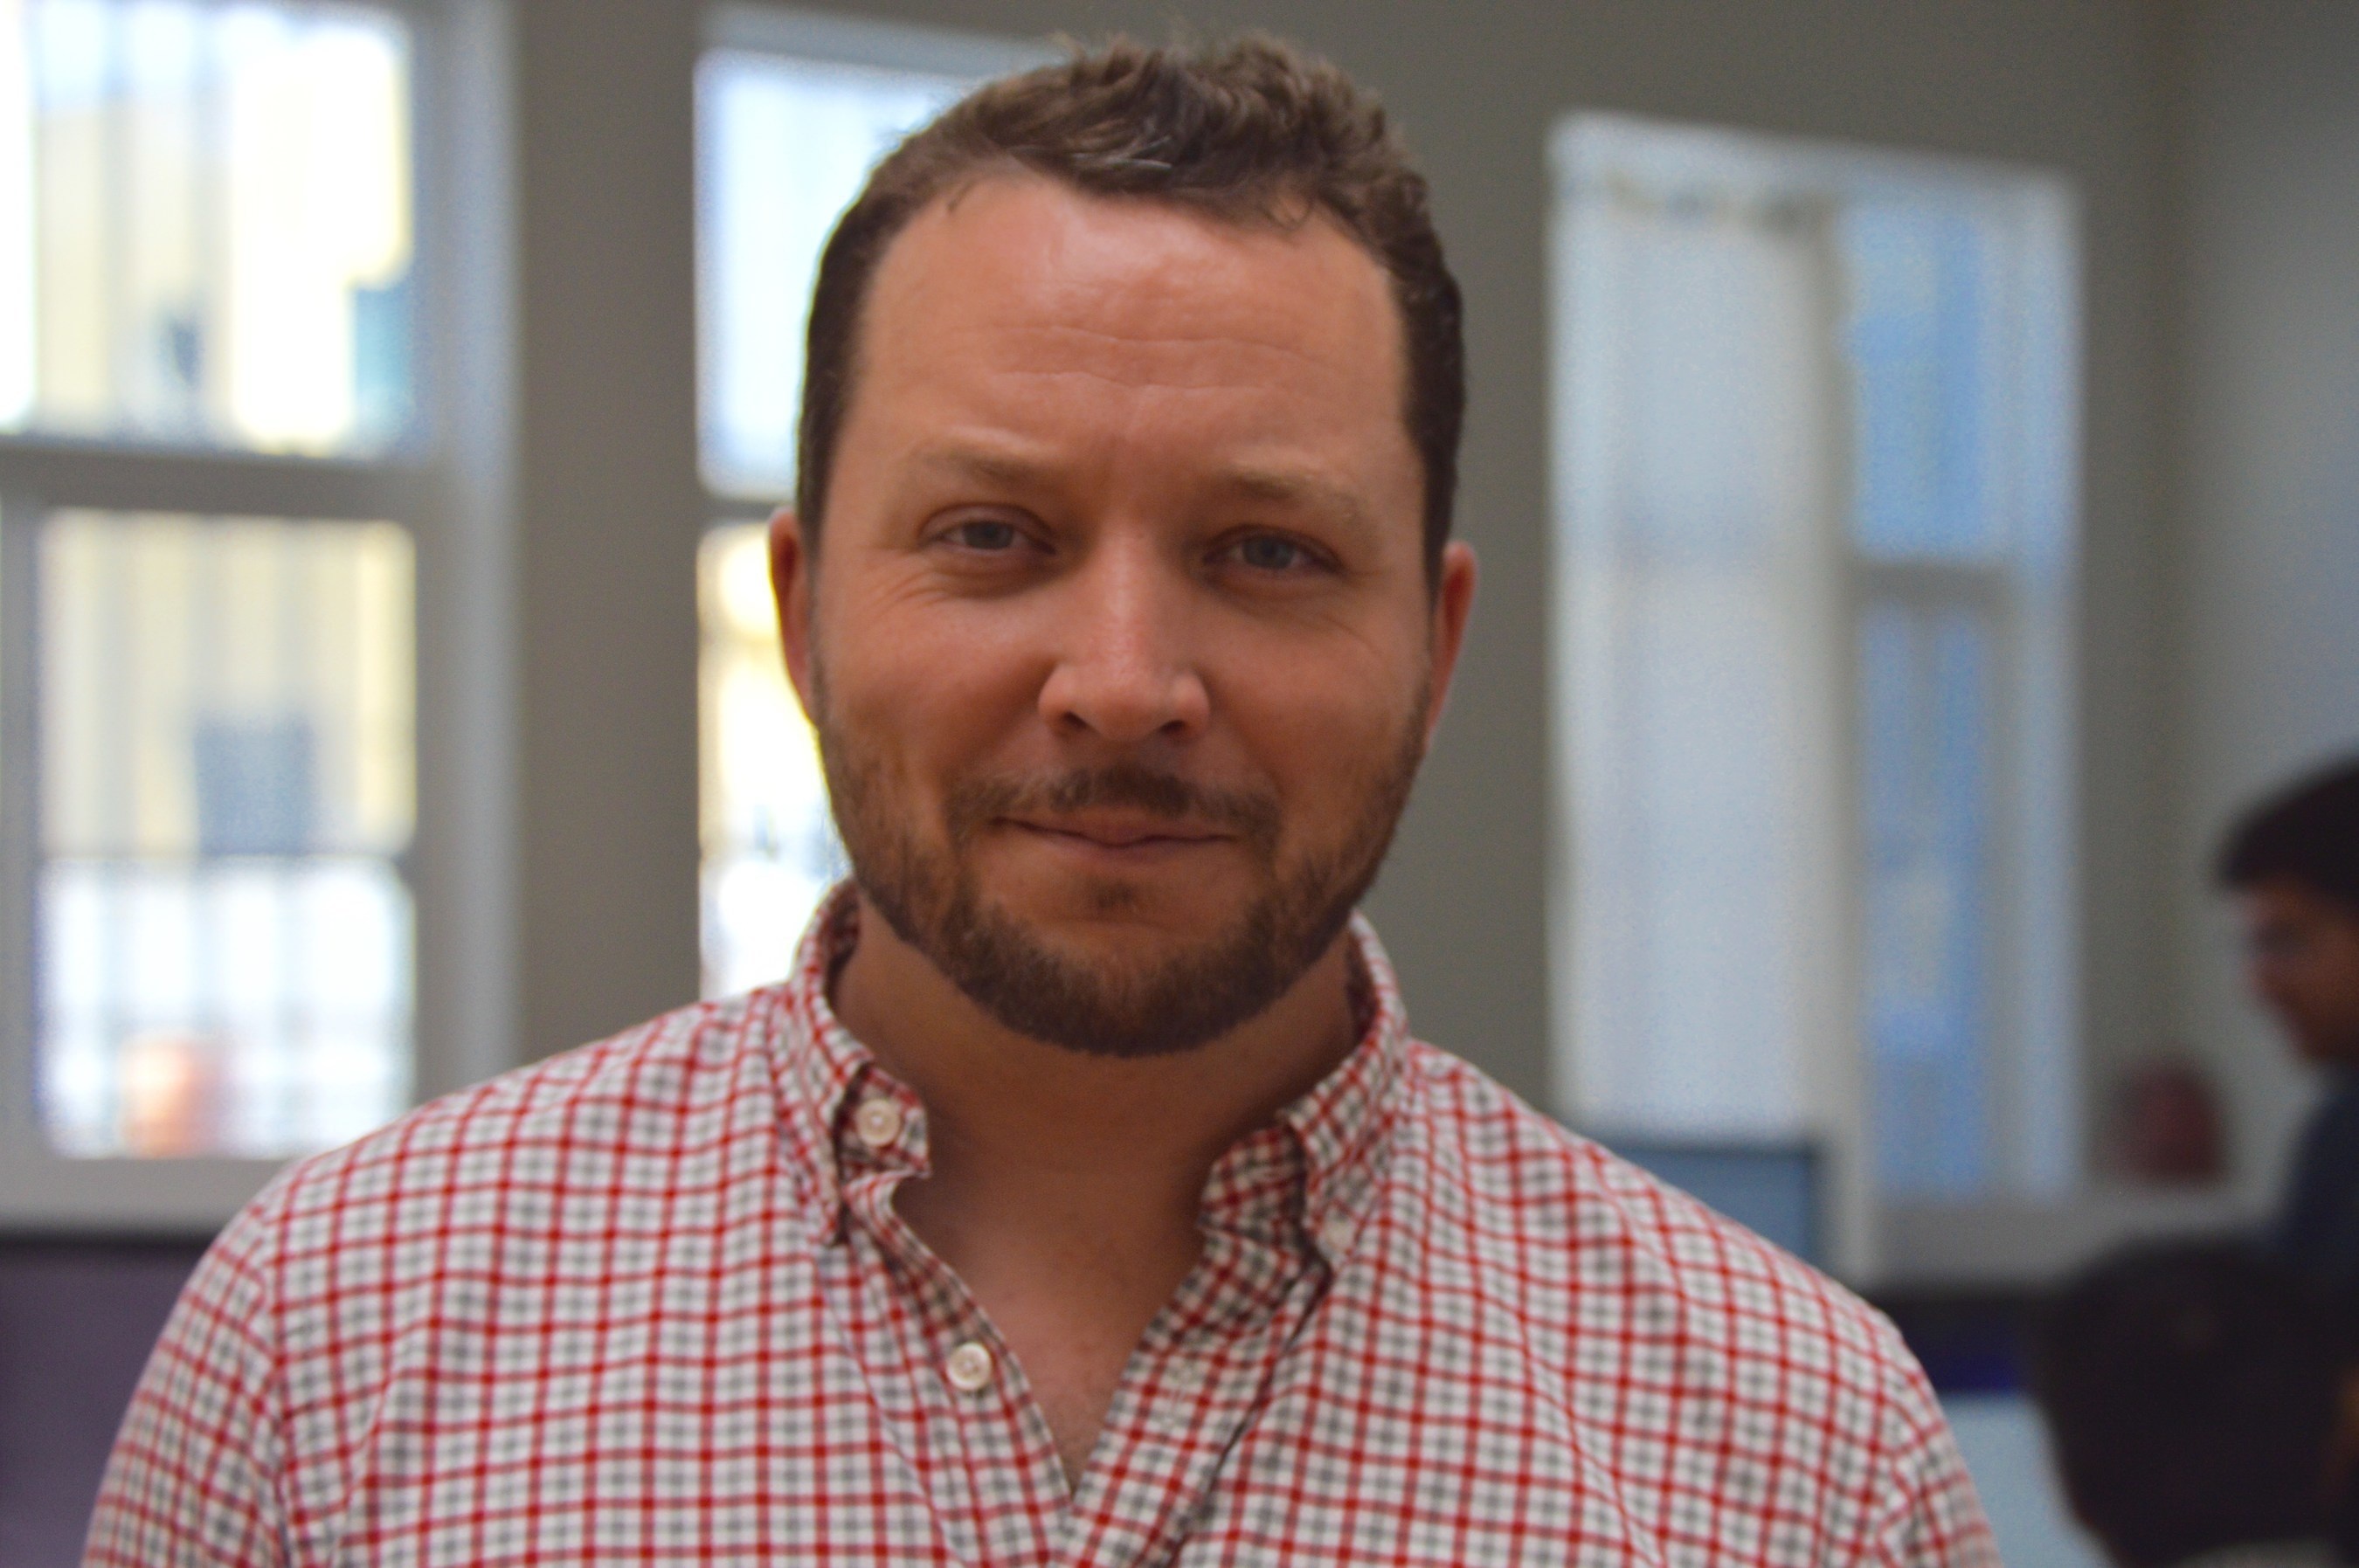
A place for student loans on the benefits menu
In April 2015, Tuition.io introduced Flex395, allowing employers to contribute directly to employees’ student loans. The borrower’s need remained familiar, but the company now had a proposition for the person choosing a benefits package. Helping repay education debt could become part of recruiting and keeping staff.
The mechanics were important. An employer invited workers onto the platform and established contribution criteria. Tuition.io facilitated extra payments to the relevant loan servicers. A company could offer financial help through a defined program, while the employee could see that help applied to an existing obligation. The useful act was pleasingly literal: money went toward the loan.
McQueen’s argument concerned the timing of a benefit. A young employee could understand the value of retirement saving and still be preoccupied with debt due now. He wanted employers to consider what would feel relevant to the person receiving the package. The immediate balance deserved a place in a conversation usually occupied by the distant future.
- EmployerSets the contribution policy
- Tuition.ioAdministers the extra payment
- Loan servicerReceives funds toward employee debt
The funding followed the enterprise direction. In November 2015, Tuition.io announced a $5 million Series A involving MassMutual Ventures, Wildcat Venture Partners and Mohr Davidow Ventures. Total funding reached $8.2 million. The stated plans were concrete: acquire enterprise customers and expand sales, customer success and engineering.
Those investors brought a broader cast into McQueen’s story. Mark Goodman of MassMutual Ventures and Bryan Stolle of Wildcat were backing a business that connected an employee’s existing debt with an employer’s hiring concerns. A problem that had begun with one graduate now required conversations with benefits buyers, investors and corporate decision-makers.
The borrower gets older; the idea gets wider
In May 2016, Tuition.io added support for contributions to Federal Parent PLUS loans. Parents borrowing for their children’s education brought another population into the picture. The benefit could matter to experienced employees as well as recent graduates. McQueen’s company was expanding beyond the convenient assumption that student debt belonged exclusively to the young.
That extension also made the employer’s policy choices more significant. Tuition.io described account auditing and aggregation that could establish loan type and ownership while tracking balances. Beneath the attractive promise of helping an employee lay a collection of administrative tasks. Benefits become real through such details, which rarely receive their own applause.
During 2016, McQueen received a Dig|Benefits Technology Innovator Award. Fidelity was among Tuition.io’s corporate clients, and he discussed the ability to measure interest and time savings for employees. The film graduate was now making a case in the language of benefits administration: adoption, implementation and results that an employer could examine.
December brought a leadership change. Scott Thompson, previously president of PayPal and CEO of ShopRunner, took over as Tuition.io’s chief executive. McQueen’s period as CEO ended there. The company’s account had grown far beyond the dozen loans that prompted it, and its next phase would proceed under a different operator.
Another complicated screen to simplify
McQueen kept building. Shuttle Finance, co-founded with Nick Roberts and Alex Tamoykin, worked on employer-linked savings assistance and announced a partnership with Science Inc. in 2018. Employees could set savings goals and automate contributions; employers could choose to help. The work again connected an everyday financial task with a company benefit.
Later in 2018, he was leading Cred, a cryptocurrency micro-investing app developed with support from Science. In an October interview, he described initial skepticism about crypto and credited Mike Jones with encouraging him to investigate. His interest settled on the difficulty newcomers encountered when trying to use the available tools.
Cred offered recurring purchases, roundups and educational material. In December 2018 it announced a rebrand to Acre and availability in 46 states. These were different products from student loan software, with different risks and markets. The recurring concern in McQueen’s own explanations was ease of use for people who did not consider themselves specialists.
His public LinkedIn profile now lists the Boise metropolitan area and an affiliation with COTIS.AI. Tuition.io remains the chapter that most clearly joins his personal circumstances to a business idea. He began by wanting a legible account of what he owed. Then he helped create a way for someone else, an employer, to contribute to it. For a filmmaker diverted into finance by his own bills, it was a consequential rewrite.
Continue the story
- Brendon McQueen on LinkedIn ↗
- Tuition.io: the company he co-founded ↗
- Columbia’s account of the early years ↗
- Watch: the FinovateFall 2012 product demo ↗
- The 2013 conversation about users, film and building ↗
- The design thinking behind the early product ↗
- The January 2013 public launch ↗
- Flex395: the original employer benefits announcement ↗
- The 2015 financing announcement and photograph ↗
- The expansion to Parent PLUS loans ↗
- The 2016 technology innovator profile ↗
- Tuition.io’s December 2016 leadership change ↗
- Science’s 2018 conversation with McQueen ↗
- The filmmaking credits for Skip Rocks ↗
- Shuttle Finance’s partnership with Science ↗
- Cred’s December 2018 rebrand to Acre ↗