The polished version of a financial-technology career is a tidy procession of brands and titles. Brad Rosenfeld’s version is more revealing when read as a sequence of translations. A nonprofit needs a new stream of support. A global payments company needs more merchants. A small-business lender needs to explain emergency rules while the rules are still moving. An identity company needs to show that security and conversion belong in the same conversation. A lending platform needs to make artificial intelligence sound less like weather and more like useful plumbing.
Rosenfeld has worked on each of those problems. Today he is Chief Marketing Officer and Chief Strategy Officer at Biz2Credit and Biz2X, the New York lending company and its enterprise software platform. The double title is less ornamental than it looks. It puts the story, the market and the operating choices close together. For a company selling digital lending infrastructure to banks and other financial institutions, that proximity matters. Buyers are not shopping for a prettier slogan. They are deciding whether to change the machinery that moves applications, data, decisions and money.
His public career makes a case that clarity is not the wrapping around a technical product. It is part of the product. If a borrower cannot understand the next step, if a bank cannot see how a model fits its controls, or if a prospect cannot explain the platform to a colleague, the system has already acquired friction. Rosenfeld has spent more than two decades finding and removing that friction, usually with a mixture of data, narrative and cheerful impatience.
Before fintech, there was affinity
After undergraduate study, Rosenfeld founded a marketing-technology consultancy that connected nonprofits with national brands including Papa John’s, Sonic and Subway. The mechanism was affinity-based digital products: a transaction could create revenue for a business while directing support toward an organization people cared about. It was an early lesson in alignment. A campaign worked when the customer’s action, the company’s economics and the nonprofit’s mission could all occupy the same small piece of screen.
He sold the venture, earned an MBA at Columbia Business School and moved into product marketing at Philips Sonicare. Toothbrushes may seem a long walk from loan-origination software, but the commercial muscle is similar. Features live in the factory. Benefits have to survive the journey into somebody’s morning, budget or workflow. Rosenfeld later entered payments at PayPal, running North American B2B digital marketing. During that chapter, the company’s merchant base in the region grew from roughly four million to more than eight million.
Scale taught one lesson; smaller companies taught another. Rosenfeld has advised young professionals to consider joining an up-and-coming company near the ground floor instead of optimizing only for a famous logo. He has lived on both sides of the choice. His argument is about learning density. In a growth company, the distance between an idea, a customer reaction and a revised product can be short enough to walk before lunch.
“From a marketing standpoint the core advantages that Biz2Credit has are information and speed to market.”Brad Rosenfeld, on competing during the PPP era
When the FAQ became infrastructure
That distance became especially short during the pandemic. At Biz2Credit and Biz2X, Rosenfeld’s marketing team was working in a market where government programs, lender requirements and small-business anxiety changed almost together. Information could expire before the campaign reporting arrived. Speed was not a preference. It was the job.
The company partnered with AICPA to build a PPP loan-forgiveness tool that helped hundreds of thousands of small businesses assemble the documents needed to pursue forgiveness. When accountants signed up in volume, the team built CPALoanPortal.com in two weeks. Webinars brought in service partners and public officials. Owned content carried rules and analysis to business owners. Technical SEO pushed the useful material toward people searching under pressure. Rosenfeld reported organic traffic rising more than 300 percent from January.
By early 2021, he was publicly celebrating more than 165,000 SBA PPP-approved loans and over $4.7 billion in approved funding through Biz2Credit. Those figures belong to a strange moment in American commerce, when a portal, a webinar and an accurate paragraph could help determine whether a neighborhood business reached another month. Marketing became part newsroom, part product desk and part traffic controller.
The episode also shows what Rosenfeld means by a feedback loop. Customers do not merely receive a message. Their behavior changes the journey. A surge of CPAs produced a portal. Questions became webinars and articles. Search behavior shaped the content plan. The distinction between marketing and product blurred because the customer did not care which department owned the answer.
Selling trust without selling friction
At Prove, Rosenfeld encountered the same tension in a different costume. Digital identity sits between two unpleasant outcomes: make verification too burdensome and a legitimate customer abandons the process; make it too permissive and fraud walks through. He framed that security problem in commercial terms. Marketing leaders were no longer responsible only for getting eyes onto a webpage. They were increasingly accountable for sign-ups, onboarding and retention. Identity belonged inside the growth conversation.
His ambition for the category was expansive but easy to picture: a person should be able to open a bank or fintech account, or send a consequential wire, as seamlessly as making a phone call. Mobile devices were central because, as he observed, smartphones are with people every second of every day. In emerging digital economies such as Brazil and India, he saw mobile-first identity as a way to combine access with fraud reduction.
Rosenfeld also helped shape Prove’s brand as it evolved from Payfone. The work was recognized with Gold honors from the MUSE Creative Awards and the Davey Awards in 2022. More important than the shelf hardware was the repositioning: a point solution became a platform story. A former colleague later described Rosenfeld’s ability to distill complex technology, align product, sales and marketing, and give teams greater clarity. That description could sit beneath nearly every stop on his résumé.
“As a marketer, you need to develop a message that resonates with your customer, and then you need to get that message out there by any means necessary.”Brad Rosenfeld
The “any means” line sounds exuberant, but Rosenfeld pairs it with an old-fashioned constraint: the message must resonate first. Tools multiply. Fundamentals remain annoyingly durable. He has written and spoken about QR codes, onboarding, digital trust and B2B growth, yet his practical unit of work is still the customer’s next action.
A brief detour through private markets
In May 2025, Allvue Systems announced Rosenfeld as Chief Marketing Officer while increasing investment in data, analytics and AI for alternative-investment managers. His language there was about turning market noise into real-time clarity. Private capital offered another technically dense arena: fragmented data, manual reconciliation, fund operations and software that must support decisions without becoming another source of opacity.
The role was a compact chapter. By 2026 Rosenfeld had returned to Biz2Credit and Biz2X with strategy added to his marketing remit. The return carries a certain logic. Payments taught distribution. The PPP period taught rapid utility. Prove taught identity and trust. Allvue added another view of institutional data and agentic AI. Biz2X is where those strands can meet inside lending.
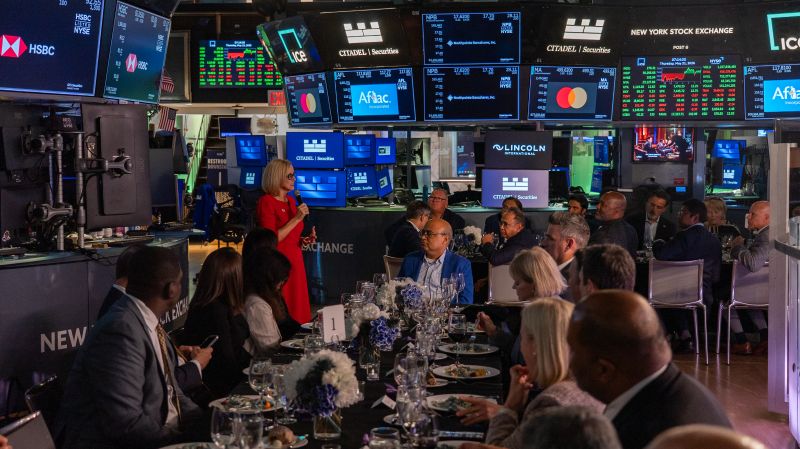
A recent dinner on the New York Stock Exchange floor offers a livelier picture of the job than an org chart does. Around the table were people from Mastercard, Amazon Web Services, Optum Bank, Aflac, Jack Henry, HSBC, American Airlines, Paychex and RBC Capital Markets, along with guests from government and media. Rosenfeld wrote that the rewarding part was seeing the minds behind partner brands in one room, exchanging ideas and enjoying themselves. Enterprise strategy, it turns out, may involve credit models and cloud integrations, but it still benefits from dinner.
The next lending interface may be invisible
Rosenfeld’s current public argument is that small-business lending remains a large missed opportunity. Traditional lenders have long worried about cost to serve and incomplete data. Borrowers have endured awkward journeys that ask them to leave the software where they run the business and enter a separate financial maze. Embedded finance changes the doorway. Credit can appear inside payroll, invoicing or point-of-sale tools, closer to the context that explains why it is needed.
What changes when lending enters the workflow?
AI adds judgment-like speed to that model, and with it a fresh communication problem. A bank needs more than a claim that a model is intelligent. It needs to understand the data, the workflow, the controls and the consequence of a decision. A borrower needs a humane path through the application. A platform partner needs the system to fit existing operations. Rosenfeld has described the transition as a move beyond simple automation toward intelligence that changes both borrower experience and decision accuracy.
His task is to make that transition credible without sanding away its complexity. Marketing and strategy belong together here because the promise constrains the product. If the story says faster, integration has to be fast. If it says responsible, risk and compliance cannot be footnotes. If it says embedded, the experience must feel native to the place where the borrower encounters it.
The useful sentence
There is a personal counterweight to all this velocity. Rosenfeld has spoken openly about the difficulty of balancing work with being an engaged partner and parent. His answer is modest rather than optimized: try to be fully present in the office and at home. Presence is a fitting discipline for someone whose career depends on noticing where people hesitate.
He continues to lecture and speak at Columbia Business School, where he has coached students on strategic intuition and joined fintech programs. Public recommendations from former colleagues emphasize collaboration, mentorship and a willingness to give teams clarity while leaving room for creativity. He also advises portfolio companies through Lighthouse Equity Partners, extending the same brand, positioning and go-to-market work into an investor setting.
The progression from founder to operator to adviser is tidy only in retrospect. Up close, it is a collection of rooms: a startup meeting, a PayPal dashboard, a pandemic webinar, a rebrand review, a private-markets product launch, an exchange-floor dinner. The connecting object is the useful sentence, the one that lets a product team agree with sales, a bank understand a platform, or a business owner know what to do next.
Finance will keep producing intricate systems and urgent acronyms. AI will make the machinery faster and, occasionally, stranger. Rosenfeld’s career offers a practical answer to both. Begin with the person trying to move. Find the friction that stops them. Make the system legible. Then give them a reason to take the next step.