The revealing number in NewtekOne’s story is $20 million. That was the cash price of the National Bank of New York City, acquired in January 2023. For a company already arranging business loans, processing payments and handling payroll, a small bank might sound like another item on a crowded shelf. It changed where the money came from, how long Newtek could keep a loan, and what it could ask a customer to do next.
- A bank charter added deposit funding to an established business lender.
- Newtek combines lending with banking, payments, payroll and insurance.
- The useful question: how much time does connecting those services save?
The $20 million change of plumbing
NewtekOne, listed on Nasdaq as NEWT, serves independent business owners across the United States. Founder Barry Sloane traces his interest in that customer to his father’s Brooklyn retail store, where he began working at eleven. The company dates to 1998. Its customer is the person who must buy inventory, pay employees and find financing while keeping an actual business running.
Before the acquisition, Newtek operated as a business development company. Buying the bank and becoming a financial holding company gave it access to deposits. A lender’s funding source sounds remote from the shop floor. It helps determine whether financing is available, how it is priced and whether the lender needs to sell the loan.
The $20 million was the purchase price, not an all-in transformation budget. The acquisition filing also recorded a $31 million cash contribution and the contribution of two subsidiaries to the bank. Software, compliance and operating work sit behind the deceptively tidy transaction number.
Two clocks, one borrower
Business lending runs on two clocks: how soon the money arrives and how soon it must leave again. Newtek offers SBA loans, commercial real estate financing, commercial and industrial loans, and credit lines. Its longer-amortizing lending stretches principal repayments over ten to twenty-five years, depending on the product. That can reduce the monthly burden compared with a shorter repayment schedule.
In March 2026, Newtek Bank introduced its Seven Day Business Loan: secured loans up to $350,000, funded to approved borrowers within seven days of a complete application, with ten-year repayment and no balloon payment. Every qualifier matters. Approval still requires underwriting; the clock begins with a complete application.
The expertise is in processing a business’s messy financial life. Newtek says its AI-assisted system gathers and analyzes financial information and reviews business documents, then presents the material for a credit decision. Credit professionals make that decision. Faster document handling can shorten the wait without making the underlying borrower easier to assess.
“Time is money for independent business owner clients.”
Barry Sloane · March 2026
Speed does not remove the obligations. Newtek’s January 2026 description of its Alternative Loan Program required personal guarantees from owners with stakes of at least 20%, pledged business assets and, in some cases, liens on personal assets. It also described prepayment penalties. A smaller monthly payment deserves comparison with total interest, fees and the cost of leaving early.
The screen has to earn its place
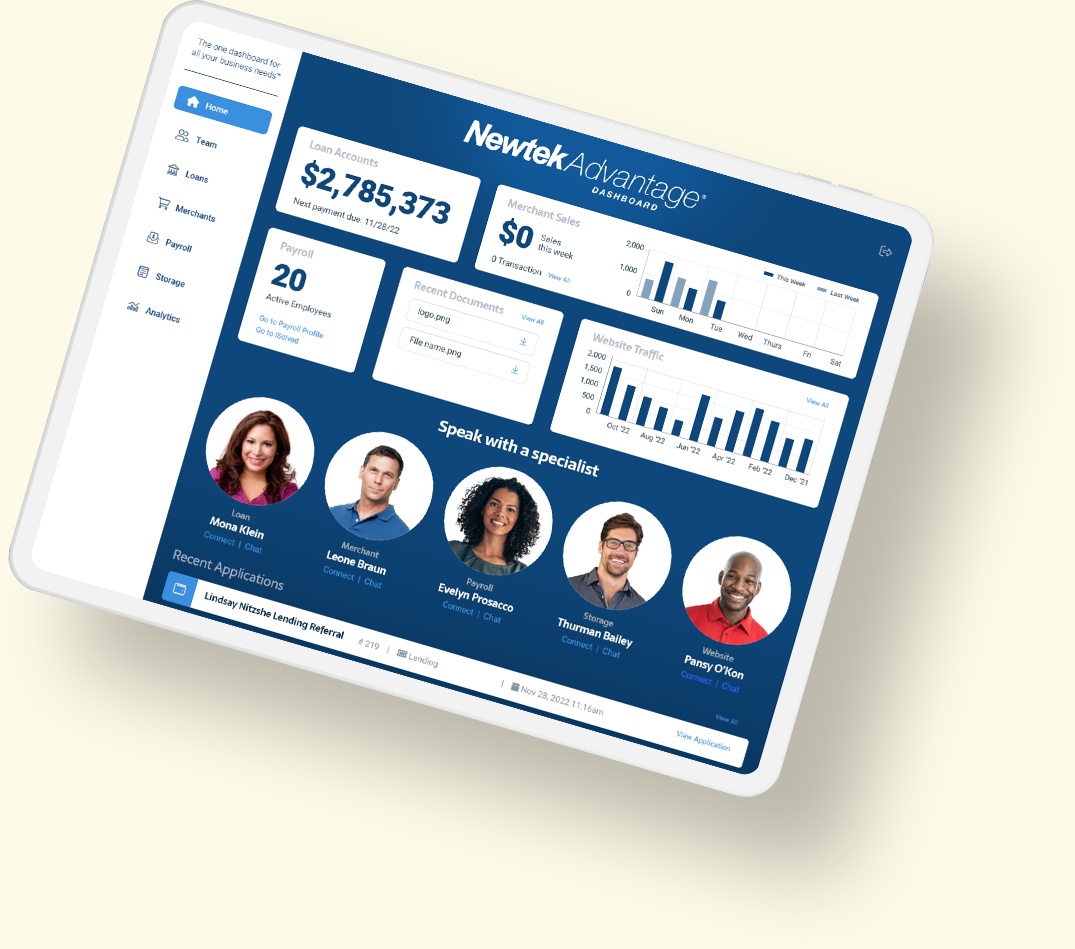
Newtek Advantage is the customer portal joining banking information, payment activity, payroll access, documents and specialists. Registration is offered at no cost. The services behind it have their own economics: loan interest, payment processing charges, payroll fees and insurance commissions. The portal gives those separate relationships a common front door.
The connections became more concrete in September 2026, when Newtek announced integrations with Sage, Xero, FreshBooks and Restaurant365 alongside QuickBooks. It describes same-day merchant proceeds deposited into Newtek Bank accounts and same-day payroll capability. In October it added Zelle for eligible small-business clients. The attraction is less time spent moving money and reconciling the trail.
There is a useful wrinkle in the technology offering. Newtek sold its technology subsidiary in January 2025; cloud, security and related services are now delivered through IPM. A connected experience can include an outside supplier. For an owner choosing services, knowing who delivers each part still matters.
June’s insurance integration shows the idea at a smaller scale. Information already captured in a loan application can generate bindable quotes for required coverage through Newtek Insurance Agency. That targets an ordinary closing delay: the borrower searching for acceptable insurance while everyone else waits. Reusing information at the next handoff is a technique other service businesses can copy.
Borrowing somebody else’s front door
A branchless lender needs ways to meet customers. Newtek recruits referral partners, including financial institutions, and gives them NewTracker to follow applications through closing. A bank can refer business it does not wish to fund and offer adjacent services. The distribution relationship can be cooperative even when the institutions overlap.
The June 2026 Payroc alliance extended that approach to a payments platform with more than 190,000 active merchants. Those merchants gained access to Newtek offerings; they did not automatically become Newtek customers. A more revealing adoption figure arrived in the second-quarter results: roughly 54% of Newtek Bank’s business lending clients had opened a business deposit account since the acquisition.
Borrowers becoming deposit customers.Approximate share of Newtek Bank business lending clients opening a business deposit account since acquisition, reported Q2 2026.
The price of waiting
The transition has required adjustments. An American Banker report republished by Newtek in June 2025 described interruptions to alternative-loan growth during the pandemic and the 2023 banking crisis, when capital availability tightened. A lending product can appeal to borrowers while its funding constrains its expansion.
By August 2026, management described the opposite development: deposit gathering had exceeded initial expectations. Newtek decided to retain more guaranteed portions of SBA loans instead of selling them for upfront gains. It reset expected 2026 earnings to $1.70-$1.80 per share. Recurring interest would arrive over time. Those figures were guidance, with execution still ahead.
The practical lesson is to draw the route from a customer payment to employee payday and count the handoffs. Newtek is attempting to connect that route. A digitally comfortable business may value the arrangement; an owner needing regular branch visits may prefer another bank. Longer lending also depends on credit quality and dependable funding. The dashboard can simplify the view. The obligations underneath it still have to work.