Ohad Lifshitz had a successful physical therapy clinic on Manhattan’s Upper East Side. Six employees. Patients who needed treatment. And, according to his son Eyal, a recurring nuisance: insurance companies took weeks, sometimes months, to pay. Work completed and money received occupied different calendars. Payroll, inconveniently, kept its own.
- Bluevine began by advancing money against unpaid invoices.
- It sold factoring and built checking, payments and credit around the everyday business account.
- Valley has agreed to buy it for about $340 million; closing is expected in early 2027.
The six-person clinic
“Billing delays were just killing me,” Ohad told Eyal. The clinic sometimes relied on credit cards while it waited. The problem was painfully specific: a healthy business could have an unhealthy bank balance. Anyone who has paid a supplier before collecting from a customer will recognize the arithmetic.
In 2013, Eyal Lifshitz co-founded Bluevine with Nir Klar and Moti Shatner. Its early answer was invoice factoring: advance cash against an unpaid invoice, then recover the advance and fees when the customer pays. Technology could shorten a process that had traditionally involved considerable paperwork. The invoice was evidence of work already done.
The product it left behind
Bluevine added revolving credit in 2016. Then came the more consequential expansion: business checking, announced in 2019 and launched in 2020. A $102.5 million Series F, led by ION Crossover Partners, backed the broader banking ambition. Lending could help during a cash shortage. A checking account could be useful every working day.
By January 2022, Bluevine was willing to part with its original business. FundThrough acquired the invoice-factoring operation, including its division employees. Bluevine concentrated on checking, bill pay and credit. Selling a first product is an unusually clear way of explaining what a company thinks its next product can become.
The founder had already described his change in thinking in a 2019 interview: the opportunity was to solve customers’ financial problems from beginning to end. That shift offers a useful lesson for builders. Follow the work surrounding your product. The adjacent chore may reveal a larger opportunity than improving the original feature again.
“Billing delays were just killing me.”Ohad Lifshitz, recalled in Eyal’s founder account
One screen, several jobs
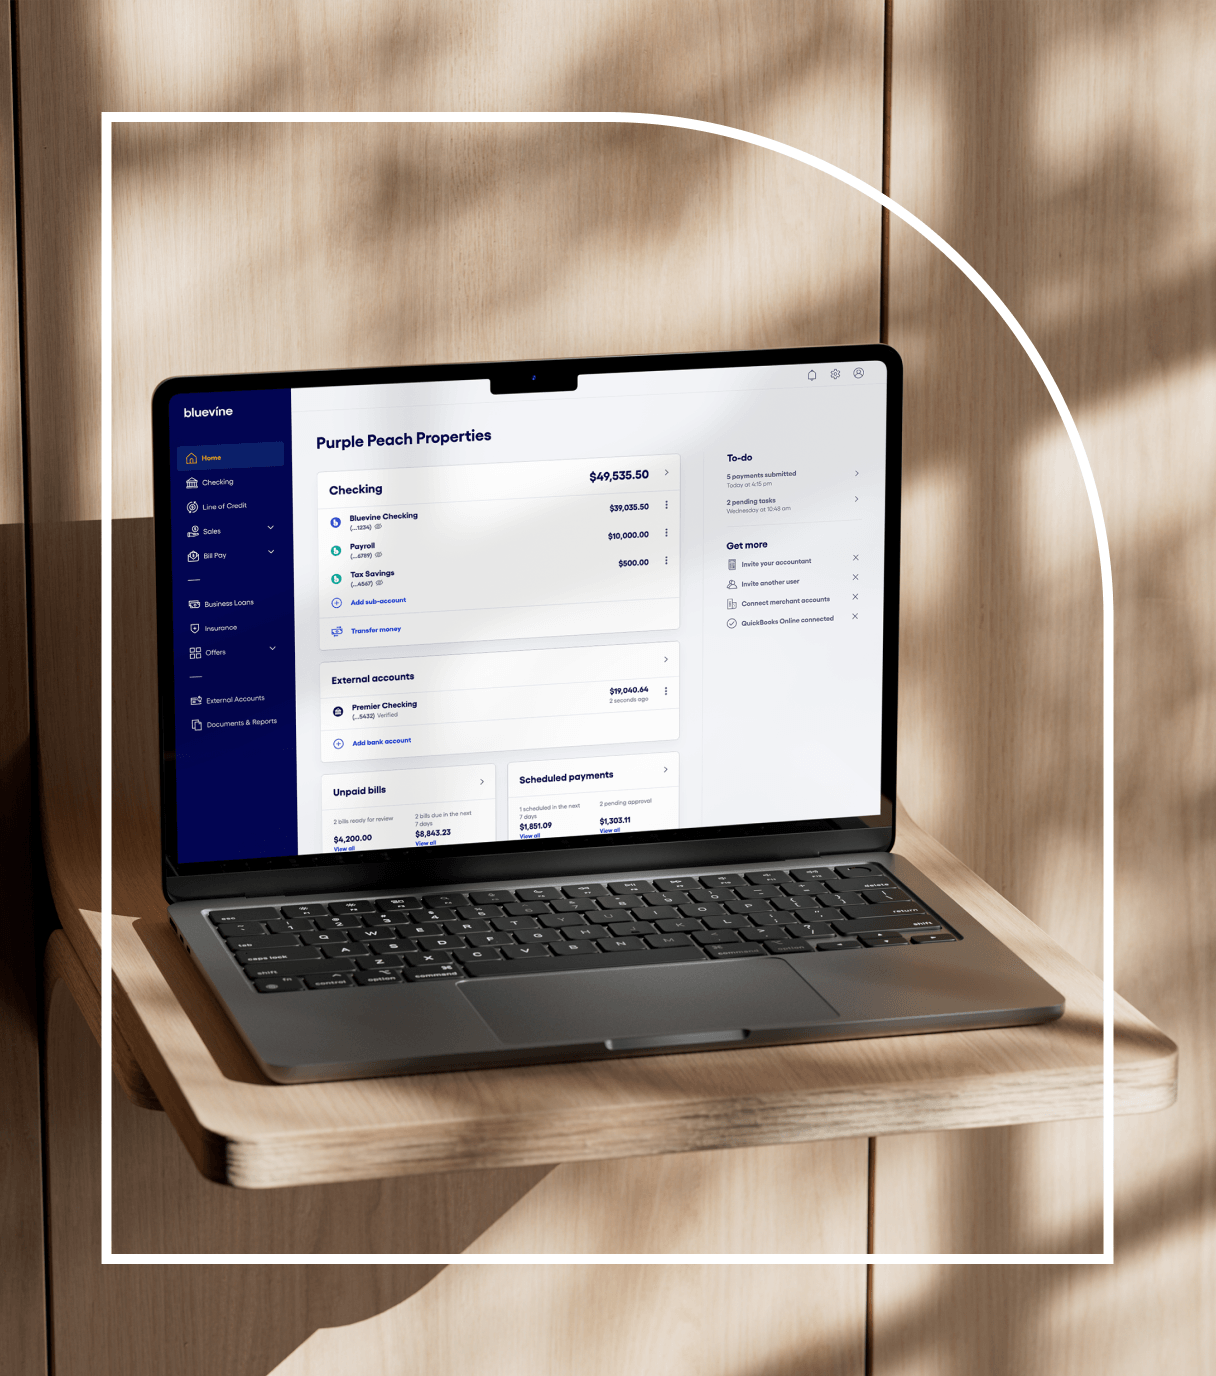
Today, Bluevine puts the operating account at the center. Owners can separate money into sub-accounts, issue debit cards, schedule vendor payments and give an accountant access. Invoicing and payment links, added in 2025, bring customer collections into the same environment. Tap to Pay lets supported phones accept contactless payments without a separate terminal.
Think of a small agency collecting a project fee, reserving part for taxes and paying a contractor. That is an illustrative workflow, not a customer testimonial. Bluevine’s appeal is that these jobs can sit close together. Its named customers include school-lunch business FoodDays and safari specialist Wander Africa: businesses with quite different work, but familiar money chores.
The machinery involves partners. Bluevine is a financial technology company; Coastal Community Bank provides banking services, while Celtic Bank issues its line of credit. Stripe powers payment acceptance, with implementation advice from Yeeld. Xero synchronizes banking data with accounting. Bluevine builds the experience across those connections.
Stripe’s account of the payments rollout supplies a concrete detail worth copying: use hosted merchant onboarding rather than rebuilding identity verification. Stripe reports more than 35,000 merchants onboarded and over $100 million processed. The lesson is about choosing where to spend engineering effort. Customers benefit from fewer forms, regardless of whose infrastructure processes them.
There is an organizational counterpart. Bluevine’s published values include “Operate as Owners,” alongside integrity, experimentation and shared growth. Those are company statements, but the product choices make the ownership question concrete: which parts of the experience must Bluevine control, and which can a specialist handle? A useful partnership needs a clear answer to both.
Free has a price list
As checked in October 2026, Standard checking has no monthly fee. Plus costs $30 a month; Premier costs $95. Both paid plans offer waivers, but each requires a qualifying balance and debit-card spending. Higher advertised interest belongs in the calculation alongside fees, eligibility and the amount actually left in the account.
Cash changes that calculation. Depositing $500 at an Allpoint+ ATM costs $3.50 under the published formula of $1 plus 0.5%. A business handling cash daily should examine deposit limits and network locations closely. An online account’s convenience depends partly on how often the business needs something physical.
Credit has a separate gate. Bluevine’s published minimums include an eligible corporation or LLC, twelve months in business, $10,000 in monthly revenue and a 625 personal FICO score. Meeting those thresholds does not guarantee approval. Nor does an approved line guarantee every draw. A newly formed business cannot treat the checking account as a promise of financing.
The account becomes the asset
The competitive set includes Mercury, Relay, Novo and conventional branch banks. Bluevine’s pitch combines interest-bearing checking with payments and access to working capital. The important comparison is the owner’s actual routine: collecting money, keeping enough available and getting the books settled. A feature list alone cannot answer that.
By June 2026, Bluevine said most revenue came from payments and related fees, subscriptions and float. September transaction materials put active customers at about 175,000 and annualized first-half revenue at $169 million. This had become a business built around holding and moving money, as well as lending it.
On September 28, Valley announced its proposed $340 million purchase, expected to close in early 2027 subject to approvals and other conditions. For Bluevine, Valley offers balance-sheet capacity and broader banking capabilities. For Valley, Bluevine brings digital distribution and operating deposits. The son who started with his father’s waiting problem had helped build something a bank wanted to own.