The first thing BigCommerce sold was relief. In the late 2000s, opening an online store could mean downloading shopping-cart software, finding a host, configuring a database, patching the code and praying that the whole contraption survived a busy Saturday. Eddie Machaalani and Mitchell Harper knew the ritual because their company, Interspire, sold the downloadable cart. Customers liked the product. They disliked becoming part-time systems administrators.
So the Australian founders rebuilt the cart as a hosted service. BigCommerce launched in 2009, opened a U.S. office in Austin and turned an annoying technical chore into a subscription. The move sounds obvious now, after software-as-a-service swallowed the business world. At the time it meant risking a healthy license business to change how the product was delivered, maintained and paid for. Interspire funded the early push; venture money arrived later.
That origin still explains the company better than the latest slogan. BigCommerce makes the repetitive machinery of online selling someone else’s problem. It hosts the catalog, cart, checkout, promotions, security and transaction logic. But unlike a sealed store builder, it exposes enough of the machinery for a serious merchant to rearrange the shop floor.
June 2026
Q2 2026
June 2026
The strange middle is the market
BigCommerce sits in an awkward, valuable gap. On one side are turnkey tools built to get a small catalog online before lunch. On the other are enterprise suites and custom composable stacks that can absorb armies of consultants. BigCommerce offers self-serve plans beginning at $39 a month, but its parent company, Commerce, reported that enterprise accounts supplied 80 percent of ARR at the end of 2025.
That mix tells you where the gravity moved. The best BigCommerce customer is not merely “big.” It is complicated in specific ways. A manufacturer has negotiated price lists and buyers with different permissions. A retailer runs several brands across languages and currencies. A direct-to-consumer company wants an unusual front end without rewriting tax, promotion and order logic. A distributor needs an ERP to remain the source of truth. These are businesses where the exception is the business.
Shopify is the obvious comparison, particularly Shopify Plus. Adobe Commerce, Salesforce Commerce Cloud, commercetools, VTEX and WooCommerce appear in larger evaluations. BigCommerce’s distinction is less a feature checklist than a posture: managed SaaS underneath, relatively open architecture around it. APIs, editable checkout, multi-storefront controls and an app ecosystem give teams more room to preserve odd workflows. The bargain is that flexibility creates decisions. A merchant that wants everything preselected may find the freedom exhausting.
“The storefront remains critical, but it’s no longer the sole driver of demand.”Travis Hess, CEO of Commerce
One engine, many shop windows
The core platform handles familiar retail chores: products, inventory, search, promotions, payments, shipping, analytics and checkout. Multi-Storefront lets an operator run regional or brand-specific sites from one back end. B2B Edition adds company accounts, roles, permissions, quotes, credit terms, custom catalogs and repeat-order tools. That is not glamorous software. It is the software that stops a salesperson from retyping a 300-line purchase order on Friday afternoon.
Catalyst is the more visible expression of BigCommerce’s open argument. It is an MIT-licensed storefront framework built with Next.js, React and the company’s GraphQL Storefront API. Developers get a working commerce funnel instead of an empty repository. Marketers get Makeswift, a visual editor acquired in 2023. The point is to separate the experience a shopper sees from the engine that prices a cart and records an order, without making each team construct every button from atoms.
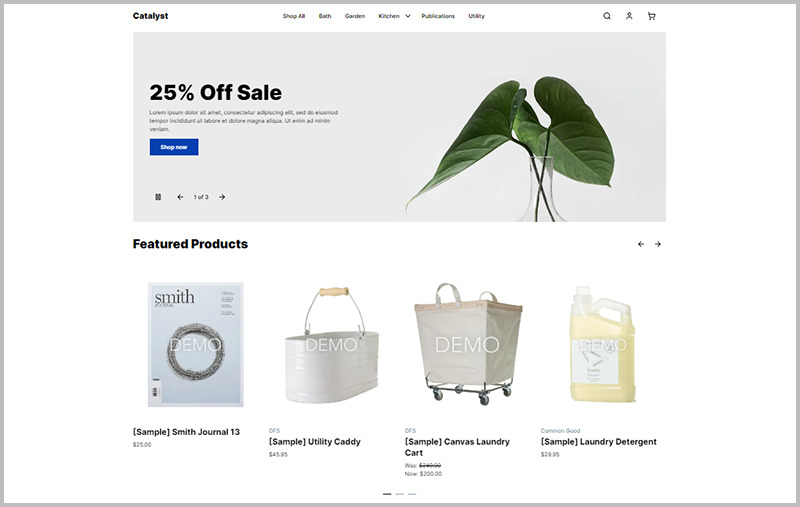
The practical win is division of labor. Engineers can work in a modern codebase while merchandisers update a campaign visually. But headless is not a magic word. It adds hosting, deployment, monitoring and integration choices. BigCommerce itself says Catalyst best fits brands with complex needs and developer resources. A two-person candle shop should not hire a platform team to express its individuality.
The acquisition that aged well
In 2021, BigCommerce bought Feedonomics, a service that ingests messy product data, improves it and sends it to marketplaces and advertising channels. A feed can sound like plumbing until one wrong shipping label makes 13,000 products disappear from Google. Feedonomics built a business around preventing that particular species of panic.
The acquisition now looks like a rehearsal for AI shopping. When discovery starts in ChatGPT, Gemini, Copilot, Perplexity or another assistant, a merchant needs product data that a machine can interpret: correct attributes, live availability, normalized categories, sensible descriptions. Commerce now pitches Feedonomics as the data layer, Makeswift as the experience layer and BigCommerce as the transaction layer. In 2025 it put the three products under a new parent name, Commerce.com, and changed the public company’s ticker from BIGC to CMRC.
Partnerships with PayPal and Stripe connect that data to checkout. BigCommerce Payments by PayPal launched for U.S. merchants in May 2026, placing transactions, balances and payouts inside the control panel. Separate agentic pilots are designed to let shoppers discover and buy on AI surfaces while the merchant keeps control of price, fulfillment and the post-purchase relationship. Google’s Universal Commerce Protocol offers another route. The promise is a shorter distance from “find me a blue chair” to paid order.
There is a risk hiding inside the promise. Every platform wants to own the layer between intent and payment. Protocols are young, customer behavior is unsettled, and beautifully structured data cannot create demand by itself. BigCommerce’s approach works only if these channels send worthwhile buyers and allow merchants to retain enough economics and identity. Otherwise, it is another integration feeding another intermediary.
A reinvention, not a victory lap
The financial picture is disciplined rather than explosive. For Q2 2026, Commerce reported $84.5 million in revenue, almost flat from a year earlier. ARR reached $360.5 million, up 2 percent. Merchant GMV rose 14 percent to $8.8 billion, and the company posted GAAP net income for a second consecutive quarter. Net revenue retention improved to 95.8 percent, but remained below 100 percent - meaning contraction and churn still outweighed expansion across the installed base.
This is what a mature software company changing its center of gravity looks like: enterprise growth, tighter costs, acquisitions woven into a suite and new payment revenue pursued without pretending the old engine has suddenly become a rocket. The parent generated $342.3 million in 2025 revenue and $31.7 billion in merchant GMV. The vast difference between those numbers is the model. BigCommerce charges for software and services around commerce; it does not book the merchant’s sales as its own.
- Several storefronts share one catalog
- B2B prices and permissions matter
- APIs and checkout control are requirements
- The team has developers or an agency
- The catalog and workflow are tiny
- Fastest setup beats flexibility
- Deep customization lacks technical ownership
- A required integration is missing or costly
What the reader can copy
The founding move is the cleanest lesson. Machaalani and Harper did not invent a new merchant problem. They watched customers struggle with installation, hosting and upgrades around a product those customers already wanted. Then they removed the chores while preserving the useful core. If you run a software company, look for the work customers tolerate only because it surrounds the outcome they value. Hosting was that work in 2009. Product-feed cleanup may be that work in 2026.
The second lesson is architectural. Standardize the dull infrastructure and expose clean seams where sophisticated customers need control. BigCommerce does not ask every merchant to write a tax engine. It does let a capable team replace the storefront, integrate an ERP or customize checkout. This works when customer variation is real and the interfaces stay stable. It fails when “open” becomes a polite word for unfinished, or when the customer must assemble an expensive pile of partners to reach the promised outcome.
The final lesson is about changing your mind before the market forces you. A downloadable cart became SaaS. A small-business tool moved toward enterprise. A storefront company bought a feed manager and visual editor, then prepared for purchases that may not begin on a storefront at all. None of those turns erased the transaction engine. They changed where it sat in the customer’s world.
That is BigCommerce’s current wager: the internet will keep inventing new shop windows, but a merchant will still need one reliable place to know what is for sale, what it costs and what happens after someone buys it. The company does not need to own every window. It needs to make sure the cash register works wherever the window appears.