Ben Markowitz has an unusually useful answer to the question of what a founder actually does. Sometimes, at eight in the morning, the job is helping someone reset a password. The customer has a problem. The business needs to work. A distinguished previous employer is unlikely to be much help with either.
He brought up those support tickets while talking about the distance between the appeal of entrepreneurship and its daily demands. Becoming a founder has acquired a certain social prestige, he observed. Then comes the work you never pictured yourself doing. In his telling, he had to grow into the role. It is an admission with rather more texture than the usual account of somebody being born to start a company.
Markowitz is the co-founder and co-CEO of Clerq, the New York payments business he built with Truett Dwyer. Their target is the moment when an expensive purchase is almost complete: the buyer has chosen, the seller has negotiated, and somebody must now arrange for the money to move. It ought to be the easy part. It has a talent for becoming the complicated part.
That small gap between agreement and payment gives his career its shape. He came from a world that studies businesses and allocates money. Now he runs a business whose usefulness depends on the details of how other people collect it. A password reset belongs in this story because the grand idea and the minor inconvenience meet at the same checkout.
“answering support tickets at 8:00 AM”
Ben Markowitz, on the day-to-day work of founding Clerq
Before the checkout, the investment desk
His education includes Harvard University, where his public profile lists attendance from 2012 to 2016. His career subsequently took him through JP Morgan and Citadel. By the time he and Dwyer started Clerq in 2022, they had been investing in fintech and payments. They had spent time examining the machinery before deciding to build a piece of it themselves.
That background matters to the kind of problem they chose. Financial services can look deceptively straightforward from the screen: a button, a balance, a confirmation. Behind that screen sit institutions with different incentives, requirements and tolerances for risk. A nicer interface can make a customer happier while leaving the underlying economic arrangement untouched.
Markowitz’s founder conversations return to those complications. Building in financial services requires attention to the surrounding system as well as the technology. For somebody arriving from payments investing, the question is larger than whether a transfer can be initiated. It includes who bears the risk, what the merchant pays and whether the product fits the working day of the person using it.
The transition also changes the meaning of being right. An investor can develop an explanation of why a market should change. A founder must persuade a customer to change a habit, train an employee and return the next call. There is no special exemption for a persuasive spreadsheet. Clerq’s story takes place in that less tidy territory.
The buyer has already said yes
Consider the payment problem Clerq chose. Car buyers can spend hours reaching a deal, then find themselves needing a cashier’s check or a wire. A dealer accepting a card may face fees that are uncomfortable on a large transaction. The alternatives bring their own manual steps. Everybody has arrived at the end of the sale, yet the sale still has somewhere else to go.
Markowitz and Dwyer saw a mismatch between payment products built around cards and businesses handling large purchases on sensitive margins. Their response was account-to-account payments aimed at high-ticket merchants. Rather than require another consumer app, Clerq puts the payment experience into the merchant’s existing process. The buyer pays from a bank account.
The choice of market is the interesting part. Changing how somebody buys an inexpensive everyday item means competing with a habit that probably works well enough already. A major purchase presents a different bargain: the buyer may already be dealing with card limits, a surcharge or a trip to obtain a check. Convenience has a different starting point.
There is also a useful arithmetic lesson hiding in the purchase price. At a hypothetical three-percent processing fee, a $30 payment carries a 90-cent cost. Apply that same percentage to $30,000 and the cost becomes $900. This is an illustration, not Clerq’s quoted pricing. The percentage has stayed perfectly still. Its importance to the seller has changed considerably.
Clerq’s published product description includes payment links, invoices and a dashboard for following payments and reconciling payouts. It also says the company guarantees the payments it processes. Those features address different people around the transaction: the customer paying, the employee collecting and the person responsible for the books afterward. A checkout has a surprisingly large supporting cast.
A place at the table
The partnership with Dwyer sits at the center of Markowitz’s working life. They founded Clerq together and share the chief executive title. It is an arrangement that makes their shared investment background visible in the business, without telling us how any particular Tuesday’s decisions are divided. The public record supports the partnership; the daily choreography belongs to them.
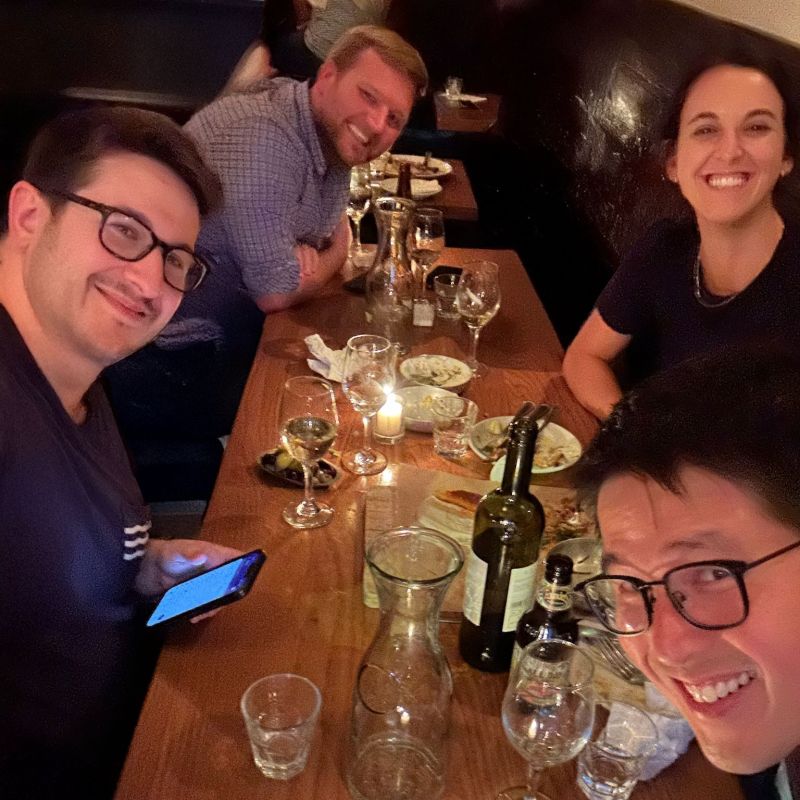
Fika Ventures backed their pre-seed in 2022. FirstMark became another investor, and 645 Ventures later led the Series A. A candid photograph of Markowitz and Dwyer with Fika’s Gabriella Brignardello and TX Zhuo catches that network in a more ordinary setting: a restaurant table, glasses, plates and a phone. Financial infrastructure, it turns out, can have dinner.
The relationships extend beyond a fundraising announcement. In September 2026, Markowitz was credited with introducing the team at commercial real estate software company Henry AI to FirstMark during Henry’s seed round. It is a small detail, but a concrete one: a founder can participate in the startup world by connecting other people, as well as by raising money for his own company.
These connections give the story a scale beyond the solitary founder portrait. Clerq is a collaboration with a co-founder, employees, merchants and investors. Its products also have to work inside the systems customers already use. There is a great deal of other people’s reality to accommodate before an idea becomes a routine payment.
The round without an AI costume
In October 2025, Clerq announced a $12 million Series A led by 645 Ventures, bringing its reported total funding to $21 million. Existing investors participated, alongside strategic investors Friedkin and Yossi Levi, the founder of Car Dealership Guy. The announcement placed Markowitz and Dwyer’s work in front of a wider audience in automotive and finance.
The company also reported sixfold revenue growth over the preceding year and hundreds of millions of dollars in processed payments. These were company-level results reported at that time. They describe the commercial progress of the platform, rather than a personal fortune or a permanent growth rate. Their value in this story is that the investment thesis had acquired paying users.
Markowitz’s account of the fundraising process contains an instructive choice. He said Clerq had potential uses for AI, but the founders did not emphasize it excessively in their pitch. That meant narrowing the investor pool when some investors were concentrating on AI exposure. They kept the company’s payment problem at the center of the conversation.
A fashionable vocabulary can make a pitch sound current. It cannot settle whether a dealer wants the product. Markowitz’s decision is interesting because it connects the money-raising story to the customer story: Clerq needed investors willing to engage with what it was actually building. The practical questions about cost, risk and adoption still had to be answered.
His near-term priorities after the round were correspondingly specific. Clerq had signed large enterprise contracts and was concentrating on rolling them out. It was also pursuing opportunities beyond its initial automotive focus, including powersports and other high-ticket categories. Signing a contract is a milestone. Getting a product used across a customer’s operations is the work the milestone creates.
Led by 645 Ventures, with existing and strategic investors participating.
The ticket in the inbox
This brings us back to the morning support request. Passwords are an almost comically modest subject for somebody who has worked at Citadel. Yet the anecdote makes the change in Markowitz’s career unusually legible. Once a customer depends on your company, a minor obstacle becomes part of your responsibility. It cannot be dismissed because the original business plan concerned something more interesting.
He discusses entrepreneurship with an awareness of its ordinary burdens: finding people, serving customers and continuing through tasks that do not resemble the polished version of the job. Dez Fleming, his interviewer, describes him as intellectually curious. The conversations themselves offer a more concrete impression of that curiosity: he is willing to examine how incentives and customer behavior complicate a seemingly simple payment idea.
The founder’s advantage, in this account, has to survive repeated encounters with actual users. A merchant may judge the product by whether a payment succeeds and a question gets answered. The founder may judge the company by market size and revenue. Both views can be reasonable. The business has to keep them in the same room.
Markowitz’s stated ambition is to build Clerq’s position in automotive and powersports and expand into additional markets. It is an ambition grounded in a repeated problem: expensive purchases still need a way to finish. The details will vary from one industry to another, which is why the company emphasizes workflows tailored to its customers.
There is a quieter preference in his public life, too. Asked about a fall destination around New York, he chose the Hudson Valley and the Amtrak ride along the river. After all the discussion of moving money, he offered a recommendation for moving himself. A train journey is a pleasant reminder that efficiency need not be the only thing worth noticing.
For now, the shape of his story is clear enough. A payments investor became a payments founder, and the work grew more personal as it became more practical. The customers have businesses to run. The buyers have purchases to finish. Somewhere in the middle, Ben Markowitz has a company to build - and, occasionally, a password to help reset.