Rory O’Reilly had a debit card to sell and a customer who would not do the obvious thing. The customer used the Millions card in person. Online, the old payment details stayed put. O’Reilly called to ask why. Updating them was a nuisance, came the answer. He thought the customer was being unreasonable. Then he called someone else and heard the same complaint.
It is an awkward discovery for a founder: the people using your product may understand its shortcomings before you do. O’Reilly and his brother, Kieran, built a way to move the card into customers’ merchant accounts. Investors in banking wanted the tool for themselves. The brothers eventually pivoted the business to Knot, with Rory as CEO and Kieran as CTO. A chore had become the business.
The pivot is the useful way into O’Reilly’s story. There are Harvard years, animated GIFs, a fellowship and several ventures along the route. But the revealing moment is a telephone call on which he initially disagreed with a customer. His next company depended on taking that customer seriously.
The first closed window
His earlier education in selling happened at street level. At nine, O’Reilly handed out fliers for his parents’ business. They sold shoes, pots, pans and other merchandise; he and Kieran helped on weekends. He remembers approaching a car stopped at a light. The driver looked at him and rolled up the window. Embarrassed, he went back to his mother.
“Go to the next car. Don’t give up.”
His mother’s advice, recalled by Rory O’Reilly
The instruction was small enough for a child to carry out. He did. Years later, he still uses that encounter to explain his relationship with rejection. There was no elaborate philosophy to memorize, only another car to approach. An unanswered sales pitch had a practical remedy.
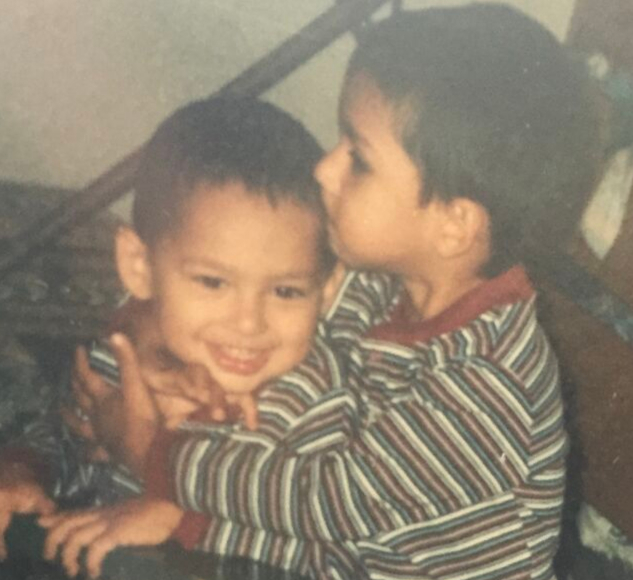
His work has since involved pitching banks and fintech companies. The venues have improved considerably. The possibility of a closed window remains. That childhood memory gives a more human scale to the job than a list of investors would: someone has to make the approach, hear the answer and decide what to do next.
A checkout time, and a website taking off
O’Reilly attended Harvard from 2012 to 2014. He and Kieran left and moved to San Francisco to work on the venture that became gifs.com. In an August 2014 account, Rory described asking a hotel for a later checkout while the team worked on GifYoutube. The hotel granted another hour. A server migration was under way. Housing was still unresolved.
He had posted the project to Hacker News despite feeling nervous. He wrote that, within a day, it reached the top of Hacker News, Product Hunt and Reddit’s technology community. Attention arrived faster than settled living arrangements. The product made it easy to turn YouTube videos into animated GIFs, a wonderfully modest object to carry such a large personal wager.
His account ended with two goals: changing how people used GIFs and finding somewhere to stay the following day. The juxtaposition did the work. A startup could have a vast imagined audience and a very immediate checkout deadline. Both belonged on the same to-do list.
In June 2015, the Thiel Foundation named both brothers to its fellowship class. Its announcement identified Rory as a 20-year-old from Elmont, New York, working on animated GIFs. The fellowship offered $100,000 over two years, alongside mentorship and a network, to young people building outside college. It provided a formal program around an already unconventional decision.
Builds GifYoutube
Gems / Expand
Millions
Knot
The ventures between the milestones
GIFs were followed by Gems, later called Expand. The brothers’ 2017 project addressed the market for small human tasks, the sort of work coordinated through Amazon Mechanical Turk. Its proposed alternative used blockchain technology. In January 2018, O’Reilly published a roadmap covering a testnet release, open-source front-end code and an API for creating jobs.
The roadmap is a glimpse of him at work before Knot: explaining what had been built, what was due next and how outside participants might use it. Some entries described completed demonstrations; others were promises with dates attached. Keeping those separate matters. A roadmap records a founder’s intentions, while a working product has to survive actual use.
His publishing continued through the Expand period. By March 2020, he was announcing that Expand was open source. These ventures belong in his biography even though the present-day story is about payments. Leaving them out would make the journey look more predetermined than the sequence of products suggests.
The card people liked, and the chore they avoided
Millions came next, in 2020. The debit-card business tied spending to opportunities to win cash prizes. It was a consumer proposition with an obvious social hook. O’Reilly later recalled audiences of more than a million followers apiece on TikTok and YouTube. The numbers demonstrated that the brothers could get attention. Attention, however, had to turn into card use.
In his retrospective, he described users resisting the task of changing payment methods even when they liked Millions. He connected the lesson to earlier work making fragmented, poorly documented APIs usable for gifs.com. Knot would require another encounter with messy systems, this time inside the merchant accounts where people had already stored their cards.
That continuity is more interesting than the difference between GIFs and banking. The objects on the screen changed. The underlying work of making someone else’s system do something useful was familiar. O’Reilly described the accumulated engineering effort as a basis for broader merchant connectivity, including subscription actions and item-level purchase data.
The practical distinction is easy to appreciate. A person can carry a new card while online shops and recurring services continue to remember an old one. The physical wallet and the saved payment method have different memories. Any business trying to become the everyday card has to contend with both.
Knot’s issuer customers embed its tools in their own products. CardSwitcher updates saved payment methods on a user’s behalf; the wider product range includes transaction details, account updates and subscription management. O’Reilly’s company is based in New York. Its work takes place inside experiences bearing other companies’ names.
Basketball, board games and a first check
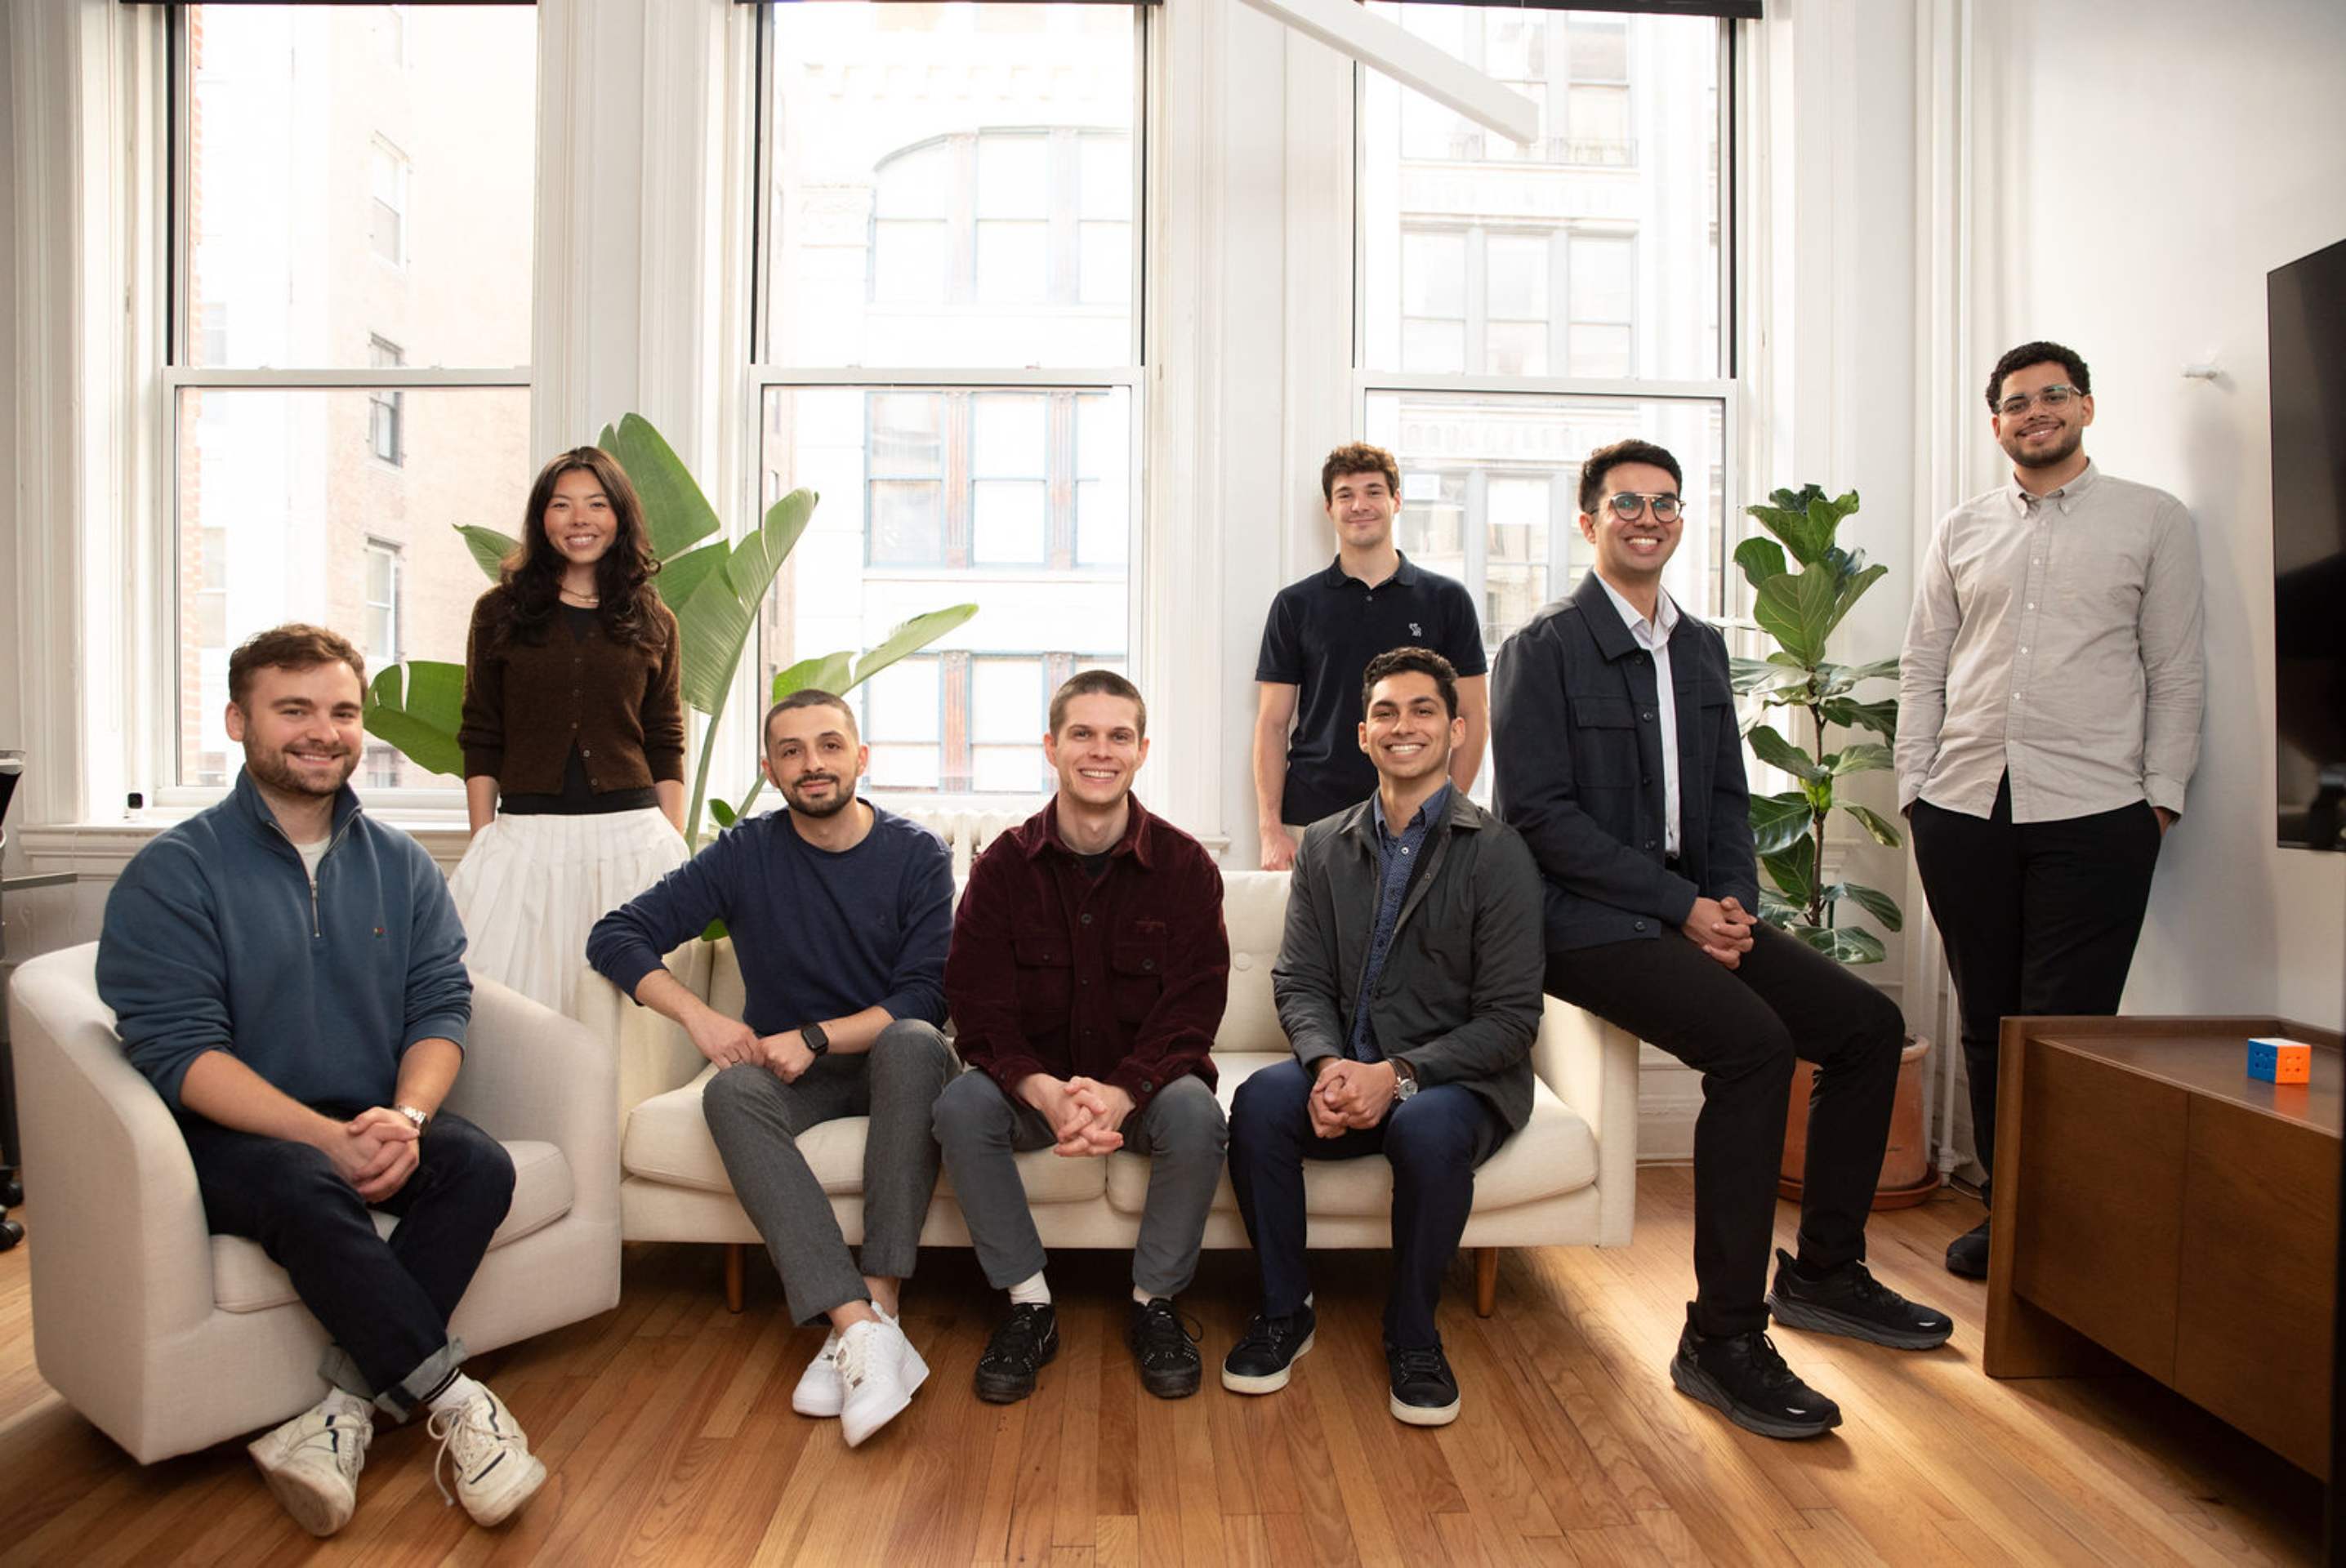
There is a social life around those businesses, too. Baselayer co-founder Jonathan Awad describes meeting the brothers in the casino halls at Money20/20, where a gathering of fintech friends was becoming an impromptu event. Later came basketball games hosted by Rory and board-game nights the brothers co-hosted. Awad remembers a circle that included founders, investors and other Thiel Fellows.
When he and Timothy Hyde described Baselayer, the brothers committed to investing within minutes, according to Awad. They supplied its first check. His recollection adds an investor’s role to O’Reilly’s operating career and a friend’s view of how the relationships formed. The basketball and board games are useful details precisely because they are ordinary. People met, spent time together and eventually backed a company.
The brothers also returned to Harvard in a different capacity. Knot identifies Rory as a Harvard Innovation Fellow; Awad recalls them teaching entrepreneurship with Paul Bottino and a Twitter co-founder. The institution they left became a place where their experience could be shared. That is a less tidy ending than either a graduation story or a tale of permanently turning one’s back.
The customer’s complaint reaches the banks
In August 2023, Knot announced a $10 million Series A led by Nava Ventures, with American Express Ventures and Plaid participating. The funding was intended to expand merchant support and scale the service. It gave the pivot a concrete institutional context: companies around the card business were putting money behind a tool for changing saved payment details.
American Express subsequently teamed up with Knot on functionality for eligible US consumer and small-business card members. In September 2024, the companies described an easier way to add card-on-file information. O’Reilly framed the relationship around connecting users and merchants. A problem first encountered in his own debit-card business was now being addressed with an established card issuer.
The next steps have been specific, too. In July 2026, Knot announced a partnership with RBC that marked its first expansion beyond the United States. RBC cardholders could set their card as a saved payment method at supported merchants through the bank’s mobile app. Geography changed; the familiar task remained.
August brought a Venmo collaboration. Depending on the participating merchant, users could save their Venmo Debit Card or link Pay with Venmo. For Knot, this was its first provision of a proprietary checkout solution as a default payment option. The original card-switching capability was extending to a payment method beyond the card itself.
By October, another Canadian application had joined the story. KOHO’s instructions explain how users can link their virtual card to supported merchants from its app, with the update powered by Knot. The service changes the payment method saved at a merchant; it does not change the subscription itself. Even as the network grows, the precise action still matters.
What comes after the saved card
O’Reilly now describes a merchant connectivity layer covering more of the relationship between shoppers and businesses: buying, returning, subscribing, cancelling, reordering and tracking deliveries. In a 2026 essay excerpt, he set that ambition alongside payment networks and bank connectivity. It is his thesis about where a further layer of financial software might develop.
The ambition is broad, but his biography supplies a smaller test for it. Can the product handle the task a customer has been putting off? That question led from a debit card to a separate company. It also keeps the narrative grounded in something more recognizable than an infrastructure diagram: a person looking at an account-settings screen and deciding to deal with it later.
Rory O’Reilly has spent his career asking people to try something. Sometimes the answer arrived as a rolled-up window. Sometimes it arrived as a complaint he did not initially like. Knot began when he stayed with the complaint long enough to build a response.