On July 4, 2000, a bank opened when much of America was taking the day off. Its name was Bank of Internet. Its founders had chosen the holiday deliberately: independence from the inconvenience and expense of branch banking. The idea had the pleasing neatness of a good invention. Remove the buildings. Reach customers through a screen. Keep the useful parts of banking.
- Consumer accounts are the front door; commercial lending, custody and clearing extend the business.
- A roughly $55 million acquisition brought adviser technology and access to client cash.
- The model depends on funding costs, lending judgment and integrations working together.
That origin still explains Axos’s appeal. It does less to explain what the company has become. A person opening a savings account sees one business. An independent financial adviser sees another. Behind both sits a question that makes Axos interesting: how many financial services can share the same machinery?
The branch was only the beginning
The holding company was incorporated in 1999; the bank began operating the following year. Co-founders Jerry Englert and Gary Lewis Evans helped turn the internet-bank proposition into a regulated institution. Public ownership followed in 2005. Gregory Garrabrants became chief executive in 2007.
Digital delivery was a method, not a complete business plan. The bank still needed deposits, borrowers and a reason for customers to choose it. A website could reduce friction, but it could not supply those relationships by itself. Over time it expanded into commercial banking, securities services and investing. In 2018, the old BofI identity gave way to Axos. A name built around a delivery channel had become too narrow for the collection of businesses underneath it.
The $55 million door into somebody else’s business
Consider an acquisition completed in August 2021. Axos bought E*TRADE Advisor Services from Morgan Stanley and renamed it Axos Advisor Services. The final purchase price, including working-capital adjustments, was $54.8 million in cash.
The business arrived with approximately $24.8 billion in assets under custody and around 200 adviser relationships. Those securities belonged to clients. Axos had not bought a $24.8 billion investment portfolio. It had bought a platform that helped independent advisers look after their clients’ investments.
Inside the transaction was another number: approximately $1.2 billion in client cash sweeps. Cash held alongside investments can supply deposits or generate revenue through partner banks. Axos’s own acquisition explanation made that connection explicit. Custody could bring fee income, technology and low-cost funding that supported lending.
A custody platform can connect three businesses: serving advisers, holding client cash and funding loans.
The strategic reading is straightforward. An adviser relationship offers access to clients who may also need mortgages, deposit accounts or other banking services. Buying the infrastructure can shorten the route to those relationships. The acquisition price matters; so does what the buyer can do with the business once it arrives.
relationships↓Custody +
client cash↓Bank funding +
lending
Conceptual flow. Client securities remain client assets.
Put the bank where the work happens
For households, Axos offers familiar tools: checking, savings, mortgages, personal loans and investment services. Axos ONE combines checking and savings. The app brings banking functions together, although promotional screens should never substitute for reading an account’s actual terms.
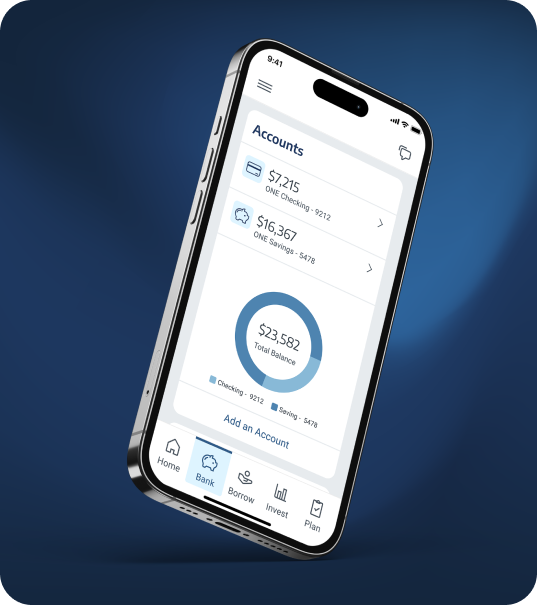
Businesses encounter a different menu: deposits, treasury management, equipment finance and commercial lending. Advisers need custody and banking for their clients. Broker-dealers need clearing. These are distinct customers with distinct operating problems, connected by a financial group that can supply several components.
The January 2026 Qualia partnership shows the practical appeal. Title and escrow companies already work inside closing software. Axos joined Qualia’s bank partner network to integrate services including wires, daily clearing and positive pay. Moving money and checking transactions become part of an existing workflow. Fewer manual steps are a concrete benefit.
White-label banking applies a related idea to advisers. Their brand remains visible while Axos supplies banking capabilities. The distribution channel is a professional relationship the client already has. That is a different route from persuading every household to discover another bank independently.
Cheap distribution still has a bill
Axos earns much of its money through an old banking calculation: interest received on assets minus interest paid for funding. Fees from custody, clearing and other services add income. Removing branches changes expenses; it does not remove the need to price risk.
Funding itself has a price. In September 2025, Axos priced $200 million of subordinated notes with an initial 7% coupon. The stated uses included repaying older notes approaching a higher reset rate. Even a digital bank must pay attention to its own borrowing bill.
Fiscal 2026 net income reached $490.4 million. But the annual results also included a $21 million legal accrual at Axos Clearing. The consolidated efficiency ratio rose from 46.84% to 49.49%; this measures operating expense against net interest and non-interest income. A rising ratio means more expense per dollar of that income. Growth alone does not settle the cost question.
The next acquisition is a software company
In July 2026, Axos closed its purchase of Arc, a cash-management and capital-markets platform serving technology and growth companies. Arc also brought financial software and AI capabilities. The promise is another combination of software, services and bank resources; the integration determines how much of that promise becomes useful.
Deposits were expanding too. Axos acquired about $2.3 billion of Jenius Bank consumer deposits in May, then approximately $1.9 billion of Capital One IRA deposits in September. These were separate transactions, with different customer groups.
The copyable lesson is to examine a customer’s whole workflow and buy distribution as carefully as products. The conditions matter. Expensive deposits, loan defaults or difficult integrations can overwhelm savings from digital delivery. Customers who need frequent branch visits may prefer another bank. Axos’s experiment asks a practical question: once banking leaves the building, where should it go next?
Follow the money
Explore Axos Bank, Axos ONE and banking insights. Read the fiscal 2026 results, the custody acquisition announcement and the Arc announcement.
Find Axos on LinkedIn, X, Instagram and Facebook. Watch the official YouTube channel.