The useful thing about a bank is how often you can forget it exists. Your salary arrives. Your card works. The mortgage payment leaves on Tuesday. At Bank of America, the interesting engineering problem begins with that apparent absence: how do you make an institution serving nearly 70 million clients feel uneventful?
- A U.S. banking network connects everyday accounts with Merrill investing and global corporate finance.
- Erica turns repeated financial questions into a product that can improve over time.
- Automation saves effort, but mistakes and poor customer recourse carry real costs.
01 A merger with a much older memory
There are two useful birth dates. In 1904, A.P. Giannini founded the Bank of Italy in San Francisco to widen access to banking. After the 1906 earthquake, it helped finance the city’s recovery. In 1998, NationsBank and BankAmerica merged to create the modern Bank of America. One date explains an inherited ambition; the other explains the machinery.
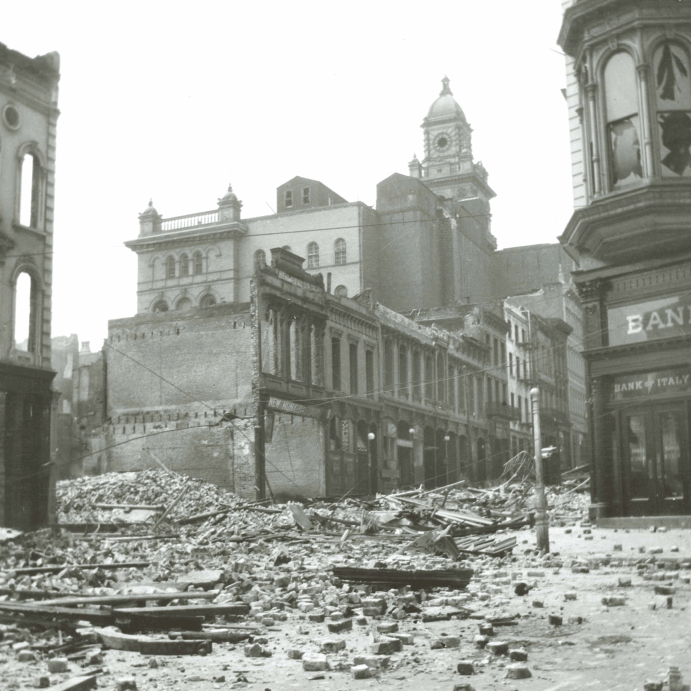
The machinery matters. This is a company assembled from different financial capabilities, now sold through a common relationship. A customer can start with a checking account, borrow for a home, invest through Merrill and eventually need trust services. A growing business can move from operating accounts to commercial credit and capital markets advice. The bank wants to remain useful as the problem changes.
02 The app is the front door
For individuals, the menu is familiar: checking, savings, cards, mortgages and auto loans. Merrill adds investing and financial advice; the Private Bank handles more complex wealth, trust and estate needs. Businesses use lending, payments and treasury services. Corporations and institutional investors also buy underwriting, trading and risk management. The expertise runs from household cash flow to the financial plumbing of a multinational.
Against JPMorgan Chase, Citi or Wells Fargo, breadth alone is hardly an exclusive claim. Bank of America’s competitive case is the combination: digital access, a large physical network and several kinds of advice within one group. Compared with a specialist investing app or an online bank, that combination may reduce the number of separate relationships a customer manages. It does not guarantee the best rate or lowest price.
Active digital banking users. A service decision repeated at this scale becomes a business decision.
The economics follow the relationship. Deposits help fund loans and securities; the bank earns a spread after funding costs. Advice, asset management, investment banking, treasury and trading bring other revenue. In 2025, revenue net of interest expense reached $113.1 billion. About 53% came from net interest income and 47% from the remaining revenue streams. This is a diversified financial business, with all the interest-rate and credit risks that implies.
03 A minute is a business model
Erica, the virtual financial assistant launched in 2018, offers a useful way into the technology strategy. Its work includes helping customers find transactions and understand their accounts. These are small jobs. They are also jobs that recur. In April 2024, the bank said its data science team had made more than 50,000 performance updates since launch. The product’s history is full of maintenance.
The cost is substantial. Bank of America reported $13 billion in technology spending in 2025, with more than $4 billion directed to new initiatives. Its July 2026 EricaAssist announcement put annual technology spending at $14 billion. These are companywide budgets, covering much more than an assistant. Treating the whole sum as an AI bill would miss the infrastructure that makes any useful answer possible.
More than $4bn within that total funded new initiatives.
By July 2026, the bank said more than 18,000 service representatives used EricaAssist, which surfaces guidance during calls. It reported average call times falling by nearly a minute. A minute sounds trivial until it becomes a repeated unit of labor. The useful question is whether the customer’s problem gets resolved, with fewer transfers and less repetition.
“EricaAssist reflects our high tech, high touch approach.”
Ashley Ross · Bank of America · July 2026
The people operating those systems are part of the investment. The bank raised its U.S. minimum hourly wage to $25 in October 2025, and its Academy provides training and professional development. Its stated purpose is to improve financial lives through connections. Those commitments offer a concrete test: can staff explain a decision, fix an exception and help a customer move forward?
04 The machine has a memory problem
There is a less comfortable example of repetition. In 2022, federal regulators fined the bank $225 million over unemployment-benefit distribution. The CFPB said a faulty fraud-detection program froze legitimate accounts and left customers with inadequate recourse. A system designed to stop the wrong person could also stop the right one. Once that happened, efficiency became a poor measure of service.
Fees tell another part of the story. In 2022, the bank eliminated consumer non-sufficient-funds fees and reduced overdraft fees from $35 to $10. It credited feedback from its National Community Advisory Council. In July 2023, regulators separately ordered more than $100 million in customer redress and $150 million in penalties over repeat fees, withheld rewards and unauthorized accounts. The earlier redesign and later enforcement should not be confused with a clean redemption story.
05 A payment takes the long way round
The same attention to recurring tasks appears in corporate banking. CashPro helps treasury teams manage payments and liquidity. Its September 2026 Payments Insights launch added analysis of payment efficiency and working capital on U.S. accounts, developed with client advisory input. Later that month, Bradesco completed a cross-border pilot through existing Swift connectivity, delivering Hong Kong dollars through Hong Kong’s Faster Payment System. Joining existing systems can be useful innovation.
What can another company copy? Start with the frequent task. Keep improving it. Give exceptions a human escape route. That is an editorial lesson, not proof that every Bank of America product succeeds. It depends on reliable data, patient investment and accessible support. For a customer who wants the highest savings yield, the combined relationship may be unpersuasive. For someone juggling banking, borrowing and investing, fewer moving parts may be the point.
Follow the money. And the people.
 Watch · CEO interviewBrian Moynihan at Axios House DCJuly 15, 2026 · YouTube ↗More from Bank of America on YouTube ↗