In September 2026, Atlanticus sold the Mercury name and kept the credit card receivables. The price for the trademark and related intellectual property was $27.5 million in cash. The loans stayed put. A brand has value. So does knowing what a borrower is likely to do next.
- Atlanticus helps bank partners offer credit to consumers outside prime lenders’ comfort zones.
- Its business combines analytics and servicing with buying and financing receivables.
- Recent deals expanded its card portfolio and removed its Auto Finance business.
The sale after the decline
Consider the familiar retail predicament: a customer wants a necessary purchase, the store wants a sale, and the first financing application comes back declined. Everyone is still standing in the same place. The problem has changed. The merchant now needs a financing option built for a customer the prime lender has passed over.
Atlanticus occupies that opening through Fortiva Retail Credit. Its second-look programs help participating banks extend financing at the point of sale. In June 2024, Synchrony selected Atlanticus for an expanded, multi-year preferred second-look relationship covering private-label cards and installment loans. A large prime-credit provider became a distribution partner for a business serving customers beyond its initial approval boundary.
That arrangement explains Atlanticus’s place in the market more clearly than calling it a fintech. The retailer supplies the moment of need. The prime lender supplies an existing financing relationship. Atlanticus supplies another route through it. Competitors include other second-look programs; lease-to-own is another option merchants may present after a decline.
needs financing
declines
offer considered
Simplified sequence. A second application does not guarantee approval.
The bank behind the card
Consumers encounter Fortiva, Aspire, Imagine, Mercury or Curae. Banks issue the credit. Atlanticus contributes underwriting technology, marketing, program management and servicing. Its website identifies The Bank of Missouri as issuer for Fortiva, Aspire and Curae, and WebBank for Imagine. Curae addresses healthcare expenses; Fortiva Retail Credit works through merchants and service providers.
The company calls its main business Credit as a Service. Read the financial filing and the phrase becomes less weightless. Atlanticus generally purchases receivables generated by bank partners at the loan’s principal amount. It earns interest, fees and service-related income, pays bank partners, and finances the assets. A subscription business can lose a customer. A credit business can lose the money it advanced.
For a consumer, the useful doorway is the particular card or financing program. For a retailer, it is the merchant relationship. Fortiva says it integrates with existing sales systems and makes decisions in seconds. Merchant pricing is tailored to the arrangement. The practical benefit is a financing process that fits the transaction already underway.
A long memory, including the awkward parts
The business began in 1996 as CompuCredit. Founder David Hanna had already worked in lending and distressed receivables. Jeff Howard, now chief executive, joined in 2001. Atlanticus’s claimed advantage is the accumulated record of repayment and loss across economic cycles. Fortiva Retail Credit says its models use FICO alongside other factors. A score starts the inquiry; observed behavior helps inform the next decision.
Experience includes an uncomfortable chapter. In 2008, CompuCredit agreed to at least $114 million in consumer redress to settle federal charges concerning deceptive credit-card practices. Regulators challenged, among other things, disclosures about available credit and borrowing costs. The Atlanticus name arrived in 2012. That history makes clarity about fees central to evaluating today’s inclusion promise.
“helping meet the needs of the financially underserved”
Jeff Howard · Atlanticus company statement
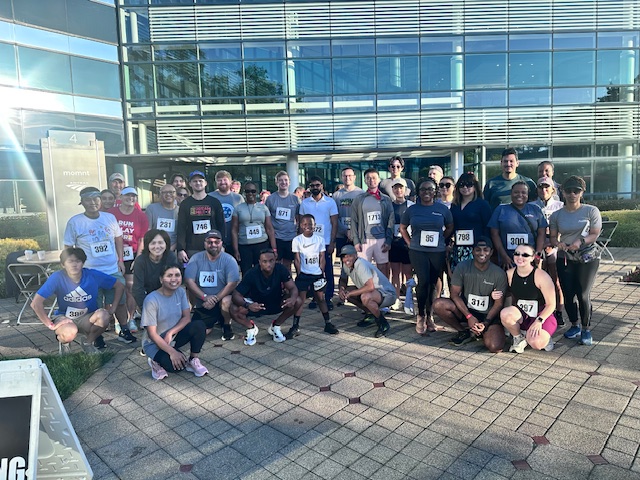
The workforce retains institutional memory. Atlanticus reports average employee tenure above eight years, with internal promotion, training and paid volunteering. Its company photographs show colleagues at Lauren’s Run. The inference is modest: retaining people may help a lender remember the circumstances behind its numbers. Longevity alone cannot establish that its decisions are good.
The price of another chance
Access is useful only in relation to its price. Fortiva’s published general-purpose card pricing addendum lists purchase APRs of 29.99% or 36%, first-year annual fees from $49 to $175, and potential maintenance fees after the first year. The actual offer controls. These figures belong to that card disclosure; they should not be applied to every Atlanticus-supported product.
The difference matters at the kitchen table. An approval answers whether credit is available. It does not answer whether the purchase remains affordable after interest and fees. Atlanticus’s mission is to broaden access; the customer’s calculation still concerns the money left after making the payment.
The company pays for capital, too. Its August 2025 offering raised $400 million of senior notes at a 9.75% coupon. Multiplication gives $39 million of annual coupon interest before fees or changes in principal. Lending depends on the margin left after funding costs, servicing and credit losses. More approvals can increase revenue while making that margin worse.
Calculated on the full principal balance. Excludes issuance costs.
Buy the portfolio. Sell the name.
Mercury expanded Atlanticus into near-prime credit in September 2025, adding about 1.3 million card accounts and $3.2 billion of receivables. The later annual filing reported roughly $166.5 million in cash consideration, plus contingent payments. Buying the platform brought existing borrowers, operating capabilities and another segment of the credit market.
A year later, Atlanticus sold the Mercury brand rights while retaining those receivables and transitional licensed use. It also sold CAR, its entire Auto Finance segment, for about $71.2 million in cash and a seller note. Management’s stated reason was to concentrate capital and attention on consumer-credit opportunities. The sequence suggests a sharper focus on earning assets and the operations supporting them.
The idea that travels
By June 2026, Atlanticus reported more than 6.3 million accounts served, counting active accounts and open credit lines. Scale makes the distribution idea worth studying: solve the problem immediately after an existing process stops working. A merchant need not invent a new buying occasion. A bank need not build every supporting capability itself.
The less portable part is the machinery underneath. Distribution, repayment experience and access to capital have to arrive together. A polished application can be copied quickly. Learning how the resulting accounts perform takes time, and the lender has to finance that learning while customers make, miss or resume their payments.
Copying that insight requires restraint. Old repayment data can mislead when borrowers’ circumstances change. Funding can become expensive. A second-look offer may be unsuitable when repayments exceed a household’s capacity or cheaper credit is available. Atlanticus’s proposition ultimately rests on three judgments holding together: the customer can use the credit, the customer can repay it, and enough remains to fund the next loan.