At Performance Automotive, paying a supplier meant dealing with whatever happened afterward. There were checks that went uncashed, questions about payments, and electronic transfers whose recipients needed better information. Moving money was one task. Explaining where it belonged was another. REPAY’s account of the dealership group’s experience offers a useful place to begin: with the administrative debris a payment leaves behind.
- Payments built into the software businesses already use.
- Cards, ACH and checks, with the records attached.
- A $372 million KUBRA deal expands household billing.
REPAY connected its vendor-payment service to DealerBuilt, the dealership management software Performance Automotive already used. In the first month, the group reported that 76% of payments went electronically and 56% of payment volume went by virtual credit card. Combined savings and rebates exceeded $5,000. Those are one customer’s reported results, but they expose the attraction: fewer loose ends, with money attached.
An overlooked place to put a payments company
John Morris and Shaler Alias founded REPAY in 2006 around an underserved consumer-finance market. Their customers included merchants that did not typically accept electronic payments. The founders built a proprietary gateway with multiple payment channels, tailored to those businesses. It was a specific opening: help a lender collect a repayment in the way its borrower could actually make it.
Morris brought experience from check verification and processing at Security Check Atlanta, as well as accounting and corporate finance. That background makes REPAY’s preoccupation with the unglamorous parts of payments less surprising. Settlement, records and reconciliation are where an apparently simple transaction becomes somebody’s afternoon.
REPAY earns most revenue from volume-based processing fees and fixed transaction fees. As clients process more payments, those fees grow. The company serves consumer lenders, auto-finance businesses, mortgage servicers, credit unions, healthcare organizations and business finance teams. It accepts cards and ACH bank payments through web portals, mobile, text and phone channels. Its Instant Funding service sends approved loan proceeds to eligible debit or prepaid cards in minutes, including weekends and holidays. Collection and disbursement become connected jobs.
The payment belongs where the work happens
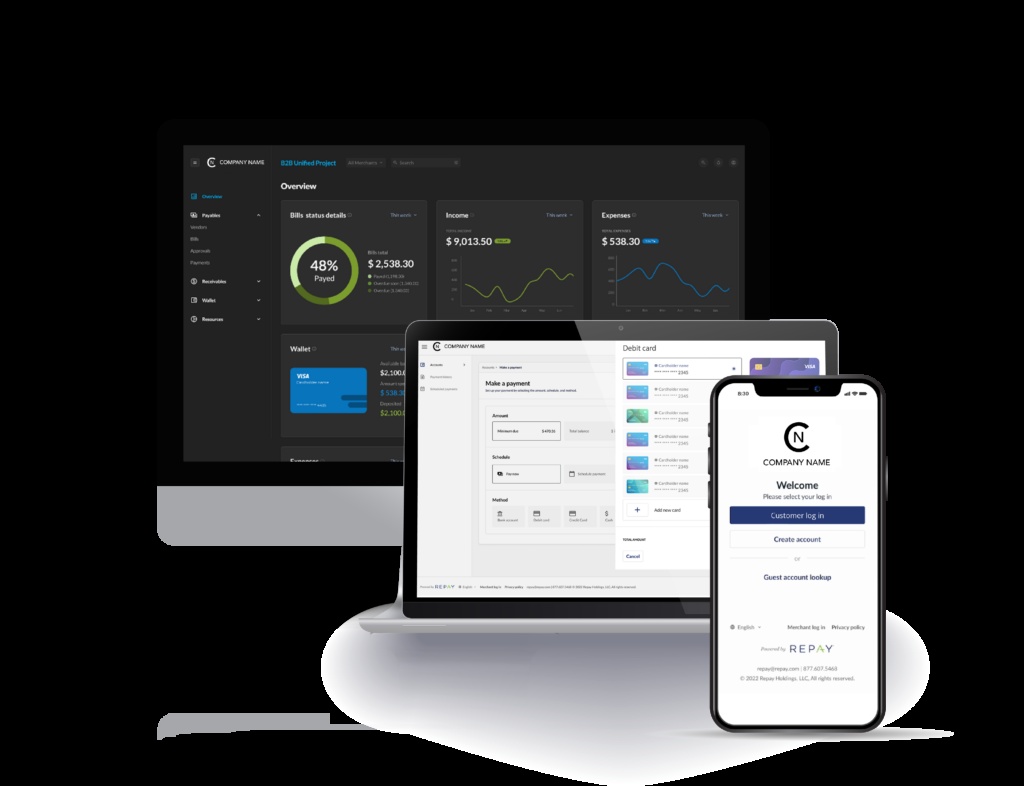
For a finance department, the distinction between accounts receivable and accounts payable is straightforward: money coming in, money going out. REPAY works on both. Its vendor-payment offering supports virtual cards, ACH and checks, with vendor onboarding and support. A supplier can still need a check. Automation has to accommodate that awkward fact.
The distribution strategy is equally practical. REPAY integrates with the software customers already operate: accounting systems such as Sage and Acumatica, loan platforms such as LoanPro, and industry systems such as DealerBuilt. LoanPro users can offer recurring or one-time payments and see payment reporting within an integrated workflow. Re-entering a transaction in a second system is precisely the kind of work this arrangement is meant to remove.
An October 2026 partnership extended that idea into Emburse’s Spend, Pro and Enterprise platforms. Domestic vendor payments can run through ACH, virtual card, digital disbursement or check, inside the approval process. REPAY’s business-payments executive Darin Horrocks described the aim as keeping payment execution within the existing workflow.
BILL offers an alternative for AP and AR automation; American Express One AP also supports supplier payments across cards, checks and ACH. REPAY’s case rests on the fit between its payment infrastructure and particular operating systems and industries. A buyer should test that fit with a real invoice, approval and reconciliation cycle.
“Payments happen where the work already happens.”Darin Horrocks / REPAY / October 2026
- 01ApproveInside the operating system
- 02PayCard, ACH or check
- 03ExplainSend remittance details
- 04ReconcileReturn usable records
A $372 million move into the household
REPAY became public through its 2019 combination with Thunder Bridge Acquisition, a transaction with approximately $580.7 million in total consideration. Acquisitions subsequently widened its capabilities. In June 2026, it completed the purchase of KUBRA, announcing a $372 million cash price. KUBRA brought billing and customer communications for utility, government and insurance organizations.
The combination takes REPAY further into bills people receive repeatedly. At closing, management said the combined business would engage with more than 40% of U.S. and Canadian households monthly and process over $130 billion in combined annual payment volume. Those are management’s scale claims; payment volume is money handled, not REPAY’s revenue.
The financing matters. REPAY received a $500 million senior secured term loan and a $100 million undrawn revolving facility. Calling that a $600 million venture round would hide the obligation involved. Management reported approximately four times combined net leverage at closing and targeted less than three times within 18 months. Expected savings and revenue opportunities remain targets, with integration work still required.
Debt and available credit capacity are different things.
The numbers that interrupt the pitch
There is a reason to keep the calculator open. Revenue slipped from $313.0 million in 2024 to $309.3 million in 2025. REPAY attributed the decline to previously announced client losses and lower political-media spending after the 2024 election cycle, partly offset by new clients and growth within existing accounts. Embedded payments still depend on keeping customers and on what those customers transact.
The 2025 consolidated net loss was $271.1 million, including $242.7 million of noncash impairment losses, primarily related to goodwill. Those write-downs are a substantial revision to accounting value. They are not the same as cash leaving the business that year.
By the second quarter of 2026, revenue reached $100.7 million, up 33% year over year. REPAY’s reconciliation put organic revenue growth at 6%, or 4% after also excluding political-media contributions. KUBRA helped expand the headline. Consolidated net loss remained $11.5 million. The acquisition story and the underlying growth story need separate readings.
Copy the sequence, then check the fit
The useful lesson for another business is concrete. Find the steps surrounding a payment: approval, entry, delivery, remittance and reconciliation. Measure their cost before choosing a tool. Then test whether the tool returns usable information to the system your team actually maintains. Performance Automotive’s example suggests why a rebate alone is an incomplete measure of the benefit.
Economics will depend on payment mix, vendor acceptance and the integration required. REPAY advertises no module or subscription fees for one AP offering; that does not establish a universal price for its services. Request the applicable processing terms, implementation costs and rebate conditions. If suppliers will not take cards, the card-rebate calculation changes. If the software connection is weak, manual work can survive the purchase.
The human layer deserves attention, too. REPAY advertises remote and hybrid flexibility and employee development; its May 2026 Great Place to Work profile says 84% of employees rated it a great workplace. Meanwhile, August’s REPAY Voice launch applied conversational AI to phone payments. The proposition remains familiar: let people complete a necessary task with fewer obstacles. The bill still has to be paid. REPAY wants the surrounding work to shrink.