A franchise can hand an entrepreneur a manual for everything from the first sandwich to the last sweep of the floor. The financing manual is thinner. Open one location, and a bank may know what to do. Plan five openings, a remodel and an acquisition, and the question changes. Which loan should be used first? How much cash must stay free for the next buildout? What happens when a lender’s timetable and a landlord’s timetable disagree?
ApplePie Capital makes its living in that untidy space. Founded in 2014 in San Francisco, the company specializes in financing US franchises. It began as an online marketplace where investors could buy interests in individual franchise loans. Today it presents a broader proposition: one relationship through which an operator can consider ApplePie-branded loans, SBA and conventional loans from a lender network, and a financing roadmap for several units. It is a fintech company with a rather old-fashioned insight: money is only useful if it arrives in the right shape.
- ApplePie serves first-time franchisees, multi-unit operators and the brands that depend on their expansion.
- Its own branded Core and Spring loans are made by Cross River Bank; other options come through independent lenders.
- The company says it has provided $3.5 billion in loans to franchisees and works with more than 100 brand partners.
- Rates and fees depend on the borrower, brand, use of funds and loan type. There is no universal sticker price.
A repeatable business with an irregular bill
Denise Thomas, the company’s founder and CEO, noticed a mismatch. Franchises arrive with systems, operating histories and brand-level data, yet a small business borrower still has to explain a particular store to a lender. In an early interview, she argued that banks had moved away from smaller loans while many franchise operators needed financing below the scale that large banks found economical. The company’s answer was to study brands as well as borrowers: store economics, locations, operator experience and the record of the system itself.
That distinction matters. A franchise logo on an application does not pay a monthly installment. A model that understands the cost of opening a store, how long it usually takes to break even, and what existing units earn can ask better questions. ApplePie’s early marketplace put that underwriting in front of investors, who could inspect a brand, borrower and use of funds. In 2015, Thomas described a $250,000 Marco’s Pizza loan outside Salt Lake City funded by ten investors. It was a tidy example of the original thesis: one operator’s new location, financed by people who would never visit it.
The moment the menu got bigger
The first model required two matches: a borrower that qualified and an investor willing to buy the loan. ApplePie secured $28 million in debt capital commitments alongside a $6 million Series A in 2015. The following year brought a $16.5 million Series B and a separate $180 million agreement under which TowerBrook planned to purchase ApplePie-originated loans over two years. Those figures did different jobs. Equity paid for a company to grow. Loan purchase capital gave that company a route to fund customers.
The more revealing move came in 2017. ApplePie bought Funding Solutions, a franchise lending consultancy with experience in SBA, conventional and equipment finance. Randy Jones, its managing partner, joined the leadership team. The acquisition widened ApplePie’s sources of capital and its bench of people who could guide an operator through them. A business built to put one kind of loan on a screen was becoming a place to compare several kinds of loans.
“One relationship, a wealth of financial choices for your franchise business.”ApplePie Capital’s description of its financing marketplace
The shift sounds small until a franchisee must decide whether to spend cash on an equipment upgrade, refinance an existing unit or preserve borrowing capacity for two planned openings. ApplePie’s current guide calls this Guided Growth: a financial roadmap that can include multi-unit commitments, with attention to the liquidity needed to open on schedule. Its 2024 financing guide lists new units, recapitalizations, refinancings, acquisitions, equipment and remodels. Each is a different problem wearing the same “I need a loan” badge.
Map the openings
Put unit dates, buildout costs and cash reserves on one calendar.
Choose the debt
Compare branded, SBA and conventional options for the job at hand.
Keep room to grow
Check what today’s borrowing leaves available for the next unit.
The human in the online form
ApplePie has an online inquiry and document portal, but its pitch rests as heavily on relationship managers. Its site says they average more than nine years of experience helping franchisees. For the operator, the practical offer is to submit an inquiry, talk through goals and let ApplePie identify potential loan routes. For the franchisor, the offer is a financing program that can help approved operators move from development agreement to opening day. The brand is a customer of the process even when the franchisee signs the debt.
There are limits to the pie metaphor. The company does not publish a single rate because its products are not a single loan. It says pricing depends on the product, use of funds, brand history, applicant credit and existing business performance. Its disclosures also draw a clear line: ApplePie Core and Spring loans are made by Cross River Bank, while independent lenders decide the terms of loans referred through ApplePie’s network. A prospective borrower should compare the complete terms, not merely the promise of a quick form.
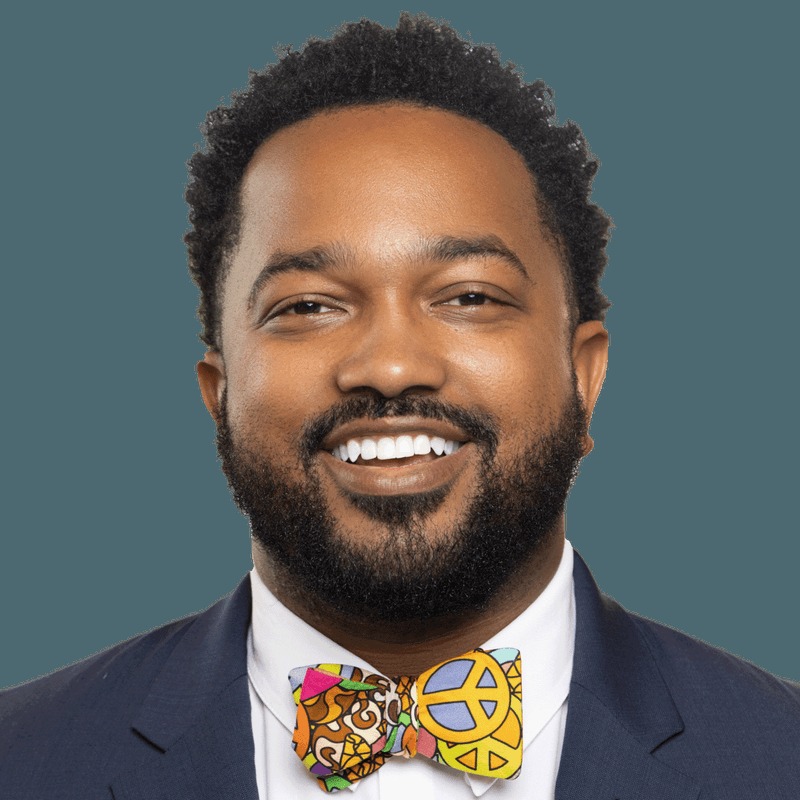
Antonio McBroom offers a useful view from the other side of the desk. The Ben & Jerry’s operator describes his earliest units as bootstrapped, supported by savings, seller financing and a banker who knew him. In ApplePie’s case study, he says working with the company helped his group pursue an acquisition of three Washington, DC-area stores. His story does not prove every borrower will get the same terms. It shows why the timing and fit of capital can alter the size of an operator’s ambition.
What the niche buys
A bank may finance a franchise. A broker may find a willing bank. ApplePie’s wager is that a specialist can do more with the facts already known about a brand: its unit economics, required investment, operating pattern and history of locations succeeding or closing. That does not erase credit risk. It may reduce the time spent teaching each lender how a franchise works. The company also acquires customers through relationships with franchise brands, giving it a channel closer to the operator’s decision to expand.
The niche has a cost. ApplePie has had to build lender relationships, underwriting expertise and enough product choice to serve operators whose needs change over time. The 2017 acquisition is the clearest evidence of that cost in action. The company did not simply add another button to a website; it bought a consultancy and brought its leaders inside. Its 2016 equity raise and loan purchase agreement likewise illustrate that a lending marketplace needs capital for both its organization and the loans flowing through it.
Start with a repeatable customer system, learn its economics deeply, then help people choose among financing tools. Copy the diagnostic questions: What is this money for? When must it arrive? What cash must remain for the next move?
The approach is most useful where businesses share enough structure for specialist knowledge to travel between customers, but differ enough that a generic loan recommendation is inadequate. It is less useful for an unproven concept without comparable unit histories, an operator whose cash flow cannot support debt, or a tiny financing need that cannot justify tailored work. ApplePie’s own terms still depend on credit, income and the lender’s decision. Expertise can make the decision clearer; it cannot make the arithmetic disappear.
There is a small joke tucked into the company’s name. A LinkedIn post says Thomas was baking an actual apple pie while early advisers searched for a name. “Easy as pie” survived the meeting. Franchise finance, of course, is not easy as pie. The durable idea is more modest and more useful: if you can see the next three stores from the first loan application, you can choose today’s loan with tomorrow in mind.