Look at the front of a store credit card and you see a retailer. Look at the agreement and another name appears. That small discrepancy explains Alliance Data Card Services, the retail-credit business now operating under Bread Financial. The store supplies the familiar face. The lender decides who gets credit, finances the purchase and collects the payments. A shopping trip becomes a relationship that can last considerably longer than the thing you bought.
- The business: branded credit cards, installment financing and consumer savings.
- The scale: about 34 million open and outstanding accounts at year-end 2025 - accounts, not individual people.
- The catch: rewards attract attention; interest, funding costs and credit losses determine the economics.
A bank with a retailer’s memory
The origin makes the arrangement less mysterious. Alliance Data emerged in 1996 from the combination of J.C. Penney’s transaction-services business and The Limited’s credit-card banking operation, acquired by Welsh, Carson, Anderson & Stowe. This was retail infrastructure becoming a company. Its working knowledge came from the point where a customer’s enthusiasm meets the question of how to pay.
That heritage still shapes its expertise: underwriting, fraud prevention, account servicing and transaction analysis. A retailer wants the next visit, not merely today’s sale. A card program gives the retailer another reason to contact the customer and another reward to offer. Bread supplies the lending machinery and uses purchase information to help partners design marketing.
First, buy a different kind of checkout
By 2020, a store card was only one answer to the financing question. Some shoppers wanted a fixed repayment schedule instead of another revolving account. Alliance Data agreed to acquire Bread, the digital installment-payments business, for an announced estimate of $450 million. Its subsequent financial statements recorded $491 million of consideration, net of acquired cash and restricted cash. Those are different measurements at different stages of the deal.
The company also became narrower. It sold marketing business Epsilon to Publicis in 2019 for $4.4 billion, subject to adjustments, and separated LoyaltyOne in November 2021. AIR MILES and BrandLoyalty went with that separation. Then, on March 23, 2022, Alliance Data took the Bread Financial name. The acquired business had become the label for the whole enterprise.
The stated reason was a simpler company centered on payments, lending and savings. The strategic inference is straightforward: serve the same shopper through several financing choices, while owning fewer unrelated businesses. Ralph Andretta called the rebrand “a turning point for the company.” The portfolio changed before the stationery.
- 2019Sell Epsilon
- 2020Buy Bread
- 2021Separate LoyaltyOne
- 2022Become Bread Financial
Three logos. One loan.
A private-label card typically works within the relevant retailer’s program. A co-branded card runs on a payment network and can travel beyond that store. Bread also markets its own general-purpose cards, including Bread Cashback and Bread Rewards, and offers Bread Pay installment and split-pay products. Merchants can integrate financing through its technology interfaces; Bread Pay served more than 1,400 small and midsize retailers and merchants at year-end 2025.
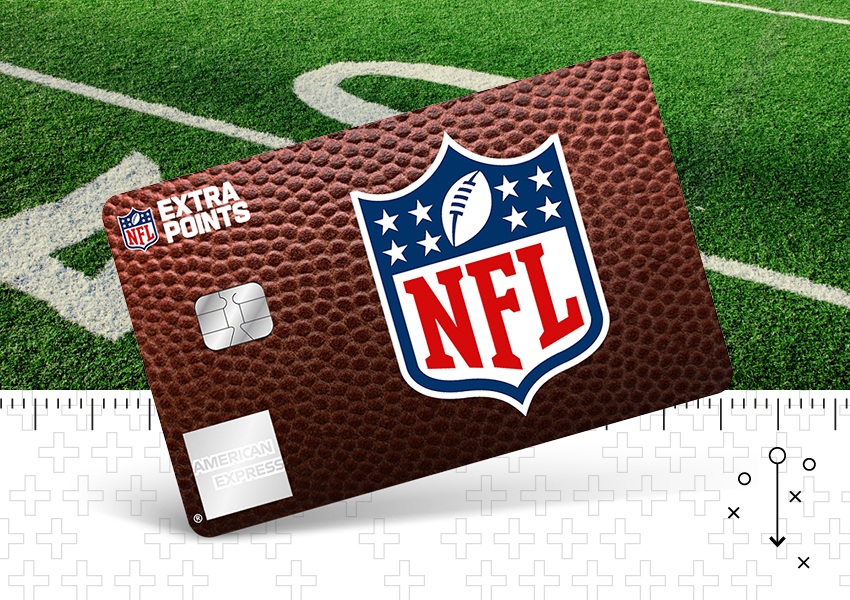
Consider the NFL Extra Points program. In August 2026, American Express and Bread announced its launch on the American Express network, with 18 teams launching cards there. The NFL supplies the affiliation. American Express supplies network benefits and acceptance infrastructure. Bread remains the issuer. Three recognizable identities share one piece of plastic, with different jobs behind each.
Sephora provides another version of the idea. Its October 2026 renewal with Bread emphasized connecting branded credit with Beauty Insider, personalization and shopping across channels. Signet’s September renewal covered technology and marketing improvements and planned credit capabilities for Blue Nile that fall. These partnerships show the pitch in practice: attach financing to an existing reason to return.
The savings account behind the shopping bag
Bread primarily earns interest and fees on loans, with additional revenue from contractual partner relationships. Bread Savings, its online deposit business, helps finance those loans. At the end of 2025, retail deposits reached $8.5 billion, up from $7.7 billion a year earlier. Deposits belong in this story because lending requires money before it produces earnings.
The market contains several overlapping contests. Synchrony competes for retail-card relationships; large card banks compete for co-brand programs and household spending; installment providers such as Affirm compete at checkout. Bread’s particular combination is brand-specific marketing, lending operations, payment choices and deposit funding. That combination carries several obligations.
For shoppers, cost depends on the product and agreement. Split-pay divides a purchase into four interest-free payments, while installment loans generally carry fixed interest rates unless a promotional offer applies. Card APRs and fees vary. A reward is a benefit only after the repayment cost is understood. A merchant, meanwhile, has to compare financing fees and program economics with the sales the offer actually adds.
The part a new name could not fix
The operational test came quickly. In late June 2022, Bread moved credit-card processing to outsourcing partners, including Fiserv for core processing and Microsoft for related cloud infrastructure. The company later disclosed unexpected platform-stability problems, with outages affecting call centers and online customer service. Customers had difficulty getting help.
The consequences included complaints, remediation costs and regulatory scrutiny. In August 2024, each of its two banks agreed to a $1 million civil money penalty related to the transition. That $2 million is a documented penalty total, not a complete bill for the disruption. The practical lesson is to protect servicing capacity while changing the infrastructure beneath it. In credit, the payment screen is part of the product.
“This is a turning point for the company.”Ralph Andretta / March 2022
A renewal is a vote. Repayment is the test.
Bread reported third-quarter 2026 net income of $156 million and a 6.40% net loss rate. The Sephora and Signet renewals show continuing partner commitment; they do not cancel credit risk. The arrangement becomes harder when customers cannot repay, funding grows expensive or a retail partner weakens. More spending alone cannot settle those questions.
There is a useful idea here for businesses well beyond banking: build a service around a relationship customers already value, then measure what happens after the first transaction. Bread’s own workplace culture has a concrete expression too: its 2026 giving campaign matched eligible associate donations without a company match cap and raised over $2.1 million for 1,013 nonprofits. For the lending business, though, the lasting verdict arrives in ordinary installments: a working account, a clear bill and a payment made on time.
Follow the relationship
Explore Bread Financial, the newsroom and investor updates. Find the company on LinkedIn, X, Instagram and Facebook.
Watch: Ralph Andretta on consumer spending and loyalty, FINTECH.TV.