Consider an imaginary $4.40 purchase. With ZYNLO Bank’s ZYNG feature, the debit transaction generates a 60-cent transfer into savings. When the customer qualifies for a full match, the bank adds another 60 cents. A small purchase has produced $1.20 in savings, half supplied by the bank. The sums are modest. The design is interesting: saving happens inside something the customer was already doing.
- Digital consumer banking backed by Massachusetts-based PeoplesBank.
- Checking, savings, money markets and CDs without monthly maintenance fees.
- Automatic round-ups with a bank match that has real eligibility conditions.
ZYNLO calls its checking account More Spending and its savings account Tomorrow Savings. The names practically stage the negotiation in your head. Today wants the purchase. Tomorrow wants a cushion. By attaching a savings transfer to a debit payment, ZYNLO lets both get something. The question is how much this convenience is worth, and what the bank learns when people use it.
01 / The bank buys half the habit
Round-ups move your own money. ZYNLO’s contribution is the match. Its September 2026 disclosures promise 100% of eligible round-ups for the first 100 calendar days. Afterward, maintaining that match requires meeting the $3,000 average-daily-balance condition in the qualifying spending account. Otherwise, the match falls to 25%, with eligibility determined using the preceding month’s balance rules.
That qualification changes the calculation. Someone carrying a small checking balance gets a different ongoing reward from someone who can leave $3,000 there. Someone who rarely uses a debit card generates little spare change to match. Buying more simply to collect round-ups would defeat the purpose. The useful version attaches savings to purchases already planned.
Savings goals add a destination: an emergency reserve, a trip, a car. Customers can personalize goals with pictures and direct ZYNG money toward them. An abstract balance becomes something recognizable. This is the copyable idea: place the action beside an existing routine, then make its destination visible.
02 / An ordinary bank, rearranged
Underneath the playful names is a conventional banking relationship. ZYNLO is a division of PeoplesBank, rather than a separately chartered institution. Eligible deposits receive FDIC protection through PeoplesBank, subject to coverage limits and aggregation rules. Opening accounts under two brands of the same bank does not create two independent insurance allowances.
The offering is deliberately familiar: interest-bearing checking, savings, money market accounts and CDs. There is a contactless Visa debit card and access to roughly 55,000 Allpoint ATMs. Mobile check deposits, bill payments, account alerts and card controls handle routine chores. Early Payday can make eligible direct deposits available up to two days early, depending on when payment information arrives.
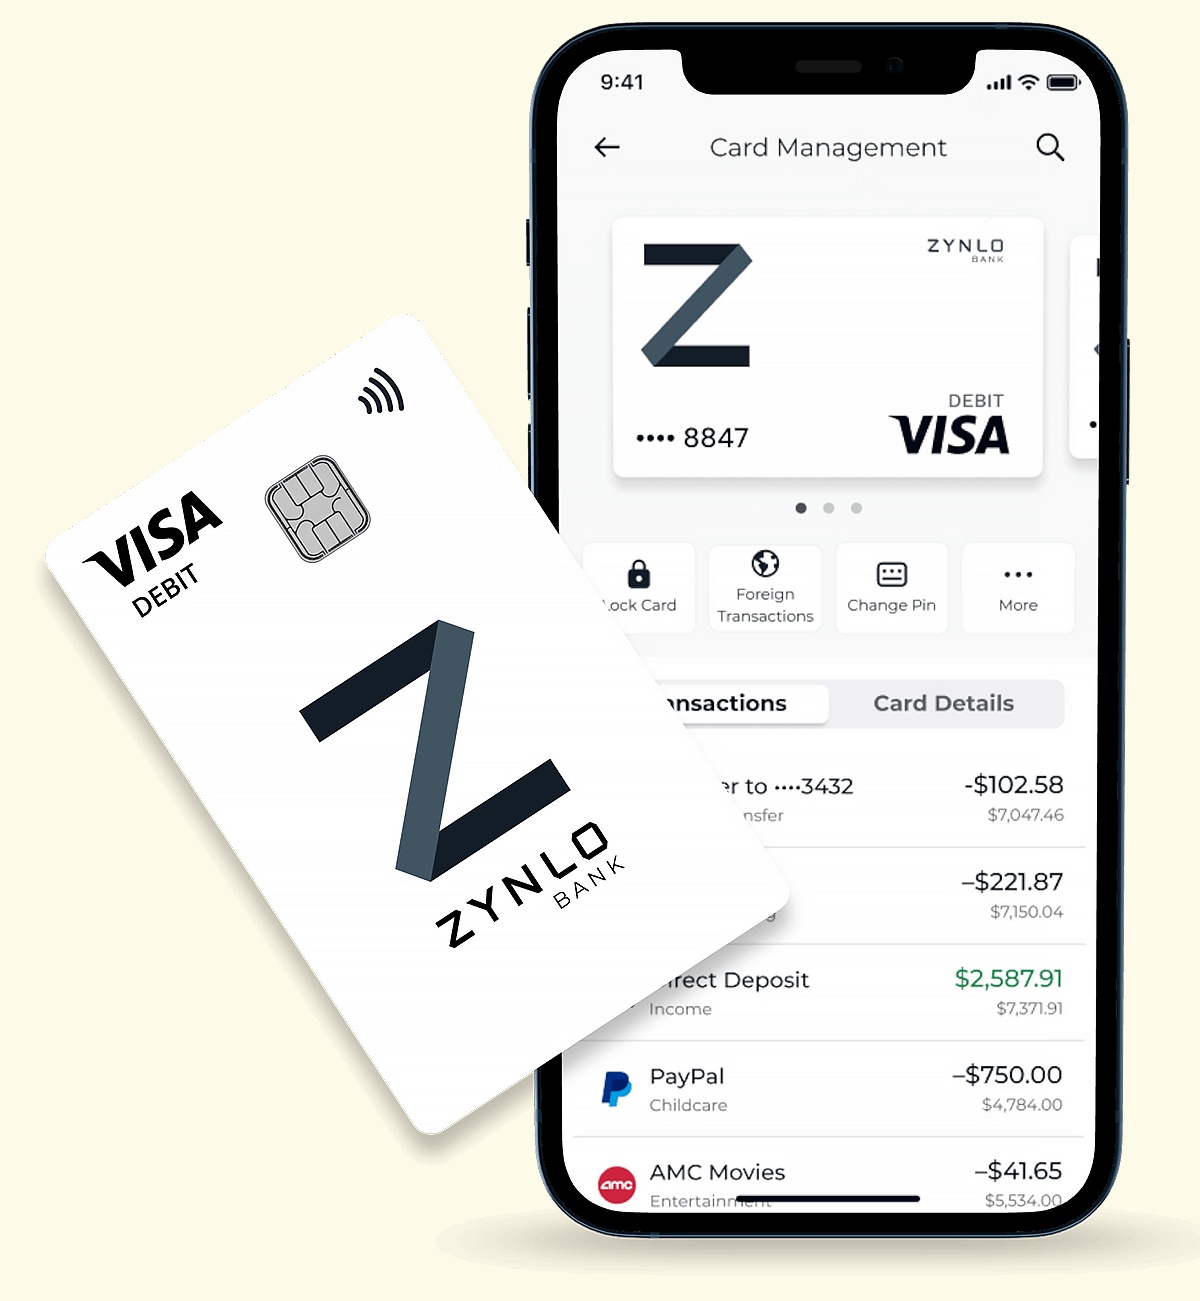
No monthly maintenance charge lowers the price of keeping an account open. It does not erase every condition: CDs can carry early withdrawal penalties. The money market account allows unlimited transactions at the account level, while external transfers have separate limits. New customers’ outgoing external transfers are limited to $5,000 monthly under the published FAQ. Access deserves as much attention as yield.
This puts ZYNLO among alternatives such as Ally, SoFi and Chime for people comfortable managing money digitally. Its particular appeal combines a savings match with deposit products and human support during published service hours. Branch-dependent customers face an obvious mismatch. Rate shoppers still need to compare current yields, which can change.
03 / Start the experiment somewhere else
The origin contains a geographical joke. A bank from Holyoke, Massachusetts, announced ZYNLO’s launch in Madison, Wisconsin, in May 2020. The release said availability initially covered that market and one other. A new digital identity let PeoplesBank look beyond its regional footprint without asking the existing brand to mean everything to everyone.
Nymbus supplied technology and operational support. ZYNLO initially ran on a separate banking platform alongside PeoplesBank’s existing system, an arrangement often called a sidecar core. In a February 2024 FinXTech report, executive Aleda DeMaria said the approach cost less than opening a branch, took about a month to construct and reached break-even in two years.
That comparison explains the business. ZYNLO gathers consumer deposits nationally for a bank that already exists. Active accounts and durable funding matter more than app downloads. Outsourced operations helped make the experiment practical, but the reported break-even timing belongs to this institution and arrangement; it is no universal timetable for launching a bank.
04 / The account was open. Then what?
Getting someone through the digital door did not finish the job. Digital Onboarding’s customer study describes unfunded accounts, low balances and first-year closures while ZYNLO relied on bulk email. The bank selected the adoption platform in September 2023. A customer could like the offer enough to sign up, then leave their actual financial life elsewhere.
“Banks can acquire accounts online all they want, but that does not mean those customers will deposit their paychecks and transact.”
Brittny Williams / Digital Growth & Partnerships / 2023
The response included personalized guidance, email and text reminders, direct-deposit tools and incentives. The vendor’s case study reports 49 automated campaigns, a 115% increase in average balances and 64% lower attrition over the first twelve months. These are vendor-reported results. They suggest useful improvements, without isolating which intervention caused them.
05 / The experiment comes home
ZYNLO also changed the parent’s appetite for technology. In their October 2025 account of PeoplesBank’s core conversion, bank executives described how the digital division demonstrated faster product launches and better operational possibilities. Seeing the system work gave them confidence to extend the approach across the institution. PeoplesBank’s broader Nymbus conversion went live in June 2025.
For customers, the result remains pleasantly concrete: a place to hold deposits, organize goals and make saving automatic. For other businesses, the lesson is equally usable. Try a new approach in a bounded setting, watch what people actually do, and earn the next commitment. At ZYNLO, even the larger institutional change began with a smaller move.