Consider a borrower with good credit, money for a down payment and an income that arrives in inconvenient shapes. Some comes from commissions. Some comes from a business. Last year’s earnings describe a life that has already changed. A mortgage application wants the story to fit into boxes. The borrower would like to explain the boxes.
Quontic has made that conversation part of its business. The New York digital bank sells familiar things: checking accounts, savings accounts, certificates of deposit and home loans. Its distinctive proposition concerns people who can be creditworthy without producing the financial biography a conventional lender expects.
- Gather deposits online from customers across the country.
- Offer mortgages with alternative ways to document income.
- Keep the evidence trustworthy as the business scales.
A small bank, an awkward discovery
In 2009, Steven Schnall bought Golden First Bank, a troubled institution in Great Neck with $24 million in assets. He and George Lazaridis rebranded it Quontic. The business acquired a community-development identity, receiving CDFI certification in 2015. Its eventual national reach grew out of a fairly local question: who was being overlooked?
The answer included self-employed workers, immigrants and families whose circumstances were poorly served by standard mortgage channels. These customers did not all share an income bracket. They shared a difficulty making their finances legible to somebody else’s process. Today, Lazaridis is CEO and chief lending officer; Schnall died in August 2022.
That distinction matters. Quontic’s specialty mortgage business includes borrowers with substantial savings. Its mission reaches underserved communities, but an underserved borrower can also be someone with assets and irregular earnings. Financial exclusion has more than one doorway.
The plumbing came before the ring
The digital transformation had a practical trigger. According to Schnall’s account in 2020 reporting, the OCC pressed Quontic in 2018 to reduce its dependence on wholesale funding and attract more core deposits. Meanwhile, banking and mortgage systems did not communicate well. Producing reports swallowed staff time.
Quontic kept its core system and worked with HubOne on middleware running on Microsoft Azure. Quontic.Works launched in June 2019. By the 2020 account, technology efforts since Patrick Sells joined had cost $3 million. Schnall described the organizational work plainly: “We’re moving a mountain culturally.”
“We’re moving a mountain culturally.”
Steven Schnall · 2020
A second piece arrived in April 2020: MANTL’s online account opening. A historical vendor case study reported 97% automatic decisioning. Treat that as a snapshot from the rollout, not a current service guarantee. The operational idea is durable: national deposit gathering needs an application process the bank can actually handle.
The company describes monthly open meetings and weekly Coffee with Colleagues sessions with leadership. Those are modest practices, but they address a problem that buying software cannot settle: getting employees to understand the same business. Its culture page also describes recognition tied to core values. A digital bank still has to organize human beings, including the people deciding how to interpret an unusual application.
Different evidence. Real requirements.
Quontic’s Lite Documentation mortgage is the clearest expression of its lending approach. Its published materials describe a recent, accountant-prepared profit-and-loss statement for eligible self-employed borrowers, or a short employment verification for salaried applicants. Tax returns and W-2s need not be the deciding documents. Current circumstances get a larger hearing.
The trade-off is visible in its published primary-residence example: a minimum 660 credit score and 20% down for loans up to $1.5 million. Bigger loans have tougher conditions. This is a route for someone with a documentation problem and financial resources. A buyer without the required equity still has a problem.
Different evidence, subject to credit and property approval.
Other products address different mismatches. Asset Utilization considers eligible liquid assets. ITIN loans offer a route for qualifying applicants without a Social Security number. DSCR financing looks at investment-property cash flow. Conventional, FHA and VA options sit alongside these programs. The expertise lies in matching a borrower to an appropriate qualification method.
Deposits on one side, judgment on the other
For depositors, the experience is more ordinary. Quontic offers high-yield savings, money market accounts, CDs and checking with interest or cash rewards. Published opening minimums are $100 for checking and savings products and $500 for CDs. Online banking supplies remote check deposit, bill pay and account management.
The checking rewards need attention to conditions. High Interest Checking requires ten qualifying debit purchases of at least $10 each per statement cycle to earn its advertised rate. Missing that activity changes the return. The useful comparison is what an account pays under your habits.
The business connects savers and borrowers through familiar bank economics: interest earned on assets, funding costs, and mortgage-related income. In March 2020, its parent raised $8 million in preferred stock with an initial 5.99% coupon. Another $8 million in subordinated notes followed in September, initially paying 5.75%. Those announcements supported lending capacity and digital investment.
Public support has also played a role. In 2021, Quontic announced a $1.825 million Treasury Rapid Response award for communities affected by COVID-19. That money was a grant supporting its community mission, distinct from the capital investors supplied through stock and debt.
For deposits, Quontic competes in the crowded online-bank market. For mortgages, its alternatives include specialist non-QM lenders and brokers. The combination gives it a particular position: a bank charter and a community-development mission, paired with nationwide digital distribution.
The ring gets a closing date
Then there is the jewelry. Quontic launched its payment ring in 2022, letting customers make contactless purchases with a knocking gesture. It needed no charging. A bank product had become something a cashier might ask about.
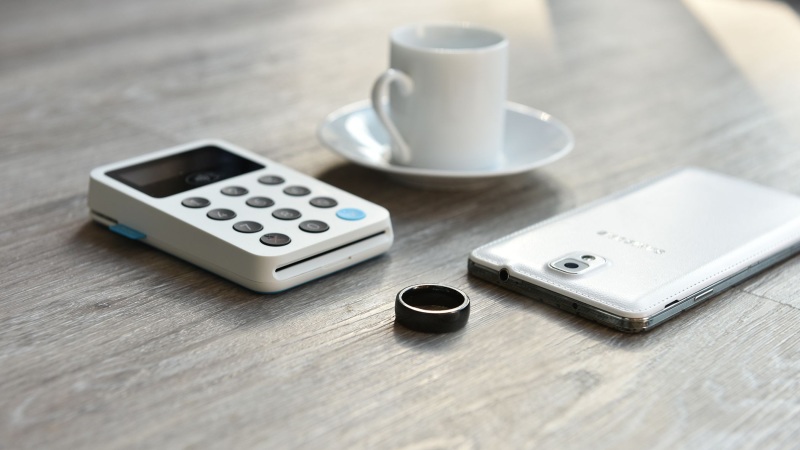
By October 2026, the story had changed. New ring orders and Wearable Checking applications stopped on September 16. Existing rings expire December 31. Quontic says an enhanced wearable experience is in development, with no announced launch date. Existing accounts remain supported. Novelty needs maintenance, a replacement path and a reason to persist.
The evidence has to survive inspection
There is a harder test of Quontic’s model. In June 2026, the OCC announced a prohibition against former mortgage officer Steven Ho, citing concealed broker relationships, falsified loan information and unauthorized transfers of confidential information. Ho consented without admitting or denying wrongdoing. The order concerns the individual; its findings make the verification challenge concrete.
The lesson another business can borrow is precise: identify customers a standard process misreads, then decide what evidence would describe them better. Build the controls to test that evidence. Quontic’s promise depends on getting both judgments right: seeing an overlooked borrower, and knowing when the story does not hold up.