Before a bank can approve your application, a surprising number of things must happen politely. A credit report must arrive. An identity check must return. Someone’s policy must decide what to do with the answers. Zoot Enterprises works in that crowded interval between a question and a decision. The application may look simple. Behind it, simplicity has to be manufactured.
- Zoot supplies the software behind credit and customer decisions.
- Its customers include financial institutions and automotive lenders; Daimler Truck Financial Services is a named example.
- WebRules lets teams build, test and run their own rules and workflows.
- The practical advantage is changing a process without rebuilding everything around it.
01 The school run behind the software
In 1988, Chris Nelson moved to Bozeman for a bank-services job. He was a single father, and the arrangement was supposed to accommodate taking his eight-year-old son to school. Then his managers objected to his hours and his jeans. The job had acquired an inconvenient dress code for both trousers and parenthood.
Moonlighting for a credit union, Nelson wrote software that brought credit reports onto a PC. He added algorithms applying each lender’s requirements, then founded Zoot in his basement in 1990. Even the name was personal: an alias he had used for college computer pranks. The software business grew from a specific irritation, with a useful technical answer attached.
“I don’t care when people work or what they wear, as long as they do great work.”
Chris Nelson · describing his approach in 2015
02 The decision is only as good as its plumbing
Zoot sells to organizations that need to turn information into an action: approve an application, present an offer, investigate a merchant, or route a case to an employee. Banks, retailers, payment providers and automotive lenders appear across its public materials. The lender supplies the credit strategy. Zoot supplies machinery that can apply it.
A concrete example arrived in July 2022, when Daimler Truck Financial Services USA announced its Zoot relationship. The commercial-vehicle financier needed decisioning technology to support specialized financing and dynamic leasing. Buying a truck and applying for a store card are rather different occasions. Both require an institution to gather information and apply its own rules.
Zoot’s Data Gateway connects external providers and internal systems. Its current homepage advertises more than 400 available connections and over 90 partners and providers. Those numbers describe a catalogue, rather than the number of customers or sources used in every application. The point is to make a new source of information easier to bring into an existing process.
- 01 / GatherApplication + internal records
- 02 / ConnectCredit, identity & other data
- 03 / EvaluateThe institution’s rules
- 04 / ActApprove, decline or review
There is an especially telling detail in Zoot’s prescreen materials. An unnamed U.S. bank wanted information from all three credit bureaus without delaying its decision, while keeping parts of its credit policy confidential from a partner. Zoot describes acquiring the bureau data simultaneously and feeding it into the workflow. Speed was only half the assignment; boundaries around information mattered too.
03 Two tools, one changing policy
WebRules Builder is the workshop. Teams use it to develop and test decision logic, screens, integrations and workflows. WebRules Live is the production environment that executes those decisions. Separating the two gives a policy change somewhere to be examined before it meets an actual applicant.
Builder uses a low-code environment and reusable components. Zoot can manage the work, share development with the customer, or support a customer’s own team. That range matters because institutions have different appetites for running their software. A rules engine is useful only if someone can operate it after the consultants leave.
James Taylor’s 2021 product review described flowcharts, decision tables, test data and tools that show which branch a transaction took and which rules fired. He also noted that customers owned their data, with exports back into their systems. His review places Zoot in an interesting position: managed infrastructure with considerable customer control over the process and its information.
Test.
Then run.
WebRules Builder develops the logic.
WebRules Live executes it.
A product distinction with operational consequences.
Live’s public page describes five data centers, 99.9% uptime and decisions in as little as four milliseconds. That last figure describes advertised processing capability, not a promise that every complete application finishes in four milliseconds. An applicant’s journey includes the other systems and data providers the workflow calls.
04 Modernize the layer that hurts
An anonymous Zoot case study describes a large U.S. bank whose aging core system was approaching obsolescence. Zoot’s approach was to layer new technology over the existing core: improve infrastructure and data handling, automate operations, then rework interfaces and analytics. The old system’s limitations supplied the reason to change. The project focused on the surrounding work that could be improved.
The cost claims deserve careful reading. The case study gives a nine-month average payback and $19.9 million in average operating profit over three years across Zoot’s portfolio. These are vendor-reported averages, not the featured bank’s disclosed invoice or independently measured result. They support a sales argument; they do not calculate another institution’s return.
Today’s credit-card origination offering makes the scope choices explicit. Base includes application screens, underwriting features and configurable policy attributes. Professional adds more customization and integrations. Elite offers tailored development and broader deployment. Zoot advertises two-to-six-week implementation for Base, with qualifications around complexity and documentation. Larger builds depend on their requirements.
The business model combines hosted software with implementation expertise, training and ongoing support. Data access has another commercial relationship attached: clients contract with the data providers. A buyer therefore has to price the whole operating arrangement, including integration work and the information its rules will request.
05 Cash flow joins the conversation
Zoot’s newer partnerships show how this machinery can acquire different inputs. In May 2023, Prism Data brought consumer cash-flow analysis into its integration hub through CashScore and Insights. Those products use permissioned banking transactions to help evaluate creditworthiness, including people with limited traditional credit histories.
In April 2026, Zoot announced SlopeScore integration for small-business underwriting. The idea is to add transaction-derived signals to an institution’s existing framework. The impressive pilot figures in that announcement belong to Slope’s bank pilot; they are not Zoot customer results. The integration’s significance is the additional kind of evidence a lender can use.
The same month, Zoot announced Income Confirm by Equifax for credit-card origination. Equifax’s product combines verified employment and income information from The Work Number with its consumer credit report, where available. July brought Baselayer’s business verification and fraud intelligence. Each addition addresses a different question: financial capacity, business legitimacy, or the meaning of cash moving through an account.
These partnerships also explain Zoot’s place in the market. It organizes signals and actions around a customer’s strategy. Enterprise Cross-Sell applies that approach to personalized offers across business lines; merchant vetting applies it to onboarding and monitoring. The engine’s usefulness extends beyond the initial loan application.
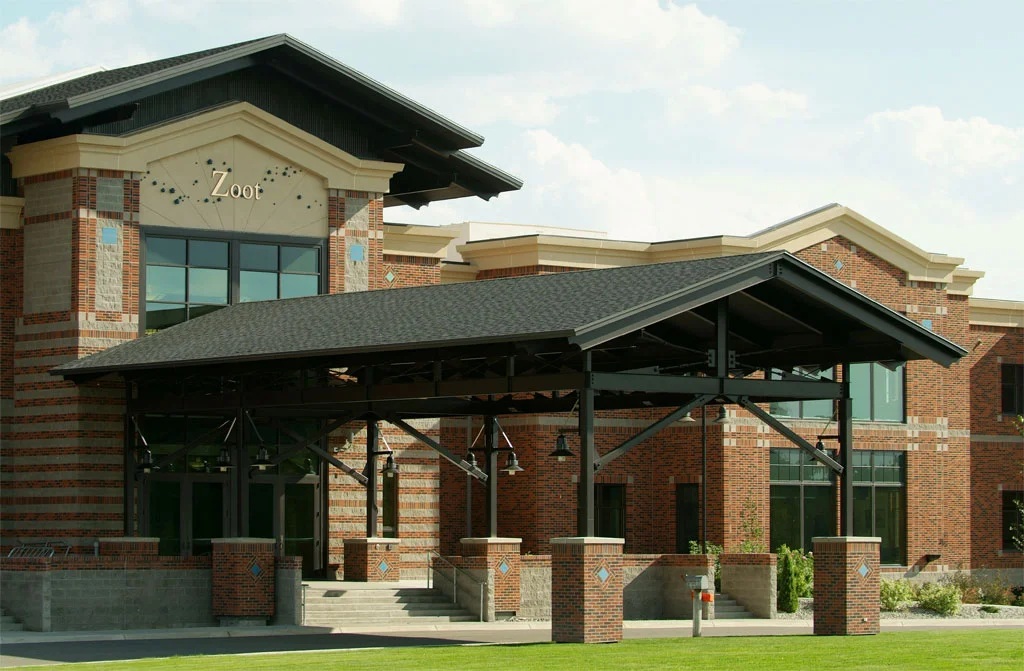
06 A campus built for people who stay
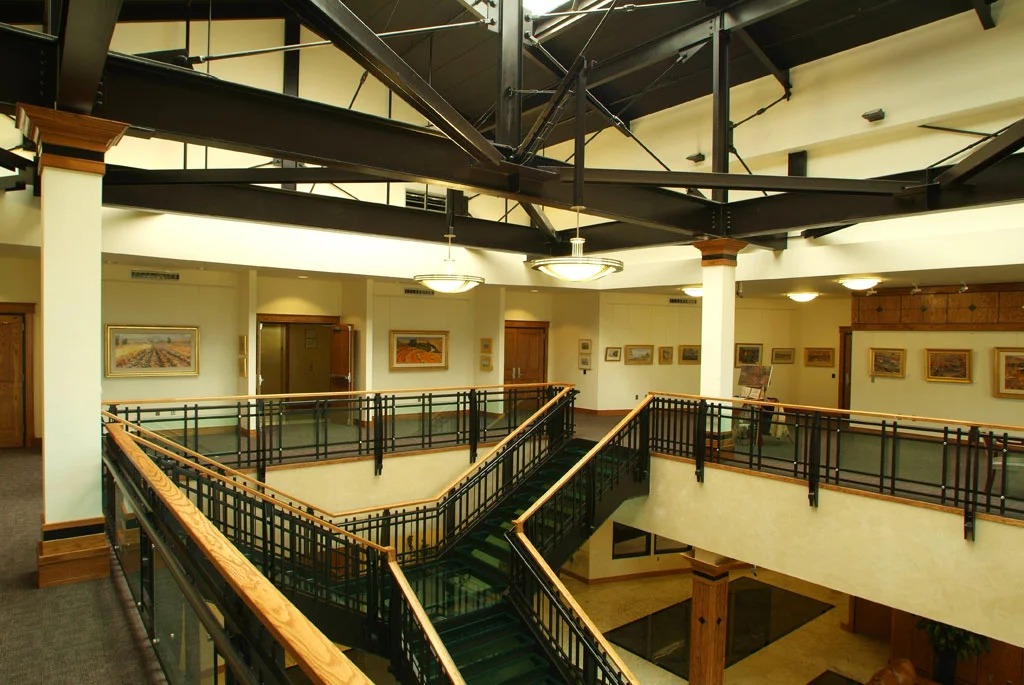
Flexibility has a less technical expression at Zoot’s campus. Its careers page lists on-site childcare for children from six weeks to six years old, a fitness center, tuition reimbursement, a cafeteria and an espresso bar. The office welcomes dogs. There is a private disc golf course. Employee life has more texture here than a photograph of a beanbag can usually convey.
The company also maintains an art gallery with rotating exhibitions. Its October-to-December 2026 show features work by children from the Zoot Adventure Learning Academy. The company that began partly because a parent needed a workable morning now has children’s art on its exhibition walls. It is a pleasingly concrete connection.
07 The useful lesson is a changeable system
Zoot operates in a competitive field. Provenir also offers low-code decisioning and a data marketplace. Internal development remains an alternative for institutions with the staff and infrastructure to maintain it. Zoot’s case rests on the combination of reusable tools, hosted operations, extensive connectivity and hands-on services. None of those features alone settles a purchasing decision.
Several practical lessons travel beyond credit software. Separate policy design from production execution. Reuse working integrations. Identify a painful layer before attempting a wholesale overhaul. Zoot’s gateway documentation recommends primary and secondary data partners so a workflow can fall back when a provider has an outage. Redundancy needs a contract as well as a diagram.
There are conditions attached. Poor inputs still require correction. Someone must own the credit policy and approve changes. An institution that requires self-hosting should examine deployment terms carefully: Taylor’s 2021 review described a platform running on Zoot’s infrastructure. Custom integrations and incomplete documentation can stretch a deployment beyond the advertised schedule. Those are matters to resolve in the buying process.
The interesting product here is an institution’s ability to revise what happens next. New information arrives. A policy changes. A customer belongs in a different workflow. Zoot has built a business around making those adjustments manageable. For the person waiting on an application, that work is invisible. The answer is what appears on screen.
Visit the company website, explore WebRules Builder and credit-card origination, or browse the newsroom and resource library.
Follow LinkedIn, X and Facebook. For a different view of the campus, explore the art gallery.