Ninety seconds is an odd place to begin a story about financial technology. It is barely enough time to make tea. Yet for Jeitto, a Brazilian digital credit business, roughly a minute and a half was the time a credit application spent being assessed. After it adopted Provenir, that interval fell to 30 seconds. The more revealing detail was elsewhere: changing a decision flow no longer required the technology team to get involved.
- Provenir sells the software connecting risk data, models and business rules.
- Its buyers include banks, fintech lenders, retailers and telecom operators.
- Its pitch gives risk teams more control over changing decision strategies.
- Customer results are useful clues, with scope and measurement that matter.
In Provenir’s Jeitto case report, the lender recorded a 10% increase in approval rate and a 20% reduction in defaults on loan contracts signed after adoption. Those are customer-reported outcomes, rather than a controlled experiment. Still, they suggest a worthwhile question. What if a lender’s constraint is partly the machinery between knowing what to do and actually doing it?
01 / The engineer’s queue is part of the risk
A credit score is an assessment. A decision is an action. Between them sit rules about eligibility, affordability, identity, pricing and exceptions. Somebody must fetch the data, run the model, apply the policy and send an answer to the right system. An application may be approved, declined or referred to a human. Each route needs its own instructions.
Provenir operates in that middle territory. Its loan origination materials describe importing models from tools such as SAS, R and Excel, aggregating data, applying rules and routing exceptions to underwriters. The unglamorous verb is “operationalize.” It means that a model must do something useful outside the meeting where everyone admired it.
The company’s current platform adds low-code workflow configuration, version control, auditability and connections to existing systems. Risk teams can change strategy directly. The appeal is easy to understand: the people accountable for a credit policy also get tools to alter how that policy runs. Engineering remains essential to the surrounding infrastructure, but every routine rule adjustment need not become another development project.
- 01ConnectInternal records + external signals
- 02EvaluateModels + rules + risk policy
- 03ActApprove, decline or refer
Illustrative workflow, based on Provenir’s published capabilities.
Provenir’s platform description makes integration central to the proposition. REST APIs support real-time decisions; batch processing and webhooks support other workflows. Core banking, CRM, bureau and fraud systems can remain connected around it. That approach suits an institution with useful existing investments and a growing collection of awkward handoffs.
02 / A marketplace for the missing pieces
A workflow is only as useful as the information reaching it. A lender might want bureau history for one applicant, income information for another and identity checks for both. Adding a provider can create a second problem: maintaining its connection. Then comes a third provider, a new geography and an entirely respectable reason for another integration.
Provenir introduced its Data Cloud and Marketplace in 2021 with 25 partners. Current materials advertise more than 120. The idea is a managed route to credit, identity, fraud and alternative data through a single API. Buyers choose the sources appropriate to their strategies; the marketplace reduces the number of separate connections they must assemble and maintain.
Its position in the market is pleasantly untidy. Provenir’s integration tools connect to providers including FICO, Experian, TransUnion and LexisNexis. FICO and Experian also offer decisioning alternatives. A firm can therefore compete with another firm’s workflow software while consuming its information. In credit technology, a rival may be sitting quite comfortably in the supply chain.
This is enterprise SaaS, bought through a sales conversation and accompanied by services. Provenir’s 2024 AI announcement describes purpose-built risk models, explainability and live retraining, with a SaaS delivery model. The bill’s usefulness depends on the work it replaces: building integrations, deploying models and maintaining decision logic. Buyers need to examine that workload alongside software and data charges.
03 / Fewer handoffs, a narrower first step
The first thing to strain at Fiba Faktoring was a manual process. The Turkish finance company wanted to serve SMEs needing working capital, but credit decisions and receivables selection were taking too long. Its Provenir case report describes 65% automation within particular SME ticket-size ranges, fivefold faster processing during decision stages and a 40% reduction in credit decision workload.
Fiba Faktoring’s reported results. Automation covers specified SME ticket ranges; these figures describe different measures.
The boundaries make the example more useful. There was a defined population of decisions to automate, with existing workflows to accommodate. Reading it as an instruction to automate every credit judgment would throw away the most practical part. A bounded process gives a team something it can configure, test and measure before extending it elsewhere.
Implementation costs also deserve a careful reading. Provenir’s current platform page says SoFi went live in ten weeks at 57% lower cost than anticipated. That is a specific reported project comparison, not a promise about another bank’s budget. The sensible buying exercise is to define the proposed project, its baseline staffing and integrations, and the outcome that would justify the expense.
04 / One applicant, several kinds of trouble
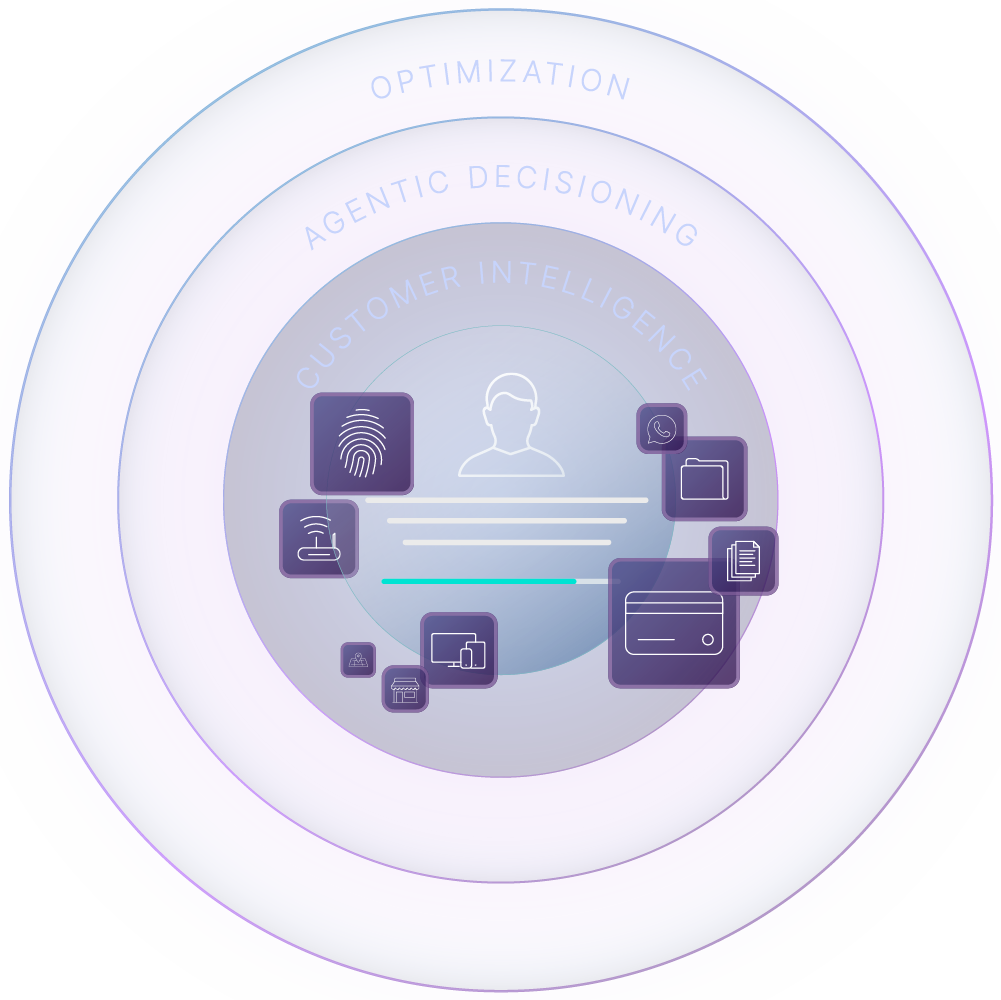
Credit risk asks whether a customer can repay. Fraud checks ask whether the application and identity should be trusted. Collections asks what happens when payment does not arrive. Provenir wants these activities to share an environment, with case management for decisions requiring investigation. That is a broader proposition than selling one score or one rules engine.
The company’s fraud materials show why connections matter. An application can appear ordinary on its own, yet become suspicious when linked to other devices, addresses, identities or prior applications. Graph analytics examines those relationships. Simulation tests strategy changes before deployment. Investigators still need the signals and reasoning behind a referral; the useful automation makes their judgment better informed.
In April 2025, Atom Bank selected Provenir to streamline data and risk decisions across residential mortgages, secured business lending, savings and buy-to-let mortgages. The announcement described reducing the complexity of managing several platforms. It was a selection announcement, not a completed results study.
Then, in June 2026, Norlys announced a partnership covering energy and telecom. Following its acquisition of Telia Denmark, the Danish group needed to bring together systems and customer journeys. Initial work would focus on onboarding and underwriting, with a wider lifecycle roadmap. Provenir’s market reaches beyond banks because credit decisions do too.
“Provenir’s primary differentiator is its flexibility.”Philip Mackenzie, Research Principal, Chartis - quoted in Provenir’s September 2026 announcement
05 / The useful question to steal
Provenir’s AI offering includes machine learning, profiling, graph analytics, scenario simulation and custom models supported by its data science team. The feature list is substantial. For a buyer, a more revealing demonstration would follow one policy change all the way from proposal to production: who edits it, who approves it, how it is tested and what happens if results deteriorate?
That question also exposes the conditions required for the software to earn its place. Data must be suitable for the decision. Outcomes must return to the people monitoring performance. The institution needs clear authority for changing risk policy and a way to investigate exceptions. Faster execution can faithfully reproduce a bad rule. Configurability gives a team more responsibility along with more control.
The lesson readers can borrow is modest and concrete. Pick a recurring decision. Count the handoffs. Measure the time to answer the customer and, separately, the time to change the policy. Provenir’s customer stories become interesting at the point those two clocks meet. A bank may already know how to answer quickly. Its next advantage could be learning how to change the answer carefully.
Provenir website ↗ · Articles and webinars ↗ · Company news ↗