Wade Arnold wanted to buy Carl some golf balls. They had met while Arnold was traveling for an event, traded texts for a couple of days, and progressed from arrangements to conversations about family and golf. Before heading home, Arnold sent him $15 in the same text thread. Carl accepted the payment. No exchange of app handles. No small diplomatic conference about whose payment service deserved the business.
Arnold told that story when Moov Money launched in September 2026. For the co-founder and CEO of Moov, the modest gift made a useful demonstration: a payment could follow a conversation people were already having. Years of infrastructure work had arrived at the rather civilized ambition of getting out of the way.
That ambition runs through his career. He has built digital banking software, worked inside the companies that supply it, and spent years confronting the machinery behind a simple transfer. Along the way, he has acquired a particular impatience with making developers solve the same problem twice. His answer has included a company, public code, a developer community, and a conference where the sales pitch is asked to wait outside.
A dorm room with paying customers
The early setting was Shull Hall at the University of Northern Iowa. As a student, Arnold worked in hosting support at Powersurge. When the business was sold, he started Eccentric Hosting from his dorm room. Linux hosting was still unusual enough to be a proposition in its own right. He later recalled serving about 2,000 clients. A university room had become a place from which strangers expected their websites to keep working.
By 2005, another opportunity had put him closer to banking. A merger created an opening to take over work serving roughly 30 bank clients, under the T8 Webware name. His technical work also brought consulting projects for businesses including Deere, McDonald’s, and Accenture. Banking, however, became the continuing assignment. The institutions needed help managing what their customers encountered online, a shopfront whose doors were increasingly made of software.
Cedar Falls offered reasons to stay: access to university talent, professors with whom he could discuss ideas, and an everyday life he found manageable. In 2011, he was describing a business with about 240 clients across the country, largely regional and community financial institutions. His address did not need to resemble his market. That was already a practical lesson in building beyond the immediate neighborhood.
Banking, one layer further down
Arnold founded Banno in 2008, building a digital banking platform for community banks and credit unions. Bob Smith, later his Moov co-founder, was Banno’s founding chairman. Jack Henry acquired Banno in 2014, and Arnold became a managing director there. The sequence gave him experience both creating software for financial institutions and working inside an established provider.
Founds Banno
Jack Henry acquires Banno
Begins Moov’s open source ACH project
Introduces Moov Money
After leaving Jack Henry in 2016, he worked with BillGO, serving in technical leadership roles including interim CTO and executive vice president of technology. The view kept moving downward through the stack: from the experience a customer sees toward the systems that make the experience possible. A pleasant screen could still depend on a long chain of difficult integrations. Someone had to understand what happened behind the button.
Remembering that work in 2023, Arnold put the number of banking cores he had connected to at around 42. He qualified the recollection himself. The exact tally matters less than the accumulated repetition: different projects, familiar obstacles, more engineering time spent reaching existing systems. Moov grew from his question of whether those foundations could be made easier for everyone who came next.
He put the difficult bit on GitHub
In 2017, Arnold began an open source project for ACH, the network behind many ordinary electronic payments in the United States. Written in Go, the library helped developers generate files in the format the network requires. It could work within a Go application or through an HTTP API. This was useful plumbing, the sort whose successful operation rarely earns applause.
The project addressed work many companies needed without making each company distinctive. Sharing it gave developers a starting point and a place to improve it together. A Slack community followed, offering answers, bug fixes, and connections to people facing similar implementation problems. By August 2020, that group had grown beyond 500 members. Other libraries covered additional financial protocols.
“software engineer by craft and an entrepreneur by accident”
Wade Arnold, 2023
Arnold’s description of himself fits this beginning. Moov started on his own GitHub account. In a 2023 thank-you letter, he described continuing to answer technical questions and ask for test cases on pull requests even while running the company. The executive title had evidently failed to cure his interest in the implementation.
Open code also gave the venture a demanding audience. Developers could inspect what had been built, raise questions, and contribute improvements. A company selling confidence in payments would have to accept scrutiny of the details. Arnold’s recurring interest in documentation belongs here, too: a useful piece of software must be understandable to someone who was absent when its author had the idea.
Capital arrived. The craft stayed on the agenda.
Moov announced a $5.5 million seed round in 2020, then a $27 million Series A that December. In January 2023, a $45 million Series B followed, led by Commerce Ventures with participation from Andreessen Horowitz, Bain Capital Ventures, Visa, and Sorenson Ventures. The commercial ambition had grown from shared libraries into a payments platform connecting to the networks businesses use to move money.
Round sizes in US dollars. Company financing, not personal wealth.
Yet Arnold’s account of engineering remains stubbornly interested in ordinary work. In 2022, he distinguished candidates fascinated by the chosen technology from those who first wanted to understand the customer’s problem. He favored curiosity about the problem. A new tool could be enjoyable; it still had to justify its place in the solution.
His definition of completion was equally inconvenient for anyone hoping to merge code and disappear. Documentation had to be published. Customer support needed preparation. Sales needed to understand the positioning. The website and communications had to be ready. Engineering, in this view, continued until colleagues and customers could use what had been made. Elegance had administrative consequences.
The boss gets out of the way
Arnold has been explicit about the workplace he wants to create. In 2021, he said he would judge his success by employees’ experience: whether they felt respected, challenged, accepted, and able to do work they valued. Fundraising and payment volume remained necessary business concerns. He wanted the people doing the work to count in the assessment of whether the business was succeeding.
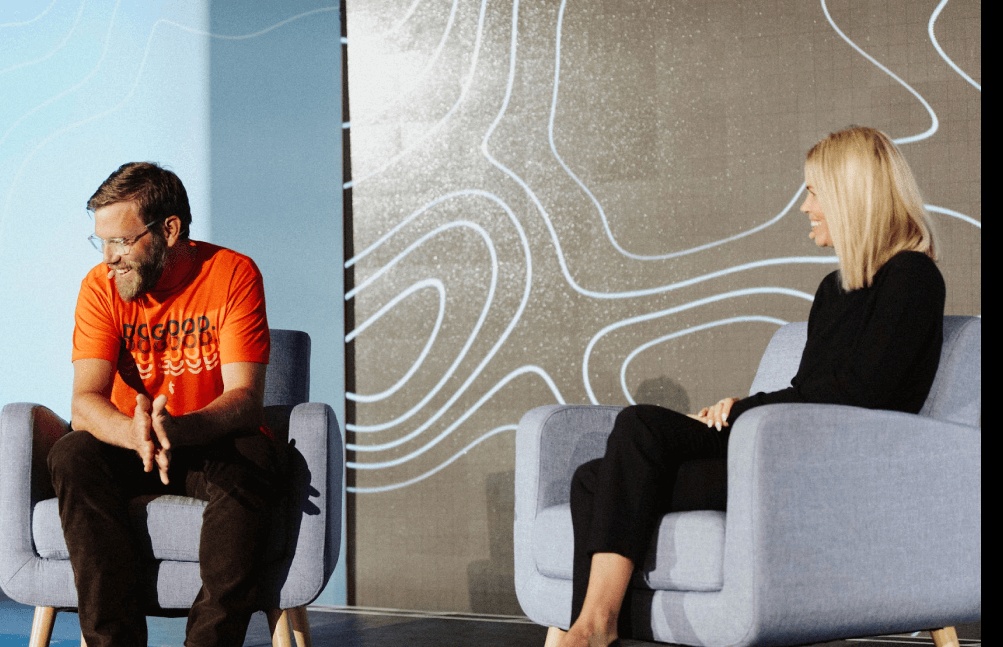
He summarized his approach as being demanding about issues while treating people with care. Trust, he argued, affects how quickly a team can decide and deliver. Hire people for their judgment, give them room to use it, and spend less time arranging permission. His preferred environment allowed disagreement before a decision, followed by a shared commitment to execute it.
These are his stated standards, rather than a guarantee about every working day. They do explain the connection between the public libraries and his management philosophy. Both depend on allowing other people to contribute something he could not produce alone. For a founder who still likes examining code, accepting that he need not be the programmer with every answer is a consequential professional adjustment.
A conference without the costume
Arnold wanted a fintech developer conference where he could relax, learn, and avoid dressing for a public relations performance. The first fintech_devcon took place in 2021 and brought together 500 people. By the following year, its program had attracted 121 talk submissions. Workshops put hands on keyboards; speakers discussed obstacles they had actually encountered.
The format extended his original wager on shared knowledge. A developer confronting payments infrastructure could learn from another developer who had already wrestled with it. Teaching made experience useful beyond the company that paid for it. In an industry fond of the word proprietary, that was a fairly sociable choice.
There was room for humor alongside the mission. Announcing the 2022 speakers, Arnold asked people to stop messaging him for discount codes because the team had taken them away from him. The founder had helped create the gathering and apparently still needed supervision at the ticket office. It is a more revealing detail than another polished declaration about community.
Back to the $15
By September 2026, Moov Money had brought his infrastructure interests into a person-to-person payment product built with Visa and Mastercard. It uses eligible debit cards as payment destinations and is offered through participating financial institutions. The ambition is to let those institutions provide a convenient payment experience within their own customer relationships. Availability and timing depend on the institution and payment method.
Arnold’s story about Carl keeps that ambition at human scale. Two people had a conversation. One wanted to send a small gift. Years after a dorm room became a hosting business, and a public code repository became the beginning of Moov, he was still testing whether software could make an everyday exchange less troublesome. Fifteen dollars for golf balls is a modest transaction. It is also a perfectly reasonable standard to ask an elaborate financial system to meet.