Consider the last few seconds of buying something in a small shop. The customer taps a card. The terminal chirps. Everyone moves on. Yet the number on the receipt and the money that reaches the shopkeeper are different numbers. For VizyPay, the payment company based in Iowa, that gap is the business.
- Payment processing built around independent merchants, especially rural businesses.
- Cash discounts and dual pricing let owners reconsider who carries card costs.
- Monthly subscriptions, Clover software and human support make the offer tangible.
There is something appealingly unglamorous about this focus. A repair shop needs to collect a bill. A restaurant needs to close a tab. Neither necessarily needs a sprawling software project. VizyPay sells ways to accept payments in person, online and on the road, with a particular interest in owners who have little time to decipher the machinery behind them.
A business built next door
Austin Mac Nab and Frank Pagano were neighbors before they were business partners. Mac Nab brought payments experience; Pagano brought the perspective of a small-business owner. In 2017, they and a third founding partner pooled $197,000 of their savings to start VizyPay. The opportunity was specific: merchants were being sold complicated payment arrangements that did not fit their businesses.
Mac Nab initially went door to door, signing roughly 20 customers a month for the first three or four months, according to his account. Then he returned to the office and took on underwriting, support and recruiting. What became difficult was the founder's capacity. Learning every job was one challenge; trusting other people to do those jobs became the next.
The early method contains a useful lesson. Sell the service personally, learn where customers get stuck, then build the organization around those sticking points. The dangerous part is keeping every decision attached to the person who knocked on the first door.
The fee doesn't vanish
VizyPay's signature cash discount program starts with pricing. A merchant builds card-processing costs into the regular price, then offers a discount for cash. Its technology separates the processing component when someone pays by card. Dual pricing makes the choice explicit by presenting both cash and regular prices.
This distinction matters. The merchant can reduce its own processing expense because the price paid changes. The underlying cost of accepting a card still exists. Someone carries it. A business owner deciding whether to switch should be thinking about customer expectations as carefully as the monthly statement.
VizyPay also publishes traditional interchange-plus pricing: $15 a month, with a stated margin of 0.35% plus 10 cents per transaction above interchange. Its cash discount subscriptions are $25, $50 or $99 monthly, depending on processing volume. Dual pricing is listed at $25 a month. These are published program terms, not a complete quotation for every business.
The obvious question is whether the customer will accept the arrangement. In a price-sensitive shop, a visible difference between cash and card could introduce friction. In another business, customers may welcome the choice. The arithmetic can be straightforward while the conversation at the counter remains delicate.
Software meets the person at the till
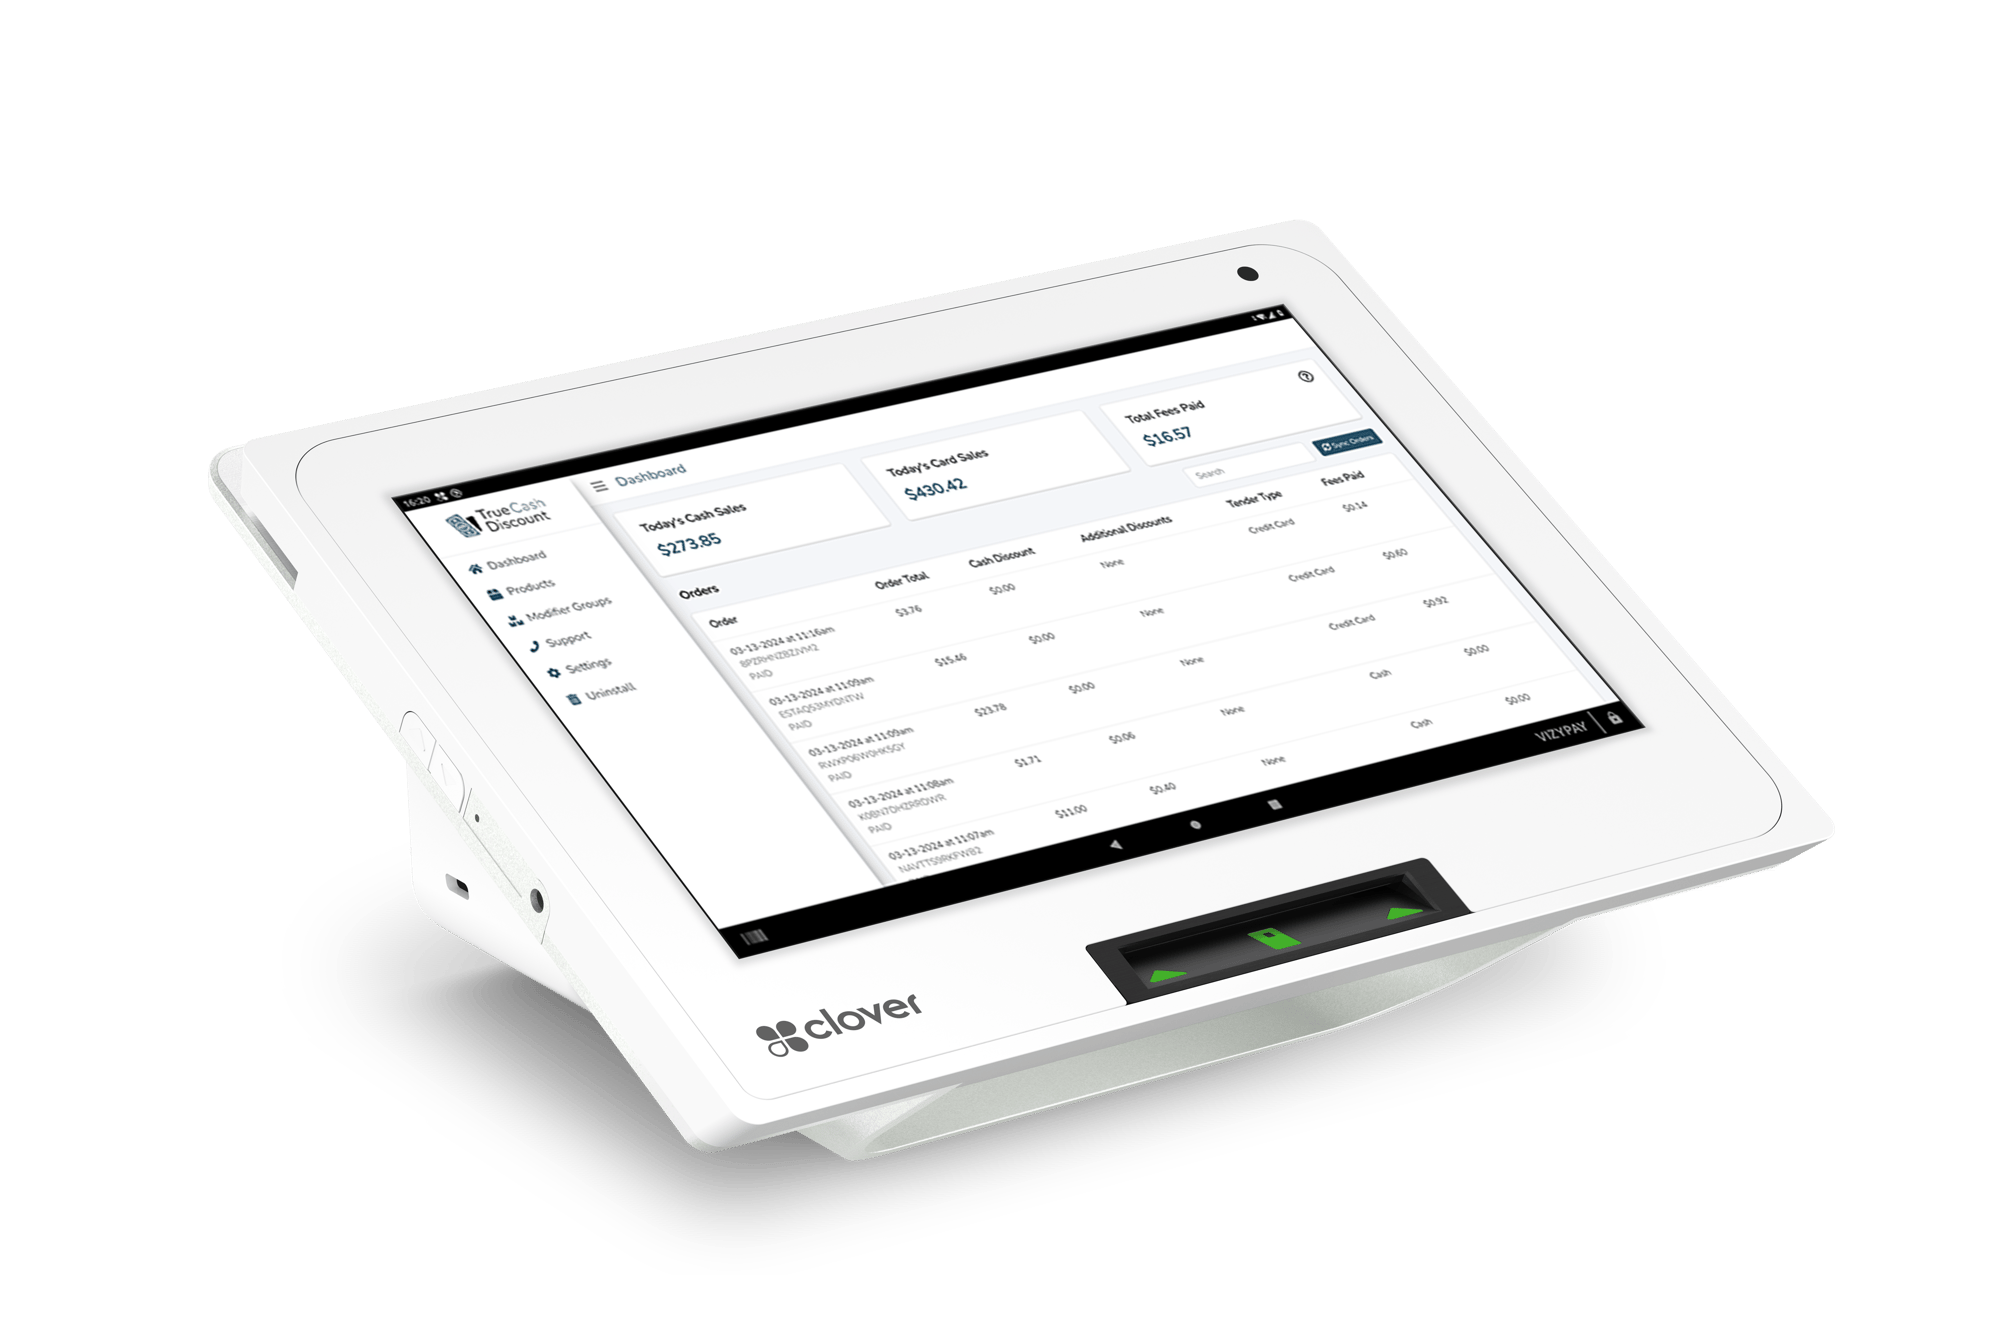
The company's True Cash Discount app brings cash discounting and dual pricing to Clover point-of-sale equipment. Its wider technology offering includes terminals, POS systems and mobile payments. VizyPay says it provides installation and equipment training at no cost, and offers an equipment placement program with qualification requirements.
That is where its expertise becomes practical. Choosing a pricing program is only part of switching processors. Someone has to configure the device, explain what staff should say and make sure the next transaction works. A useful demonstration starts with your ordinary sale, then tests the awkward cases: refunds, tips and the payment methods your customers actually use.
Thirty seconds is a product feature
VizyPay says its support team aims to answer in 30 seconds or less. Treat that as a service promise, rather than a guarantee about every call. Still, the promise reveals its positioning: the person answering the phone belongs in the product description alongside the terminal.
Its hiring philosophy follows a similar logic. In 2022, more than nine in ten employees had entered without previous payments-industry experience. Mac Nab emphasized attitude and willingness to learn. The tradeoff is clear: hiring beyond the usual industry pool broadens access, but makes training and accountability essential.
“They probably don't have a CFO to look over a [card processor] statement”
Frank Pagano, discussing small-business customers in 2022
Find the people merchants already trust
Distribution is another part of the design. A 2023 partnership with Clear Lake Bank & Trust connected payment services with a community banking relationship. In February 2024, VizyPay partnered with The Boutique Hub, whose membership then exceeded 7,500. That figure describes the partner's community, rather than 7,500 confirmed VizyPay customers.
In August 2025, VizyPay announced its fifth consecutive Inc. 5000 appearance and introduced VEXIS, its proprietary CRM. In June 2026, it announced a Jaris partnership for embedded business lending. Applications were available within the VizyPay experience; instant payouts were described as a future development. Payment acceptance was becoming the starting point for a broader merchant relationship.
Start with one month's statement
VizyPay competes in a crowded merchant-services market. Helcim also publishes interchange-plus pricing. Transparency alone cannot settle the choice; hardware fit, support and the economics of a particular shop matter.
The useful thing to copy is the sequence: find an overlooked customer, solve an expensive recurring irritation, and make the service understandable. For a merchant, that starts with one month's statement and a written comparison. Include transaction size, card mix, equipment and customer response. A smaller processing bill is attractive. The better test is what remains after the entire business has lived with the change.
Keep exploring
Watch / listen
Austin Mac Nab on VizyPay's vision From the Ground Up / interview ↗ VizyPay video library Product help and company videos ↗