In June 2026, Shell offered an unusually blunt assessment of two assets it was selling. According to its modeling, Na Kika and Coulomb would not make a meaningful contribution to its production by 2030. In September, Talos Energy completed the purchase of interests in those same assets. Talos described them as a way to expand its offshore business. The seabed had not changed. The owner had.
- Read the geology again, with better tools.
- Connect new wells to infrastructure already in the water.
- Buy selectively, then pay for the upkeep and eventual retirement.
That difference in perspective gets close to the heart of Talos. The Houston company explores for and produces offshore oil and gas. Its expertise lies in deciding which reservoirs, facilities and overlooked connections deserve another investment. The interesting question is how a field that has become less important to one company can become useful to another.
The platform next door
Imagine finding oil beneath the ocean. Before it becomes revenue, someone must drill wells, install equipment, move the hydrocarbons to a processing facility and get them to market. A discovery near an existing platform can use a subsea tieback: a connection that brings production to that facility. Geography becomes a financial advantage. A promising reservoir in the wrong place can remain an expensive curiosity.
Talos brings geology, geophysics and reservoir engineering to that calculation. Its website describes a seismic library covering 97,000 square miles. Seismic data helps teams interpret underground structures; reprocessing can change what those structures appear to contain. The skill is connecting that interpretation to an executable development plan, with a facility capable of handling the production.
●
New resource → subsea connection → existing processing capacity
The founding team had already worked together at Gryphon and Phoenix Exploration before starting Talos in 2012. Apollo and Riverstone announced up to $600 million in equity commitments. The original proposition emphasized acquiring Gulf assets and applying technical expertise to mature fields. Experience came first; the new company gave it another balance sheet.
Scale arrived through transactions. Talos began trading on the New York Stock Exchange in 2018 after combining with Stone Energy. In 2024 it acquired QuarterNorth, in a deal announced at $1.29 billion. These were purchases of producing assets and future drilling opportunities. Each brought an immediate operating business, along with estimates about what could still be extracted.
The valve that stopped the story
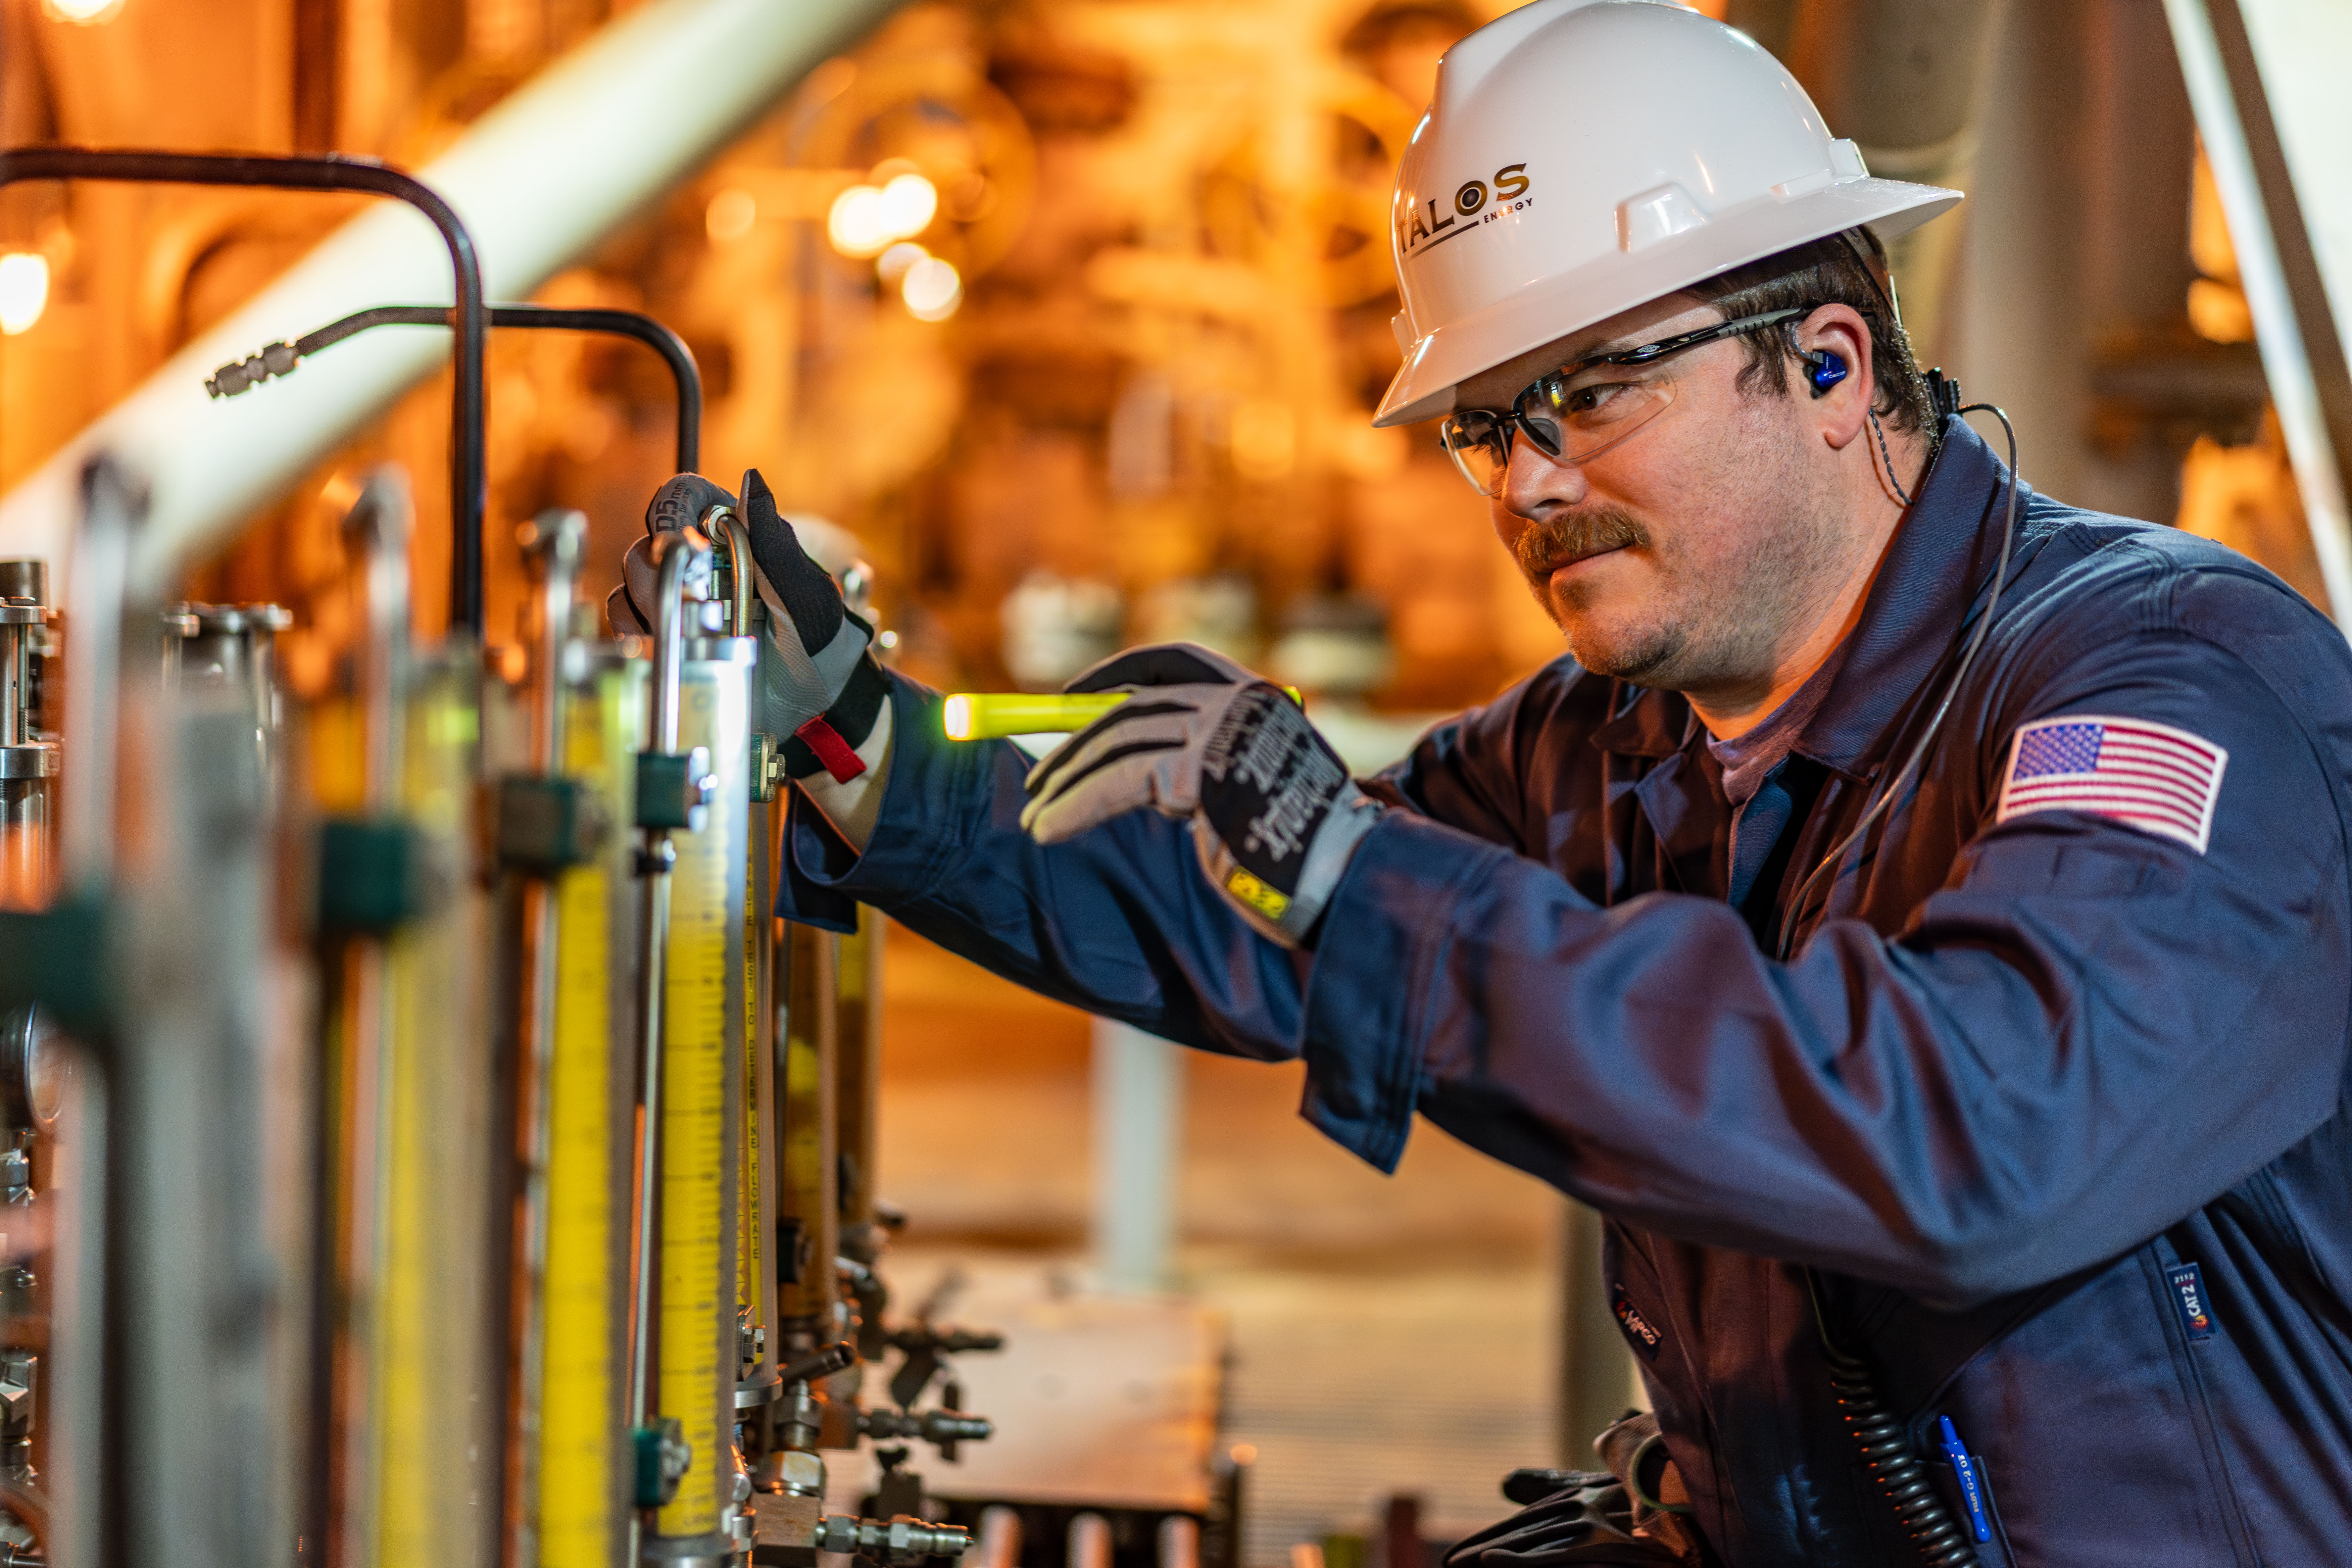
Consider Sunspear. Talos reported first production in the second quarter of 2025. In July, an early failure of its surface-controlled subsurface safety valve forced a temporary shutdown. The reservoir could be productive and the development plan sensible, yet a component could interrupt the whole sequence. Offshore economics depends on those unglamorous details working together.
Then there was Manta Ray. Drilled in late 2025, the non-operated well encountered hydrocarbons but was deemed noncommercial. Talos held a 40% working interest. Finding oil or gas answers a geological question. Whether the volumes, costs and expected prices justify producing it is a separate examination. Manta Ray passed one test and failed the other.
The distinction matters when reading Talos’s accounts. For 2025, it reported $1.78 billion in revenue and a $494.3 million net loss attributable to the company. That loss included $454.5 million in noncash impairment charges as lower average oil prices reduced the accounting ceiling on asset values. It also generated $935.8 million in operating cash flow. Cash generation and accounting profit tell different parts of this business’s story.
What a narrower company chooses
Talos has also changed where it puts its money. In March 2024, it sold its entire carbon-capture and sequestration business to TotalEnergies for approximately $148 million, including retained cash. Talos reported roughly twice its invested capital and used the proceeds to repay credit-facility borrowings. The sale turned a newer business into financial room for its offshore operation.
Paul Goodfellow became president and CEO in March 2025. After reviewing the business, growth prospects and market trends, he announced an enhanced strategy in June. Talos would improve existing operations, grow production and profitability, and build a longer-lived portfolio. Its target included approximately $100 million in additional annualized cash flow in 2026 from operating and organizational improvements. That was a target, with execution still required.
“Improve the business every day.”First pillar of Talos’s June 2025 strategy
Its customers make the commercial logic concrete. Talos sells crude oil, natural gas and natural gas liquids to business buyers. Shell Trading, Exxon Mobil and Chevron accounted for 35%, 23% and 12% of 2025 revenue, respectively. Most production is sold under contracts shorter than a year at market-based prices. Talos supplies the upstream end of the energy chain; shoppers never need to recognize its name.
A second look, with a bill attached
The September 2026 acquisition makes the strategy tangible. Talos paid $420 million net cash at closing, subject to adjustments, for a 50% operated interest in Coulomb and a 25% non-operated interest in Na Kika and associated fields. BP operates Na Kika. Talos gains production and infrastructure access while accepting dependence on another operator for part of the package.
The next opportunities stretch beyond inherited facilities. In July 2026, Talos agreed to acquire half of Repsol-operated Block 29 offshore Mexico, containing the Polok and Chinwol discoveries. Its terms include a contingent $30 million payment at a final investment decision and up to $20 million toward the next exploration well, plus certain reimbursements. Regulatory approvals and a future investment decision remain gates to pass. The agreement buys participation in a development opportunity, rather than immediate barrels.
The broader transaction also carries decommissioning obligations. Buying a working facility means inheriting responsibilities for its final chapter. Shell’s forecast and Talos’s ambitions can therefore coexist: a smaller owner may value incremental production differently, but it still faces maintenance, reservoir decline, commodity prices and retirement costs.
There is a useful lesson here for anyone allocating capital. Examine what an existing asset enables before paying to build another one. Reuse can shorten the route from an idea to revenue. The approach needs reliable infrastructure, credible subsurface estimates, available capacity and enough financial room for interruptions. Without those conditions, yesterday’s investment becomes tomorrow’s liability. Talos’s wager is that a careful second look can reveal which is which.