A rent payment is an oddly forgettable thing. Make it every month and it keeps a roof over your head. Apply to buy a roof of your own, however, and the evidence of those payments may need an introduction. Synergy One Lending has made that introduction part of its business. Its Renters Advantage program gives eligible positive rental history a route into the mortgage assessment. The interesting question is how to persuade a nervous buyer to use it.
- For the buyer: purchase loans, refinancing and home equity financing, with a loan officer alongside the app.
- The useful wrinkle: eligible rent payments can help tell a fuller borrowing story.
- The business bet: digital convenience, supported by people and a larger lending platform.
01 / A receipt gets a second life
Consider what the borrower is being asked to do: connect financial information to a process that will judge whether they can buy a home. A button alone is a thin argument. Renters Advantage asks applicants for their monthly rent and invites them to verify payments by connecting to online banking. A loan officer then reviews the application. Someone has to explain why the connection is worth making.
A Fannie Mae case study describes Synergy One putting that explanation near the beginning of its digital application. The lender supported the rollout with agent outreach, borrower campaigns, scripts and examples for loan officers. It reported digital asset-verification adoption of 73%-78% among prospective buyers. That figure measures participation in verification. It does not measure how many applicants received a mortgage.
There is a practical lesson here for anyone designing a financial service. Put the benefit beside the request for data. Give employees words they can use in a real conversation. Measure whether customers take the next step. The software feature matters, but so does the sentence that makes someone comfortable enough to try it.
02 / The mortgage still has a human attached
Synergy One serves people buying homes, replacing existing mortgages and borrowing against equity. Its purchase menu includes conventional, FHA, VA, USDA, jumbo and renovation loans. Those names represent different eligibility rules and purposes. Choosing among them takes more than finding the smallest number on a screen. The company pairs its digital tools with loan officers who can help borrowers compare options.
S1 Connect handles recognizably unglamorous work: calculating payments, scanning documents and showing application progress. These are the chores that accumulate around a house purchase. Moving them onto a phone can reduce the friction of getting a file from one person to another. The expertise sits in understanding the file and explaining what happens next.
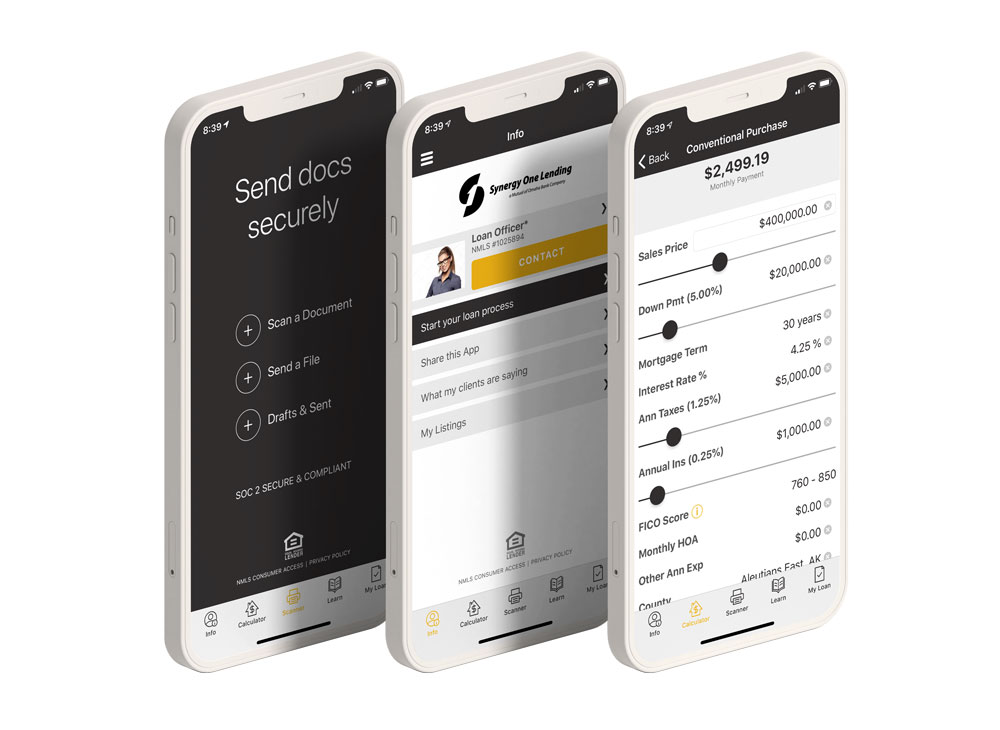
S1 FinFit starts earlier. The free personal finance app offers budgeting, credit monitoring, spending tracking and mortgage-readiness tools. It gives someone who is still preparing to buy a reason to interact with the lender. Our reading: that is useful customer acquisition disguised as the rather sensible habit of getting your finances organized before the house hunt.
A bank, a credit union or an independent broker may offer another route to the same home. Synergy One competes over the experience of getting there: who answers the question, where the documents go and how clearly a borrower can see the next task. That proposition is especially relevant when a customer wants both a phone-based process and a person to call. It depends on the handoffs working; a progress screen is only helpful when the underlying work keeps moving.
03 / Five minutes is one part of the clock
The home equity offering supplies the attention-grabbing promise: preapproval in as little as five minutes and funding in as few as five days. The distinction matters. Its process uses a soft credit inquiry and automated valuation, with a hard inquiry later after rate and term selection. Electronic verification helps the process move; manual document uploads can slow it down.
There are costs behind the convenient interface. The HELOC disclosures say an origination fee is deducted from proceeds, and loans above $400,000 require a borrower-paid appraisal. Texas is excluded from the advertised five-day funding. A useful offer still requires a careful reading of the actual terms.
For refinancing, Synergy One itself notes that lifetime finance charges may increase. A smaller monthly payment can therefore tell only part of the story. Comparing a lender means comparing the rate, fees, term and total cost together. An attractive application does not settle that arithmetic.
04 / Independence needed a balance sheet
The brand dates to 2013, but the current retail business has a second beginning. In 2020, Steve Majerus and Aaron Nemec led a management purchase of the retail channel and Synergy One name from Mutual of Omaha. The earlier reverse-mortgage operation stayed behind. In a later interview, Majerus described employees investing alongside management, giving the relaunch a very literal form of buy-in.
What strained first was demand. Majerus recalled moving roughly 350 employees onto a new platform, scaling into the pandemic-era opportunity and then facing a sharp fall in business. His account makes clear how quickly a mortgage organization must change pace. A smooth application cannot keep customers refinancing when the market gives them less reason to do so.
The company completed $50 million in corporate note financing in 2021, with Brean Capital advising. That was debt capital for expansion plans including technology, distribution and servicing. It was neither a revenue figure nor a venture valuation. Building a convenient borrowing experience takes a balance sheet as well as a product team.
05 / The next handoff is a bigger one
By June 2026, the argument for scale had brought Synergy One to a merger with American Pacific Mortgage. The announcement said Synergy One would keep its brand. In July, a company release described it as an APM division and announced an agreement to receive Newrez’s distributed retail business. The deal terms were undisclosed.
“Scale is becoming essential to win”
STEVE MAJERUS
June 2026 merger announcement
The distinctive proposition is the combination: a rental-history pitch, practical phone tools and an organization built around originators. Borrowers can find digital applications elsewhere. Synergy One’s test is whether its people make the next decision easier to understand. It begins with something as ordinary as a rent receipt. It succeeds only if the borrower can follow the story all the way to closing.