The mortgage application was going digital. The benefits forms were still paper. In a case study about Intercontinental Capital Group, benefits specialist Ep6ix describes a company that expanded from 500 to 1,500 employees in 2020, spread across more than 30 states. Three new insurance carriers, a new medical offering, and no benefits administration system. Growth had arrived before the machinery to handle it.
It is an unusually useful detail about a mortgage lender. Buying a home produces its own small mountain of forms. A company promising to make that experience easier has to master the same problem inside its own walls: getting information to the right person before confusion becomes delay.
- The offer: residential mortgages with online application steps and human guidance.
- The growth problem: more people required better internal systems.
- The test: promises about speed and price had to survive the fine print.
Several front doors. One lender.
Founded in 2005 and based in Melville, New York, ICG operates in residential mortgage origination. Its customers are people buying homes or refinancing existing loans. Company materials describe conventional, FHA and VA programs, while its brand roster has included Own It Home Loans, Veterans Community Home Loans, Fellowship Home Loans, Proven Mortgage and eReverse.
Those names reveal a distribution strategy. A military household and a senior considering a reverse mortgage can arrive with different questions, even when the lender behind the conversation is the same. ICG’s documented network of retail branches and consumer call centers gave those borrowers several ways into the business. Its product is the financing; the website helps move the application along.
The website reduces the journey to a conversation, verification and a rate lock, then closing. A loan specialist remains available alongside the digital process. Against bank lenders, credit unions, other nonbank lenders and brokers, ICG emphasizes lower overhead and personal help. That is a positioning claim, not evidence that every borrower receives the cheapest loan.
The distinction matters commercially. ICG is selling mortgages, with fees and the economics of originating loans, rather than subscriptions to an application. Technology can reduce administrative effort. It does not remove underwriting, eligibility requirements or the need to explain what a borrower is agreeing to.
Charlotte had the people
By December 2020, the company was planning a larger operations presence in Charlotte. The announced commitment was specific: $5,844,450 in capital investment and 500 additional jobs over five years. Proposed roles included sales and marketing, fulfillment, technology, administration and management. A mortgage business needed more than people who could sell mortgages.
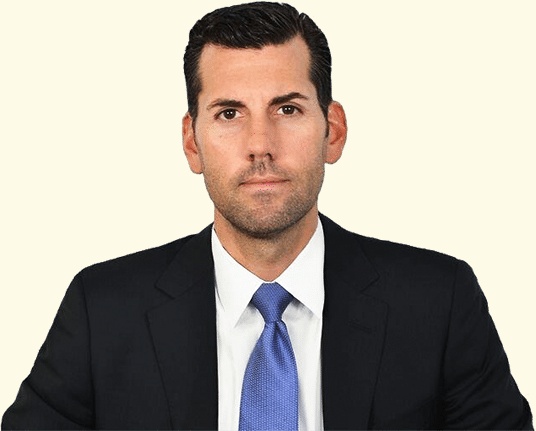
Founder and CEO Dustin DiMisa considered Indianapolis and Richmond as well. His explanation for choosing Charlotte stressed recruiting and retaining talent. An existing local operation gave him something more tangible than a city’s sales pitch: experience employing people there.
“I felt in my gut we would be more inclined to being successful there with attracting the talent and retaining it for years to come.”Dustin DiMisa on choosing Charlotte, December 2020
North Carolina approved potential Job Development Investment Grant reimbursements of up to $7,694,250 over 12 years. Charlotte’s council agenda described a separate city investment grant capped at $109,661 over seven years. These were conditional incentives tied to performance. The announcement recorded commitments and targets; it was not a receipt showing 500 completed hires.
planned capital investment
over five years
The price of a promise
The Washington advertising record supplies a harder test of simplicity. In charges resolved through a 2022 consent order, the state’s Department of Financial Institutions challenged solicitations promising cash within 15 days. The department said ICG’s own data showed that only 5.7% of its Washington cash-out loans delivered cash within that interval from submission.
ICG and DiMisa agreed not to contest the charges. The order set a $300,000 fine, with half stayed, and required advertising compliance review before paying certain branch advertising expenses. A further August 2024 order required a $40,000 fine and conditioned Washington mortgage activity on payment. These are dated regulatory terms, not a statement about today’s payment status.
For a lender selling relief from complexity, the gap between a headline and its conditions is part of the product experience. An application can feel effortless while the transaction remains demanding. Speed needs a definition. So does cost. Removing a named fee does not, by itself, explain the economics of the whole loan.
ICG’s own website illustrates how much detail can sit beneath an advertised rate: its disclosure assumes a California purchase, a minimum 760 credit score, 80% loan-to-value, a debt-to-income ratio below 40% and 1.99 discount points. Those assumptions belong beside the headline number when assessing what the advertisement actually describes. A rate without its conditions tells only part of the story.
The person after the form
The benefits project offers a more constructive example. Ep6ix says it introduced an administration platform with carrier feeds and supported enrollment with 20 trained benefits counselors. It reports 1,325 virtual consultations. Software organized the information; people helped employees understand their choices. The vendor’s account describes both parts as necessary to the solution.
DiMisa’s Consumer Connect project applies a related idea to borrowers: speak directly with customers, then take their experiences back to employees. In a January 2026 personal post, he focused on housing affordability and the economics behind monthly payments. That writing documents his interests, rather than a new company product or a measured improvement in loan outcomes.
There is a practical lesson here for anyone building a service business. Put the customer’s form beside the employee’s workflow. Look for the places where someone must re-enter information, interpret a promise or chase a missing document. Those are sensible places to examine before adding another attractive screen.
That approach has limits. A digital interface cannot make an ineligible borrower eligible, turn an advertised assumption into a personal quote, or make a hiring target happen. ICG’s story is interesting because the ordinary work keeps returning: staffing the operation, checking the message, explaining the terms. “Easy” is a short word for a long chain of responsibilities.