Samir Shergill’s cousin had finally landed the kind of order that makes years of work feel justified. A major retail chain wanted to buy. There was one awkward detail: fulfilling the order required money the business needed to borrow. The financing offers were so expensive that fees and interest threatened to leave the owner with very little for his trouble. The big break came with a bill attached.
Shergill helped his cousin work through the cash requirements. He later described the experience as emotionally affecting. Here was someone putting a livelihood into a business, finding demand, doing the difficult work, and discovering that the financial arrangements could swallow the reward. The customer wanted the product. The arithmetic was less enthusiastic.
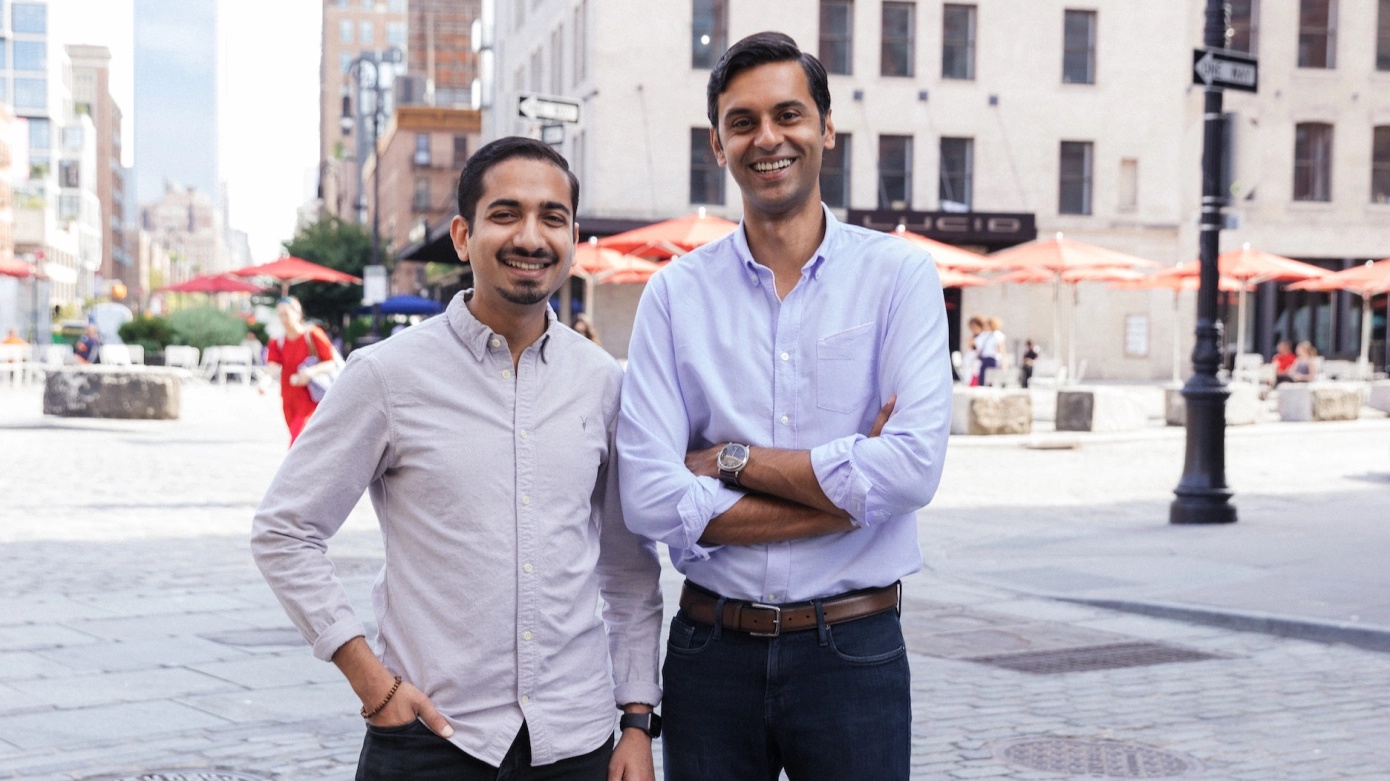
That episode supplies a useful way into Shergill’s working life. Today he is the New York-based co-founder and CEO of Highbeam, a financial technology company for consumer brands. His subject is the space between a business looking successful and its owner actually having money. It is a space with plenty of room for unpleasant surprises.
The engineer behind the bank balance
Shergill began in software engineering at Microsoft. His education combined a Bachelor of Engineering Science in Computer Engineering at Western University with an MBA at Harvard Business School. He also worked as an engagement manager at McKinsey. Code, business school, consulting: the ingredients were accumulating for a career spent asking how complicated organizations work.
At AppNexus, the advertising technology company later acquired by AT&T, he held product and business leadership positions. His responsibilities included international expansion and commercial activity across Japan, Asia-Pacific and Latin America. He helped build publisher and advertiser relationships and held roles in product and strategic initiatives.
Advertising brought him into contact with ecommerce from a particular direction. He saw businesses trying to acquire customers. In a later conversation with Stephen Brown, he traced his entry into the sector to that experience at AppNexus. The software engineer had found himself close to the machinery that helped online merchants sell.
There is a revealing change of emphasis in the move to Highbeam. Advertising concerns itself with bringing people through the door. His subsequent business concerns itself with what happens after orders start arriving. A founder can become very good at selling and still face an expensive problem paying for the next batch of goods. A successful campaign does not rearrange a supplier’s payment calendar.
The calendar that sales charts leave out
Highbeam was founded in 2021 by Shergill and Gautam Gupta. Gupta brought experience from Shopify, Venmo and Alloy. Their backgrounds put the systems used to sell products beside the systems used to move money. The company’s founding account describes conversations with hundreds of business owners about managing finances. The responses suggested that making a sale and understanding a business’s cash were very different accomplishments.
The founders focused on a familiar collection of chores: banking, borrowing, supplier payments, spending and forecasting. Those jobs often sat in separate products. A spreadsheet was left to explain how they related to one another. Each tool could perform its own task while the owner still struggled to see the whole business.
For an illustrative example, imagine a clothing label paying a factory before its new collection reaches the warehouse. Advertising bills arrive. Stock sits waiting to sell. Receipts arrive on a different schedule. The collection can be popular while the balance is tight. The calendar has its own opinion about the business.
- 01Pay supplierCash leaves
- 02Hold stockCash waits
- 03Make salesRevenue appears
- 04Get paidCash returns
Illustrative sequence. The intervals vary by business.
Highbeam’s answer brought financial products and cash management into a shared platform. Shergill was pursuing a relationship with the operator as much as a collection of features. The company is a fintech, with banking services provided by Thread Bank. The useful distinction for his story is that he chose to build around a type of customer and the recurring decisions that customer has to make.
A first customer wearing Turkish shoes
Mickey Ashmore, the founder of Sabah, offers a particularly concrete example of the people Shergill wanted to serve. Ashmore built a footwear business around handmade Turkish shoes and a personal approach to retail. Early sales took place from his East Village apartment. Customers could gather, have a drink and leave with shoes. It is difficult to imagine a banking product designed around an average company fully describing that one.
Ashmore says he met Shergill in 2021 and liked both him and his vision enough to move Sabah’s banking to Highbeam. Sabah became the company’s first customer. Years later, Ashmore was still describing the relationship as a partnership that had lasted through difficult and good periods alike.
That first commitment mattered in a way a product demonstration cannot. A bank balance is an intimate sort of business information. Persuading a founder to move the working machinery of a company requires more than a handsome screen. Shergill had to become someone an operator would trust with the practical business of keeping money moving.
The relationship also gave him a connection to a different definition of success. Sabah grew without outside investors dictating a deadline for returns. Its founder cared about the experience of the shop and the character of the business. Serving an owner like that means understanding why he started, as well as what he sells. A forecast is useful partly because it can protect the choices that make the company his.
“Founders need undeniable social proof before they’ll trust you with their financials.”
Samir Shergill
Trust has a longer timetable
Shergill made that observation while discussing Highbeam’s marketing work. It is a compact explanation of the challenge he chose. A merchant can experiment with an advertising tool and inspect the results. Moving financial operations asks for a deeper commitment. Other founders’ experiences become part of the evidence a prospective customer wants.
There are signs of how he thinks about that relationship in the stories he chooses to share. He has celebrated Still Here founders Maurice and Sonia Mosseri, early Highbeam customers who became friends. He wrote about the unexpected pleasure of appearing together on a SoHo billboard for their jeans launch. Cash management had acquired a rather more public wardrobe.
Grace Myers, a Highbeam colleague, recalled asking him during her interview about the most rewarding part of building the company. His answer centered on customers and hearing how Highbeam had helped their businesses. Her account is one small workplace anecdote, but it fits the emphasis he repeatedly brings to the subject: the founder at the other end of the transaction.
The venture itself needed backing. A $7 million seed financing was publicly announced in 2022, co-led by FirstMark and Mayfield. In September 2025, Highbeam announced a $30 million Series A led by Acrew Capital, with other new and existing investors participating. Shergill was raising capital for a company intended to help other founders make better use of theirs.
Financing rounds are separate events; dates refer to public announcements.
A question worth answering before Monday
In June 2026, Highbeam introduced Luma, an AI finance product for consumer brands. The company described more than 40 workflows at launch, with forecasting at the center. The questions were familiar ones: whether the business could hire, buy inventory, increase advertising or take on debt. Shergill’s larger ambition was to make that sort of financial judgment available to operators who could not assemble a large finance department.
The product’s technical account is unusually relevant to his background. Highbeam describes a shared layer for organizing operating and financial data, then workflows that generate and execute code against that data. It also uses machine-learning models for forecasting. In that design, the calculations are meant to be inspectable. An engineering career has a use when the answer needs to survive someone asking how it was obtained.
At an Aspen Institute discussion, Shergill also drew boundaries around the AI claim. He described language models as useful for accessing, cleaning and categorizing information, while explaining that lending decisions require other models and human underwriting. Better data could help a lender understand the business; it did not make judgment disappear.
He acknowledged another obstacle: getting a business to move its financial operations onto a new system. That admission gives the ambition some weight. The hard part includes persuading busy people to change a routine on which their company depends. A convincing answer has to arrive with a workable path from the tools already on the desk.
The virtue of keeping at it
Asked in 2023 which attribute mattered most for a founder, Shergill chose tenacity. His advice to someone starting a business was equally spare: “Just keep moving!” Away from work, he described spending time with his children and watching soccer when he could. Tokyo appealed to him for its different social norms and its food.
Those details supply a modest counterweight to the language of finance platforms. This is a father who makes time for football, an engineer interested in how things operate, and a founder whose stated purpose begins with other people’s businesses. The ambition is substantial. His most useful examples remain small enough to recognize: an inventory order, an upcoming payment, a founder deciding what the company can afford.
Return to the cousin with the retail order. The episode left him with a question that extends well beyond one family’s business. What does a big break accomplish if the financing consumes the gain? He has organized Highbeam around helping founders confront that question earlier, while they still have time to change the answer.