In 2015, Richard Love offered a small business scene with an unusually pleasant setting: the boss was on a golf course. There were checks to approve, but the boss could pull out a phone, review them and sign on the screen. The signatures could travel to the checks when they were printed. Work had followed someone onto the fairway, admittedly. At least it had brought less paper.
Love was explaining a practical ambition. Businesses had reasons to keep using checks, including control over when money went out. Their owners did not necessarily want to reorganize that process around a different payment method. He wanted to make the existing routine less cumbersome. That required paying attention to the accountant, the approver and the bank, rather than simply admiring the phone.
It is a revealing way into the career of AP Technology’s founder, chairman and chief executive. Love has worked on the machinery of payments for decades. His company, founded in 1989 and based in Carlsbad, California, now says customers process more than $140 billion annually through its products. Behind that large number sits a surprisingly intimate question: who gets to say yes to this particular payment?
The printer came before the phone
Love’s route into that question began with financial systems. Before AP Technology, he co-founded Torrey Pines Research and led teams at Eagle Computer and Troy. His work included leading development of an early U.S. Treasury check-printing system, followed by development of the first desktop MICR laser printers. His career put him close to the physical act of issuing money, where the document and the system have to agree.
Printing a check sounds like a small task until the payer is a government or a bank. The paper carries instructions that must survive a trip through other people’s machinery and procedures. A printer is therefore part of a much larger arrangement. That helps explain the continuity between Love’s early work and his later interest in approvals, data movement and remote issuance: the point of friction keeps moving around the payment.
His public LinkedIn profile lists San Diego State University from 1980 to 1982 and participation on the track team. By 1989, he had started AP Technology. The company’s account of its beginnings describes a founder who wanted his own business after designing and implementing financial systems for banks and businesses. The subject was already familiar; running a company gave him a continuing vehicle for working on it.
- 1989Love founds AP Technology.
- 2015Cloud approvals meet the existing check workflow.
- 2020Checkrun’s public launch connects mobile signing with QuickBooks Online.
- 2026Remote official checks extend bank services beyond branches.
A startup, with a long memory
By 2015, Love described a company that had already survived a quarter century as still having the outlook of a startup. It neatly captured the tension in his business. AP Technology had built back-office applications for large institutions. Now cloud software and mobile devices offered a different way to put that accumulated experience to work.
The product was APeChecks, a cloud-based payment platform with a mobile front end. The opportunity Love described was specific. Small businesses might have checks prepared in batches and release them as bills became due. Keeping that control mattered. Asking an owner to abandon the routine could make a technologically tidy proposal commercially unappealing. A phone-based approval offered a smaller, more useful change.
In that light, his golf-course example becomes more than a salesman's convenient afternoon. It identifies the person around whom the software has to bend. A payment can be ready while its approver is elsewhere. Moving the approval to the phone changes that dependency. The check can remain a check, and the owner can remain the owner, with one less reason to return to the office.
“We consider ourselves a startup with 25 years of experience.”
Richard Love, 2015
A bill of rights, and a country singer
Love’s public appearances gave this fairly technical work some unexpected company. At the 2015 Mobile Payments Conference in Chicago, he joined a retail-focused panel with Greg Wilfahrt, analyst Nick Holland, former Sears and Kmart mobile-commerce executive Mario Di Prizio, and country singer Rick Monroe. A musician had a direct stake in the discussion: buying music or merchandise should not become an exercise in patience.
That conference also saw AP Technology introduce its Mobile Payments Bill of Rights, co-authored by Love and Wilfahrt. It proposed best practices around consumer confidence, transparency, security and accountability. Love presented it as a document others could adopt and develop. The ambition reached beyond making a transaction technically possible. A customer needed reasons to feel comfortable using it.
The following year, conference sessions brought Love together with actor and producer Kevin McCorkle and mobile-payments analyst Daniel Csoka. Another Chicago panel added PayPal executive Jim Ciortan, Business Insider analyst Evan Bakker and Monroe. Its Wild West theme cast payment fraud as a threat to the gold. Treasury software had found a theatrical wardrobe, though the underlying questions about data and trust remained quite sober.
These collaborations show a public side of Love’s work that a product list misses. He was willing to discuss payment systems alongside people who encountered transactions as performers, merchants or analysts. Their problems made a technical subject concrete. A delay at the moment of purchase looks different to a musician than it does on an architecture diagram, which is precisely what makes the conversation useful.
The bookkeeper enters the picture
Checkrun carried Love’s interest in practical approvals into the world of QuickBooks Online. Its own history dates its introduction to 2018 and its first customers to 2019. A May 2020 announcement introduced its mobile and cloud check-approval platform more broadly. The sequence matters: this was a product taking shape across several years, rather than a company suddenly discovering that signatures could be inconvenient.
Checkrun connected to QuickBooks Online through an API, avoiding a second round of data entry. Payments came directly from business accounts without requiring prefunding. Users could approve and sign through mobile apps, then print checks at their own offices or have them printed and mailed. Each feature addressed a step someone otherwise had to perform, wait for or repeat.
Love emphasized that the underlying payment technology also served large bank transactions. He also pointed to something less glamorous: client requests had influenced features such as storing images of printed checks back in the accounting software. The bank-scale engineering and the bookkeeper’s request belonged in the same product. A saved image would never make a dramatic conference entrance. It could, however, answer a question later.
Different locations. One payment moving through the people responsible for it.
When speed deserves a question
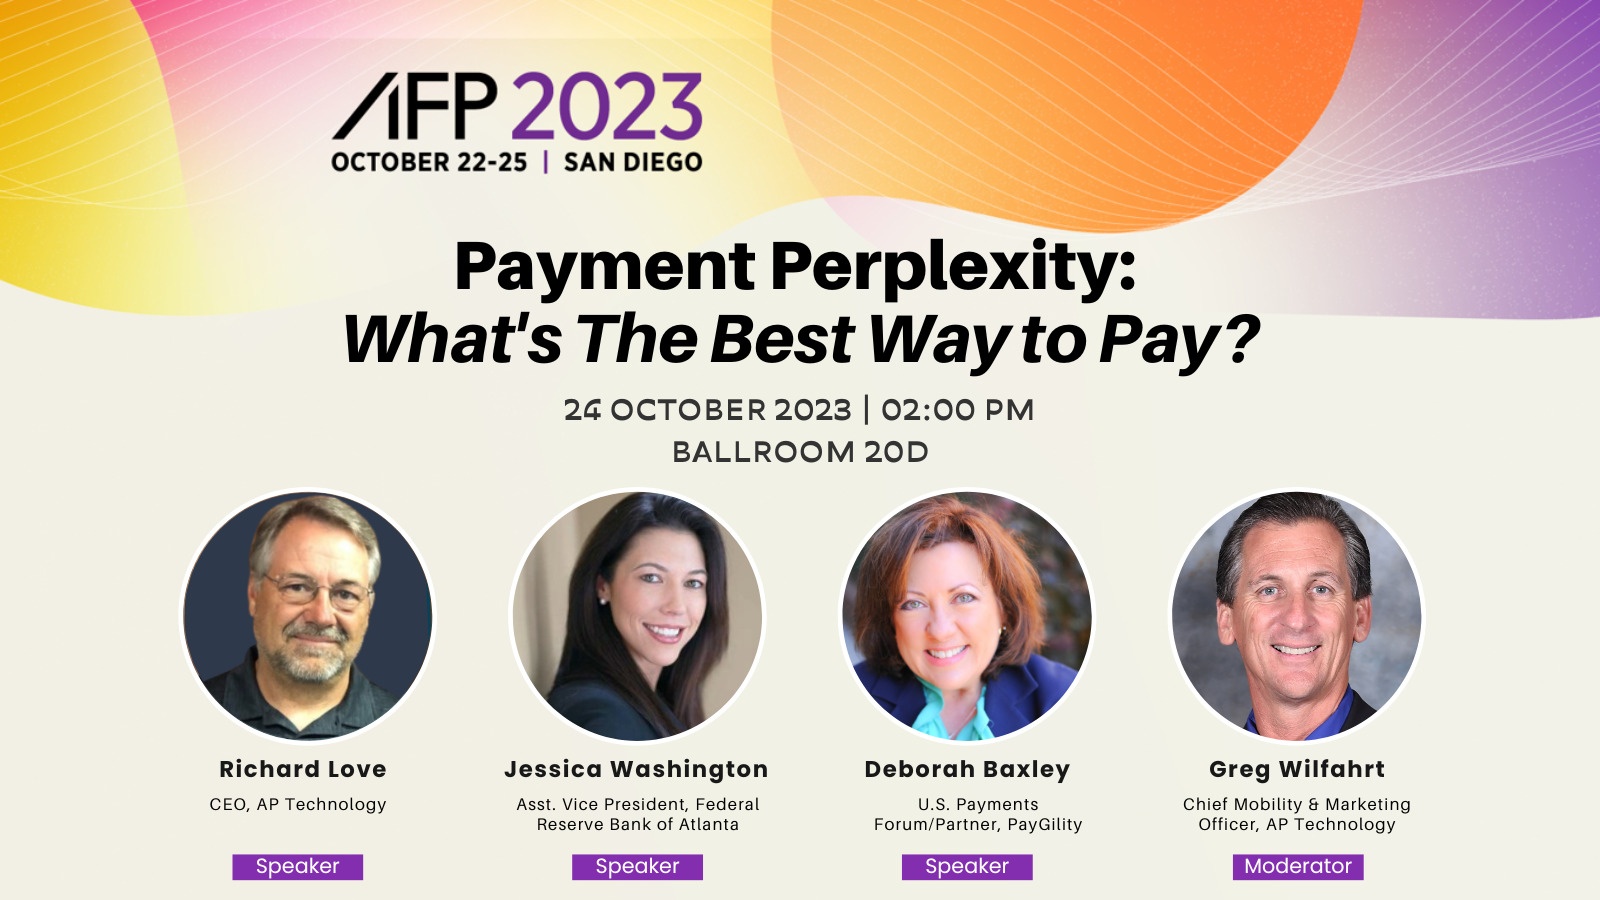
By August 2023, Love was discussing real-time payments at the MPC Digital Commerce event in Atlanta. His fellow panelist was Insider Intelligence principal analyst David Morris, with Wilfahrt moderating. Their agenda included FedNow, cards, modernized checks, wires and buy now, pay later. The range itself undermined the idea that a single payment method could suit every transaction.
Love’s memorable contribution was a caution: “Faster is not always better.” He asked whether increased transaction speed could increase exposure to fraud and buyer’s remorse when payments became irrevocable. The point was a question about consequences, rather than an objection to new technology. Once a payment becomes immediate and final, the decisions made before it leaves deserve careful attention.
Coming from someone who had spent years promoting mobile convenience, the remark has particular weight. The earlier ambition was to free approvals from a desk. The later question concerned what happened when speed compressed the opportunity to reconsider. Both positions put the user’s control near the center of the design. Convenience is attractive; choosing the right moment to commit still matters.
A bank branch, minus the trip
The more recent chapter brings Love back to a familiar object in an unfamiliar location: the official bank check printed outside the branch. In 2024 and 2025, AP Technology promoted APSecure’s remote issuance capabilities to financial institutions. Love described the recurring demands as security, speed, compliance and convenience. The customer might be a law firm trying to complete a real estate transaction without another journey to the bank.
In July 2026, Peapack Private Bank & Trust announced expanded real estate payment capabilities using remote official check printing, supported by AP Technology. Approved organizations could issue official checks at designated locations while retaining bank controls and audit requirements. In August, Love’s company announced an APSecure 5.0 showcase for New York Cash Exchange, again emphasizing payment services beyond branch locations.
The connection to his 2015 example is easy to see. In one case, an approval no longer required the owner at a desk. In the other, an official check no longer required the customer at a branch. The work travels to where it is needed, while the permission to perform it remains a serious matter. Love has kept returning to that combination for a substantial part of his career.
There is another side to the résumé. Love plays pickleball and is a certified professional coach. It is a pleasing detail for an executive whose working subject is often hidden inside administrative processes: an activity with a visible court, an immediate result and a ball that must actually cross the net. His payment work has a less visible destination. Somewhere, someone can finish a transaction and get on with the day.
Continue the conversation
Richard Love & his work