A hospital does not need another screen to worry about. It already has monitors, pumps and machines connected to its network, each useful, each another possible security problem. In 2018, University of Iowa Health Care deployed Zingbox to monitor a network of more than 45,000 connected medical devices. Behind that unglamorous assignment was a startup backed by Oriza Ventures.
This is a useful place to begin with Oriza: somebody has a difficult working day, and a founder thinks technology can improve it. Founded in 2015 by John Yu and Alex Liang, the Silicon Valley venture firm primarily backs early-stage technology companies in North America. Its investments range from enterprise infrastructure to biotechnology. Look closely, though, and the abstract categories become specific jobs.
- The offer: venture capital, operating experience and business introductions.
- The connection: networks in Silicon Valley and China.
- The test: does the technology make somebody’s work measurably better?
The people who had done the work
Before Oriza, Yu co-founded Advanced Communication Devices, a networking semiconductor business, and Viaquo, an internet security software company. He later became a founding partner and managing director at WestSummit Capital. Those experiences put him on both sides of the meeting table: building a company, then deciding which companies deserved investment.
Liang brought a different route through the same territory. He founded mobile internet company PICA, held senior roles at network businesses Asia Netcom and 21Vianet, and led US investment activity as a venture partner at SAIF Partners. His work included helping American portfolio companies expand into China. Oriza’s cross-border pitch therefore had an operating history behind it.
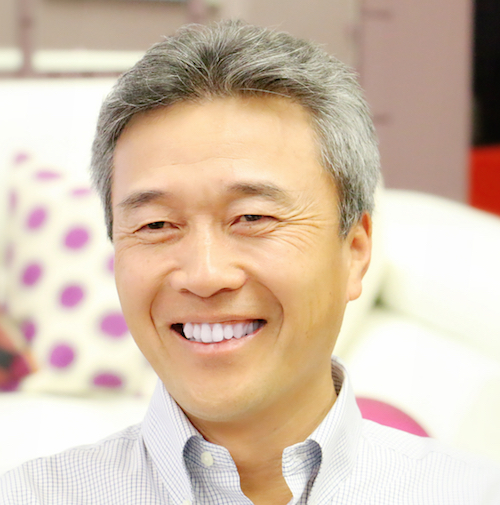
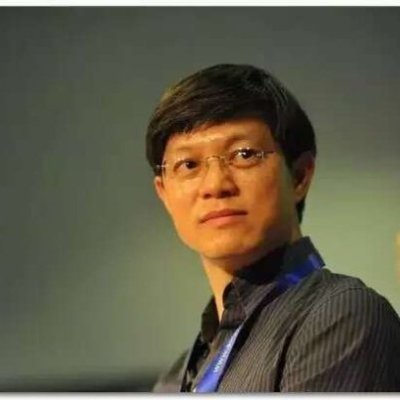
Compared with a sector specialist, Oriza presents a broader technology brief. Compared with a purely financial pitch, it emphasizes its partners’ experience and access across two business communities. That positioning makes sense for a founder facing a problem the partners have encountered. It becomes less persuasive when the relevant expertise lies elsewhere. A useful investor match depends on the company’s next obstacle.
The firm describes its approach as supporting founders through the ups and downs of company building. That proposition places it among investors offering help beyond a bank transfer. For an entrepreneur, the useful question is concrete: which hiring decision, customer introduction or unfamiliar market can this particular partner help with?
“We pride ourselves in our long-term approach to investment”Oriza Ventures · public company description
The money has two audiences
There are two relationships inside a venture firm. Investors commit money to its funds. Founders receive investment from those funds in exchange for ownership. Oriza’s management business sits between them, choosing companies and supporting the portfolio. It belongs in the early-stage venture market, where the product being offered is capital accompanied by judgment and access.
The distinction matters when reading its numbers. In December 2015, Oriza Ventures Technology Fund reported $30.3 million sold to three investors against a $100 million offering. That was fund fundraising. It was neither Oriza’s revenue nor a startup round for its management company. By its April 2026 filing, the adviser reported approximately $134.4 million in private fund assets across two funds.
Reported gross fund assets. Asset values do not show investor returns.
For prospective fund investors, the same filing lists a routine minimum commitment of $1 million for each vehicle. A founder faces a different cost: the ownership and rights negotiated in a financing. Those are different transactions, with different questions to ask before signing.
Software meets the working day
Zingbox addressed the growing problem of securing connected devices. Palo Alto Networks announced a $75 million cash agreement to acquire it in September 2019 and completed the acquisition that month. The buyer wanted device and threat identification capabilities for its security platforms. The case connects a particular operational headache to a particular strategic buyer.
Peer5 offered another kind of relief. Its browser-based technology used peer networking to improve video delivery without installing software on every viewer’s device. Microsoft acquired it in August 2021 to improve large live events in Teams. Oriza had participated in Peer5 financing. A company town hall may sound mundane; keeping thousands of employees watching without overwhelming the network is a real engineering assignment.
Connected devicesZingbox → device security
Company broadcastsPeer5 → video delivery
Available trucksParade → capacity management
Then there is Parade. Oriza participated in its $12.7 million Series A announced in February 2022. Parade sold capacity management tools to freight brokers, layering software over existing transportation systems so brokers could find trucks and book loads digitally. Customers named at the time included Armstrong Transport Group, Schneider and Worldwide Express. Improving the incumbent’s tools was a business opportunity in its own right.
Unifimoney followed a related distribution logic: give community banks and credit unions a digital wealth management platform. Oriza joined its $10 million seed financing in April 2022. These businesses served very different buyers, but both proposed helping established operators offer something their customers already wanted.
The experiment that cost too much
The portfolio also includes Atrium, whose technology business closed in March 2020. Earlier that year it had reduced its in-house legal operation and shifted emphasis toward software. Looking back, co-founder Augie Rakow told Artificial Lawyer: “It’s hard to combine venture capital with professional services.”
The difficulty was economic. Lawyers remained expensive, even with better tools. As an interpretation of the portfolio, Atrium supplies a useful counterweight to the acquisitions: automating pieces of a workflow does not establish that the whole business can scale profitably. A founder copying the approach needs to measure the cost that actually disappears.
An introduction is only the beginning
Oriza’s interests also reach into drug discovery. Portfolio company SyntheX announced a Bristol Myers Squibb collaboration in October 2022 involving its molecular glue discovery platform. The agreement offered up to $550 million in performance milestones, plus royalties. Those were conditional payments, rather than money already received.
The biotech example also complicates a tidy software-only reading of the firm. Improving freight bookings and developing a drug discovery platform involve different customers, evidence and timelines. A sensible lesson to draw is to match the investment relationship to the work ahead. A founder who needs patient scientific validation should evaluate support differently from one selling an enterprise tool with an existing customer base.
Taken together, these investments suggest a practical way to assess Oriza. Start with the problem, identify the buyer, then ask whether its partners’ experience and connections help reach that buyer. A cross-border network has value when the business needs it. A founder can test that promise by asking portfolio CEOs which introductions led to useful commercial conversations. Capital buys time to prove the proposition; customers still decide whether the technology belongs in their working day.