A receipt is an unpromising place to begin a story about wealth. It is small, easy to lose, and usually discovered after its usefulness has become an accounting problem. Yet receipt storage is one of the features myEcon sells. Beside the promises of financial progress sits a remarkably ordinary task: record what came in, record what went out, and keep the evidence.
- Financial education and software meet a direct sales opportunity.
- The core offer costs $49.95 to set up, then $49.95 monthly.
- Household savings and affiliate earnings deserve separate calculations.
The company’s name supplies the organizing principle. “My Economy” treats a household as something deserving the management attention normally given to a corporation. A family has income, costs, obligations and choices about what to do with the remainder. myEcon packages help with those choices, then offers members a business selling the package and related products.
The household gets a ledger
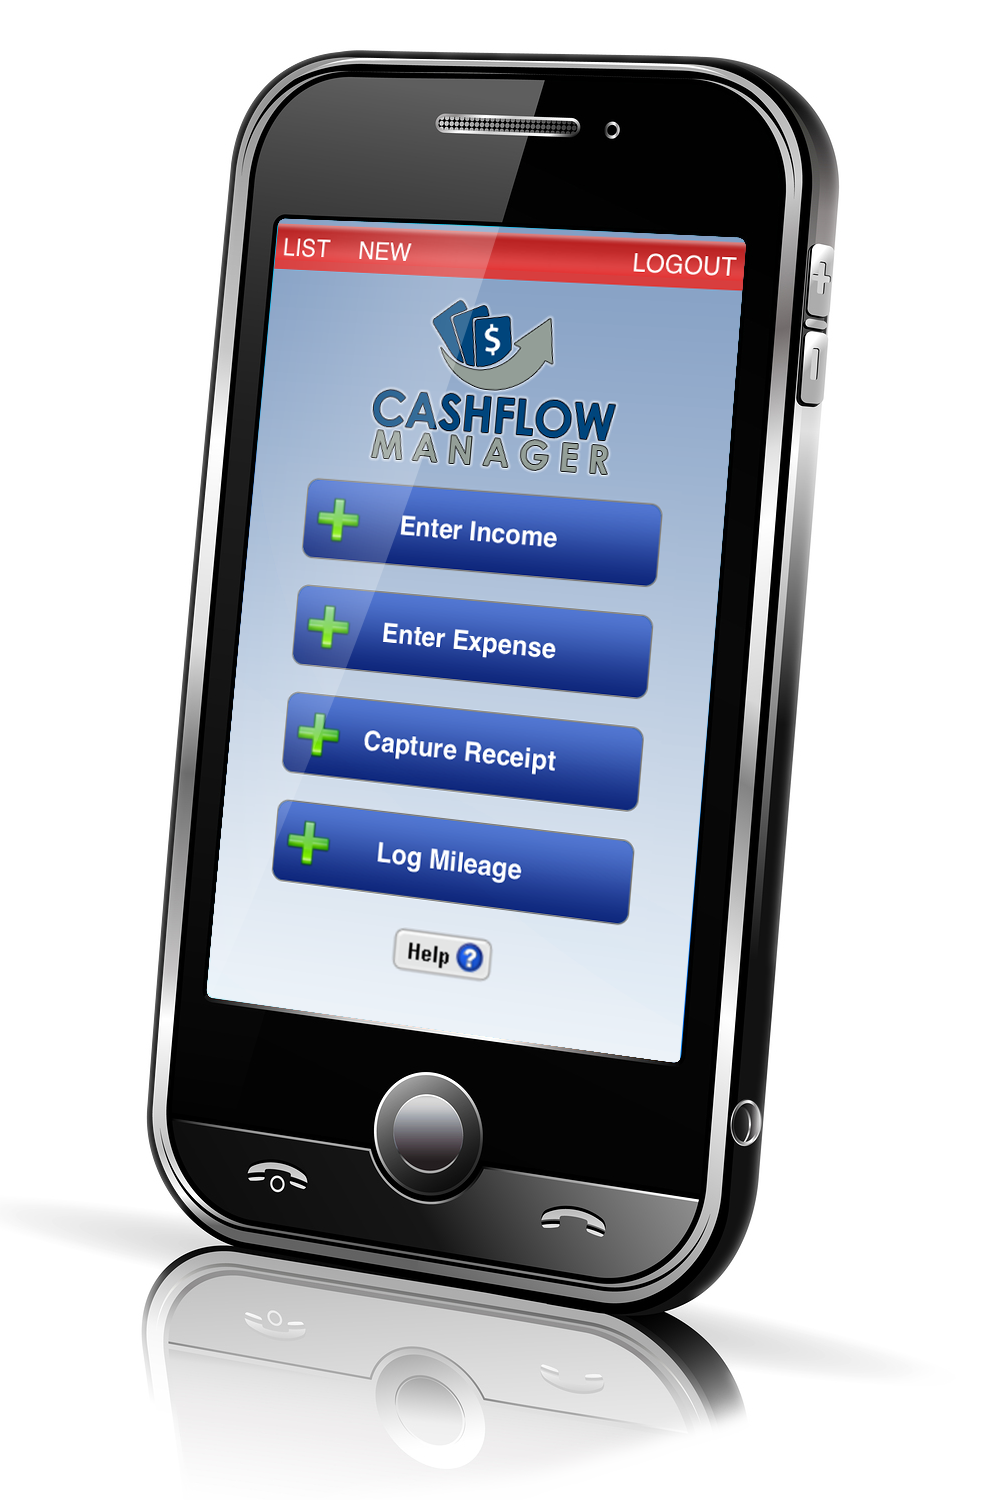
CashFlow Manager is the most literal expression of that idea. The online system records personal and business transactions, stores receipts, supports recurring entries and allows multiple businesses in one account. Categories can be preset or customized. Standalone access is advertised at $10.95 a month. The practical customer is someone whose household spending and small-business paperwork have become an awkward administrative partnership.
Credit education gets its own machinery. The myCredit System combines written and video instruction with a dispute-letter generator and a tracker. That makes the offer closer to an organized toolkit than a promise that someone else will fix everything. Its separate membership is listed at $34.95 to enroll and $34.95 monthly, beginning after 30 days.
There is a useful boundary here. Consumers can dispute credit-report errors themselves for free. Accurate negative information generally cannot be removed simply because it is inconvenient. A template can help someone organize a legitimate dispute; its value lies in instruction and follow-through. The information being challenged still has to justify the challenge.
The paycheck has a calendar
myEcon places W-4 withholding education inside its wider cashflow proposition. This is an appealing subject because a paycheck feels fixed even when its deductions deserve another look. But the timing matters. Withholding is money paid toward a tax bill during the year. Adjusting an excessive amount can increase current take-home pay while reducing a later refund.
That adjustment does not, by itself, reduce total tax liability. Too little withholding can create a bill or penalty. The IRS offers its own free estimator, using income, deductions and credits to help people check the amount. The sensible lesson to copy is the habit of checking, especially after a change in work or family circumstances.
the money→02Review
the obligations→03Give the balance
a purpose
Cashflow is useful only when the next decision is useful. Money freed from one obligation can disappear into another purchase. This is the behavioral appeal of myEcon’s broader framing: connect the paperwork to a purpose, rather than leave budgeting as a monthly exercise in regret.
A customer can become a seller
The unusual combination is financial instruction alongside a distribution business. myEcon operates through independent associates. Memberships include access to marketing tools and training, while the associate app helps users contact prospects, send prepared messages, share media and enroll people from a phone. It is software for finding customers as well as software for organizing money.
This creates two different tests of value. A household can ask whether the tools improve its financial routines enough to justify the subscription. An associate must also ask whether sales receipts exceed membership charges and other business expenses. The company’s member success stories are selected testimonials. They do not tell a prospective seller what a typical participant will earn.
Household savings and selling profit belong in separate ledgers.Two questions. Two calculations.
A budget app, a bookkeeping subscription or free public financial guidance can substitute for individual pieces. myEcon’s distinction is the bundle, the associate relationship and the sales opportunity around it. That arrangement has more appeal for someone who wants ongoing instruction and enjoys selling than for someone who only needs a receipt folder.
The moment the audience mattered
In September 2016, a merger announcement with Novae exposed a specific strategic ambition. Founder Ivey Stokes said myEcon wanted better marketing, to “become mobile,” and to attract younger people after years of reaching Baby Boomers. Novae brought a recently released mobile application into the proposed combination. Distribution and audience were explicit reasons for the deal.
Today’s associate app makes that mobile ambition tangible. Google Play describes prospecting, enrollment, company media and automated marketing access, and lists a September 7, 2026 update. The corporate leadership page names Larry Gates as CEO and COO, Carliss Curry as CFO, and June Collier as vice president of marketing. Their published biographies emphasize operations, administration and recruiting.
Put a price on the bundle
The Elite package costs $99.95 to set up and $69.95 monthly after 30 days. It adds Zingo Travel and individual Defender Plus access to the core membership. Travel discounts depend on actual bookings; identity protection is a different kind of purchase. Defender Plus includes restoration support and legal referrals through Legal Club of America, with insurance subject to policy conditions and geographic exclusions.
The company’s refund policy distinguishes retail purchases from associate enrollment. Retail customers have a stated 30-day refund window; enrollment setup fees become nonrefundable after the three-business-day cancellation period, and monthly technology fees are nonrefundable upon payment. The distinction deserves attention before a subscription becomes another household expense.
What can a reader take away? Keep the receipts. Check the withholding. Track legitimate credit disputes. Give available money a destination. Those habits travel beyond any membership. myEcon sells a structure around them, plus a chance to sell that structure to others. Its usefulness turns on whether the customer actually uses the tools, and whether the seller can make the second ledger add up.