A million dollars can be too much money for a neighborhood bank. Not too much to hold, perhaps, but too much to reassure a nervous customer with the familiar promise of federal deposit insurance. The standard limit is $250,000 per depositor, per insured institution, for each ownership category. A business with payroll due Friday or a school district holding reserves can have a perfectly good banker and still want a larger safety net. That leaves the banker with an awkward choice: find a credible way to protect the excess balance, or watch a valuable relationship walk toward a giant institution.
The short version
- ModernFi runs deposit networks for U.S. banks and credit unions; the institutions own the networks.
- Its reciprocal product distributes eligible balances across insured members and sends matching deposits back.
- The network also lets institutions source funding or sweep surplus deposits.
- ModernFi announced more than 1,000 participating institutions in September 2026.
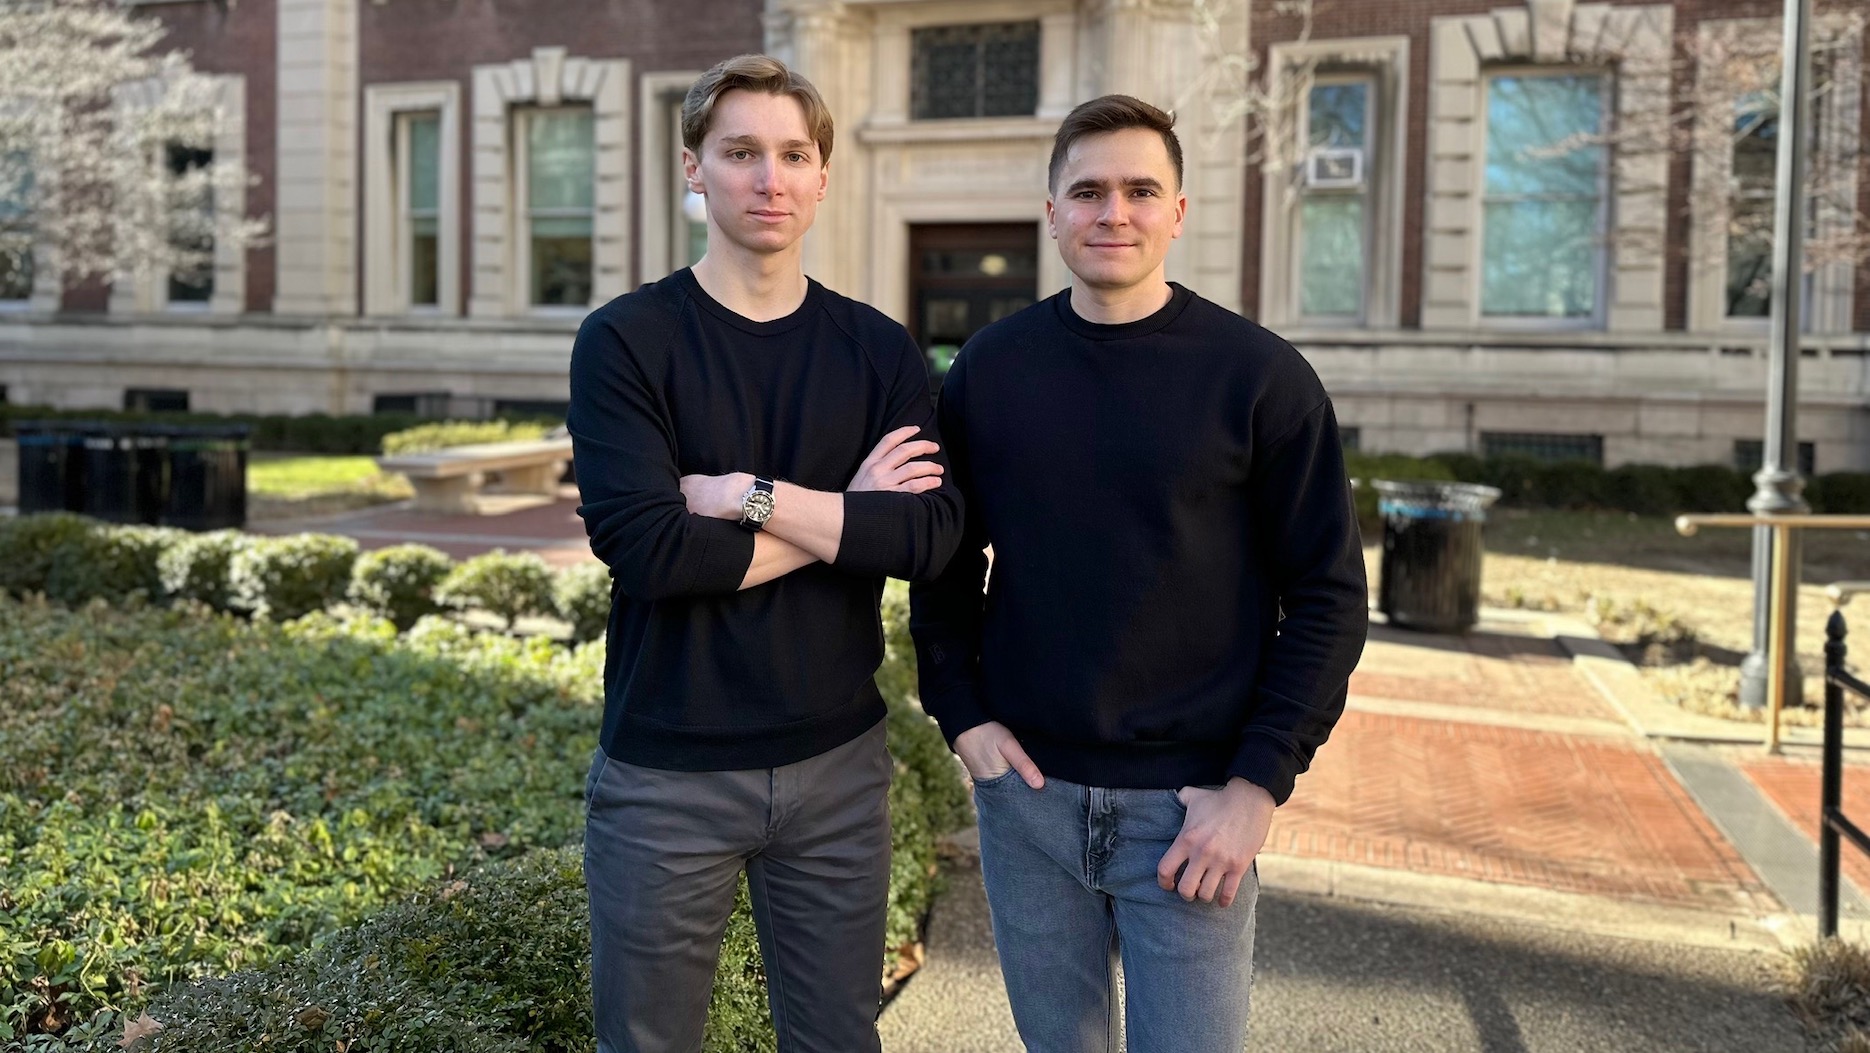
ModernFi was founded in New York in 2022 by Paolo Bertolotti and Adam DeVita to address precisely this mismatch. They began with a marketplace for banks to exchange deposits. Today the company operates two institution-owned networks: NBID for banks and ModernFi CUSO for credit unions. Its customer is the institution, not the person making the deposit. For that person, the selling point is almost comically modest: keep one account, one statement, and one familiar relationship while the machinery underneath does something far more complicated.
The phone call was the first thing to go
Bertolotti described the old wholesale deposit market as an over-the-counter business in which bank finance officers called brokers and other banks to discover prices and available liquidity. That is a revealing starting point. Banks can send money around the country, yet finding the right place for it could resemble buying a used piano: know someone, make a call, negotiate in the dark. ModernFi offered a network and software to make that process more transparent and repeatable.
The company had only just announced its $4.5 million seed round when the banking turmoil of 2023 made uninsured deposits a question ordinary customers understood. ModernFi did not invent the anxiety. It arrived with a product designed for it. The pitch widened from matching banks with surplus and shortage to helping them answer a depositor’s first question: how safe is this cash?
“It’s an over-the-counter market, meaning there’s no marketplace or exchange and the market is very antiquated and opaque.”Paolo Bertolotti, in a 2023 interview
Consider a business that wants to keep $1 million at its credit union. In a simplified example, the credit union can place eligible portions under the insured limit at several credit unions in the network. The business sees an extended insurance account at home. Behind it, ModernFi’s software tracks allocations and transactions, while the participating institutions hold the deposits. Under a reciprocal arrangement, matching money flows back to the originating institution. The customer gains access to broader aggregate coverage, subject to the rules for pass-through insurance, and the home institution keeps both the relationship and, in aggregate, its deposit balance.
Illustrative process. Coverage depends on depositor category, proper records, placement, network capacity, and other program conditions. ModernFi itself is neither an insured bank nor an insured credit union.
The same network has three moods
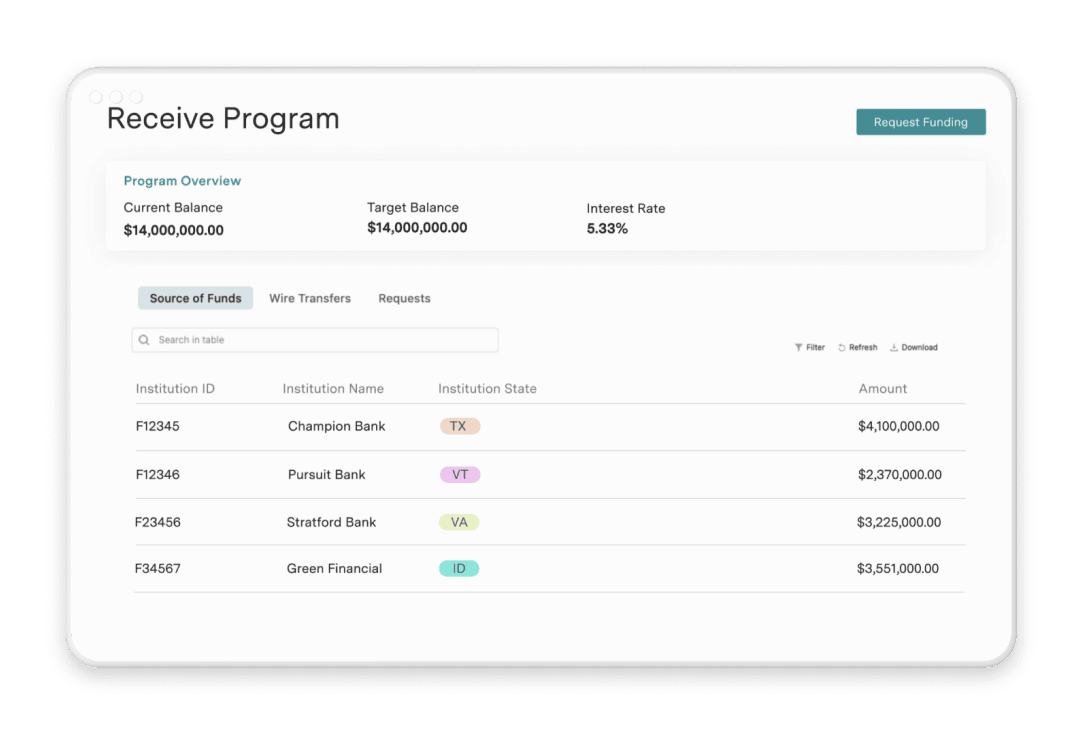
Insurance is only one use for a network of institutions willing to exchange deposits. A bank with loan demand can set a target funding balance in ModernFi’s admin portal and source deposits from other members. The company describes that funding as non-collateralized, adjustable, and priced at a displayed network rate. A bank with too many deposits can move excess balances into the network instead, reducing balance-sheet size and potentially earning fee income. The exact financial benefit depends on the institution’s costs and the network terms.
This is what makes ModernFi more than an insured cash label. It treats deposits as inventory that institutions must continually manage: some need more, some need less, and large customers need coverage. The operations are less romantic than the pitch. Public product documents describe program omnibus accounts, transaction records, allocation, reporting, and a daily wire cycle handled by Northern Trust for the credit union network. ModernFi’s engineering page speaks of reconciling every cent daily. If the promise is simple for depositors, the backstage work has to be exact.
The members own the machinery
ModernFi’s sharper distinction is ownership. NBID, launched in 2025, is a standalone network company owned by its member banks. ModernFi operates it. On the credit union side, ten credit unions hold direct stakes in ModernFi CUSO, alongside industry CUSO funders. Member governance, preferential pricing, and a share of network economics are part of the bank proposition. The model borrows from the logic of a cooperative utility: if the value of a deposit network comes from the institutions connected to it, those institutions should have a claim on the rails.
That matters in a market with existing reciprocal deposit networks, especially IntraFi, and familiar alternatives such as Federal Home Loan Bank advances or brokered CDs. ModernFi does not make those options disappear. It offers a different combination of ownership, digital integration, flexible funding, and a depositor experience that can sit inside the institution’s own channels. A banker comparing products still has to examine rates, operational commitments, insurance conditions, and the regulatory treatment of each funding source.
The scale arrived quickly. ModernFi raised $18.7 million in a 2024 Series A and announced a $30 million Series B in 2025. Investors in the latter included Canapi Ventures, Andreessen Horowitz, Curql, Remarkable Ventures, and Intercontinental Exchange. In September 2026, the company said its two networks together passed 1,000 financial institutions across all 50 states. Membership is a meaningful measure of network reach, although membership alone does not tell us how much each institution has placed or received.
The credit union story has its own timing. ModernFi CUSO launched in 2024, bringing reciprocal deposit infrastructure to a sector that historically had fewer such tools. In March 2026, the NCUA published guidance acknowledging that federally insured credit unions may use reciprocal deposits when programs are conducted safely and soundly. The company now says the CUSO serves more than 150 credit unions. Its website names large and small institutions among the wider network, from regional banks to community credit unions. That range is the point: a shared network gives a smaller institution a capability it would struggle to assemble alone.
What does it cost to keep the customer?
ModernFi does not publish a universal price sheet. In a 2023 interview, Bertolotti said the company took part of the yield banks paid on deposits and, at that time, did not charge transaction, account, or setup fees. Current pricing is not public, so that early description should not be treated as a present-day quote. The practical comparison for a bank is the total cost of acquiring and holding a large account: the deposit rate, network economics, integration work, operations, and the cost of losing the relationship altogether.
There is a lesson outside banking here. The company did not ask local institutions to become huge. It made their collective reach usable through software and gave them an ownership stake in the infrastructure. That approach works when many participants share a recurring problem, trust a common operating standard, and can settle with precision. It becomes less useful when a depositor’s needs exceed available network capacity, eligibility rules are not met, or the economics compare poorly with another source of funding. No network abolishes the insurance rules or the need for a bank to manage its own risk.
For the depositor, none of this should feel like an epic of financial engineering. That is the clever part. The most elaborate thing about ModernFi may be its insistence that a customer with a large balance should still be able to call the banker who knows their name.