The least glamorous software in a bank may be the most important. A core system keeps the ledger, posts deposits, calculates interest, tracks loans and makes sure a debit-card swipe becomes the right number in the right account. Nobody makes a celebratory video when it works. When it does not, people notice before breakfast.
That is the business COCC has occupied since 1967. From Southington, Connecticut, the company supplies the back-office engine and much of the digital storefront for community banks and credit unions. It processes the chores consumers rarely see, then layers on mobile banking, account opening, payments, analytics, document workflow, accounting, cybersecurity and network services. COCC says its technology now serves 175 financial institutions; its digital platform reaches more than 2 million users.
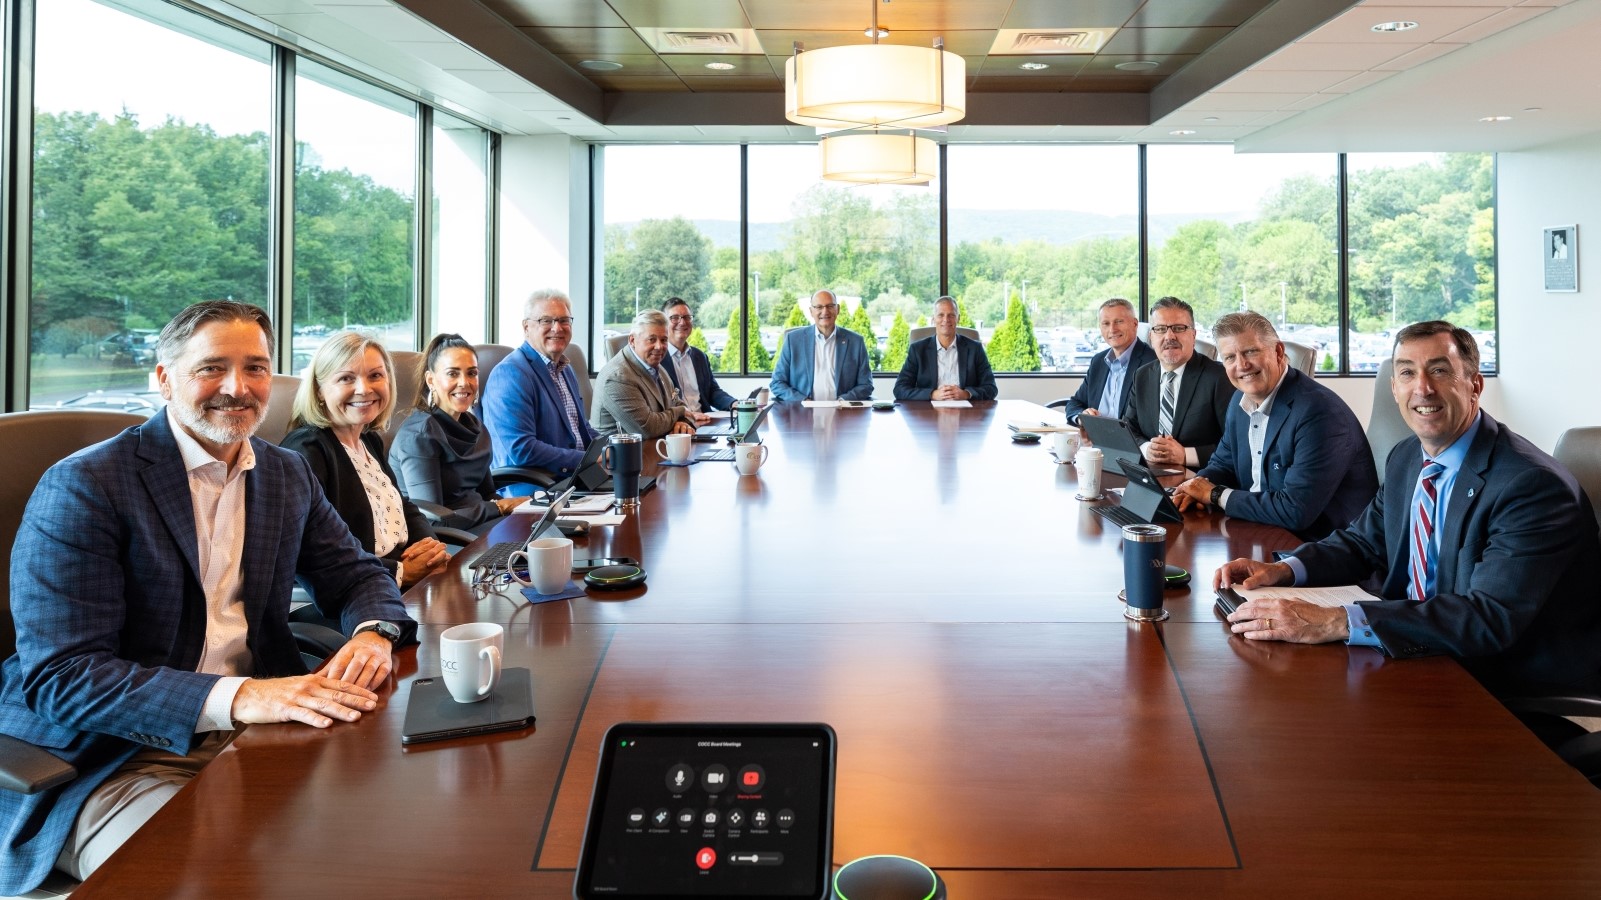
The software is consequential. The organizational chart is the real plot. COCC is a private cooperative, owned entirely by its client institutions. Client CEOs make up the board. Banks do not merely fill out feedback forms and wait for a product manager to notice. They have a formal seat at the table.
Fifteen banks, one expensive problem
COCC opened in Hartford with 15 institutions converting their deposit work to the shared operation. The founding complaint was plain: community banks wanted more control over the features, cost and delivery of the technology they depended on. Individually, none could justify building a modern processing company. Together, they could own one.
That is what changed their minds. The first failure was not a dramatic outage or a doomed app. It was the vendor relationship itself - the feeling that essential technology was being done to the banks rather than with them. The cooperative turned that frustration into governance. It pooled demand without asking each bank to surrender its local identity.
The price of that original move is not publicly itemized, and COCC still does not put a sticker price on its site. Core systems are sold through negotiated, multi-year contracts shaped by institution size, modules, transaction volumes, conversions and integrations. The more honest cost is larger than a license fee anyway. A bank changing cores must map decades of data, retest connections, retrain employees, communicate with customers and survive a launch in which every balance must land correctly.
A bank in a box - with doors
At the center is a real-time relational-database core. It handles deposits, loans, customer records and the accounting truth beneath every channel. Around it, COCC offers consumer and business digital banking; ACH, wires and cash management; card services; business intelligence; Oracle-based financial accounting; document management; managed security; and network infrastructure.
The important word is “around.” Banks have long complained that a core provider can become a tollbooth, controlling which outside products connect and how much the connection costs. COCC pitches open architecture, full client access to data and more than 100 APIs and integrations. Its ConnectSuite is meant to let an institution add specialist fintech products without replacing the foundation.
Recent partnerships make the strategy visible. Digital Onboarding helps banks keep engaging customers after an account is opened. AKUVO brings cloud-based collections and credit-risk workflows. LenderSquared supplies commercial-lending analysis, market intelligence and prospecting. COCC does not need to build every clever tool. It needs to make those tools behave like part of the bank.
National Iron Bank offers a useful before-and-after. When Steven Cornell arrived at the Connecticut bank, colleagues described accounting work built around manual routines and Excel sheets. The institution adopted COCC's Oracle accounting tools, including the general ledger, fixed assets, accounts payable and investment software. Over a relationship now measured in decades, the bank moved from what Cornell called “non-digital” operations to an almost entirely digital posture. The first thing to fail, in other words, was not the vault. It was the accumulation of ordinary workarounds.
That sequence matters because buyers can copy it. Do not begin a core decision with a gallery of mobile-app screens. Begin with the ledger, data ownership, integration rules and the staff time consumed by reconciliation. Then map the customer-facing changes those foundations make possible. A handsome interface sitting on delayed data is still an expensive costume.
Run the ledger in real time, offer branded web and mobile banking, open accounts remotely, move money through ACH and wires, spot profitable relationships in dashboards, automate document-heavy work and call on COCC for round-the-clock digital support and managed security.
The small alternative in a giant's market
COCC is not the dominant American core provider. Fiserv, Jack Henry and FIS collectively served more than 70 percent of banks surveyed in 2022, according to research from the Federal Reserve Bank of Kansas City. COCC accounted for about 3 percent. CSI, Finastra and credit-union specialists fill more of the field, while newer API-first companies promise cleaner technology and faster launches.
Selected provider share among surveyed banks, 2022
Being smaller is useful only when it produces a different experience. COCC's clients are concentrated in the Northeast and range from roughly $10 million to more than $7 billion in assets. The company can sell local access and a single-core focus instead of a global catalog. Richard Leone, who joined as CFO in 1991 and became CEO in 2002, has argued that proximity matters: support staff can reach most clients quickly, and executives remain accessible.
The business model resembles enterprise software more than a bank cooperative's annual dues. Institutions sign contracts for processing and choose additional services; implementation, support and integration become part of the relationship. Because COCC is privately held and publishes annual reports without full financial statements, outsiders cannot neatly separate license revenue from processing or services. The supplied company estimate of roughly $177 million in annual revenue is best treated as directional, not audited public disclosure. What is clear is the economic loop: client spending funds a company the clients collectively own, and the resulting platform is shared across institutions that would struggle to build it alone.
There is evidence that the pitch lands. In the American Bankers Association's 2024 survey, COCC reported an overall satisfaction rating of 4.03 out of 5, the highest of the providers shown, against an industry average of 3.19. COCC also says it retained every core client in 2024, renewing 20 relationships and adding four. Average client tenure was 17 years, with the longest relationship at 57.
Those numbers deserve two readings. Service and shared ownership may be working. Core software is also famously sticky. ABA found that 69 percent of bankers expected to stay with their provider at renewal even while satisfaction across the market remained modest. Loyalty can be affection, switching pain, or both. COCC's stronger argument is that its customers report satisfaction while staying.
The copyable part is not the code
A founder cannot copy COCC by adding the word “community” to a landing page. The useful lesson is to match governance to switching cost. When customers must make a long, risky commitment, give them meaningful influence over the roadmap, service rules and economics. That can turn an abstract promise of alignment into an operating mechanism.
The model has limits. It works best when members have compatible needs, long planning horizons and enough trust to fund shared infrastructure. It is a poor fit when customers want radically different products, when speed matters more than consensus, or when one giant client can dominate the rest. Cooperative governance can align incentives; it can also create committees, cautious roadmaps and pressure to satisfy yesterday's requirements.
COCC's own history is a long negotiation with that risk. It moved from deposit processing to real-time accounts in the 1970s, migrated every client to an open core in 2003, added apps and analytics, then built a digital layer with millions of users. During the 2020 pandemic, virtual networks moved employees home while processing continued. This was modernization by accumulation, not a clean-sheet rebellion.
That is also where COCC fits in the market. It is neither a consumer fintech nor a shiny middleware startup. It is the regulated plumbing, digital storefront and support desk for institutions that want modern capability without becoming software companies themselves. Its latest signings - United Roosevelt Savings Bank, MCS Bank and Citizens Federal Savings & Loan Association - all describe some version of the same need: preserve community-banking service while replacing the technology underneath it.
Consumers may never know COCC's name, which is probably a compliment. The balance appears, the wire leaves, the mobile deposit lands and the local bank keeps its own sign over the door. Beneath that quiet transaction is an unusual bargain: the customer bought software, then became one of the people the software company must answer to.
Continue exploring