The dressmaker had a business. She had customers. She knew what to make and how to sell it. What she lacked was enough money to stop buying her materials one exhausting journey at a time. Michael Schlein remembers meeting her in Brazil: hours spent traveling for fabric, then dresses made and sold to support her children. A $300 loan let her buy two weeks of supplies in one go. Half her day became available for work. She made more dresses and started selling materials to other women.
For the president and CEO of Accion, this is a compact explanation of a large problem. The woman’s working day had been arranged around a shortage of capital. Give her access to a modest amount, and the same skills could produce more. A loan had purchased something that rarely appears on a bank statement: an afternoon.
Schlein still tells the story years into a career that has taken him through investment banking, City Hall, financial regulation, and international bank management. His current work involves funds, financial technology, and institutions operating across continents. The dressmaker supplies a useful scale for all that machinery. Can it make someone’s ordinary working life less difficult?
Enough to buy two weeks of fabric.
Enough to free half a working day.
A résumé with several kinds of money
Schlein’s education combined economics and political science at MIT, where he earned undergraduate and graduate degrees and graduated Phi Beta Kappa. The pairing fits a career spent around markets and the institutions that govern them. He began at Smith Barney, working with municipal governments on access to capital markets.
Public service followed. From 1989 to 1993, he was chief of staff to New York City’s deputy mayor for finance and economic development. He then served as chief of staff to SEC chairman Arthur Levitt from 1994 to 1997. Borrowing for a city, administering its economic agenda, and overseeing securities markets offered different views of how money moves and who sets its terms.
He returned to Smith Barney in 1997, working for Jamie Dimon. The mergers that created Citigroup brought a much larger institution into the story. Schlein’s responsibilities there included communications, philanthropy, government relations, branding, and human resources. As president of international franchise management, he managed the bank’s network of 100 chief country officers.
Those jobs gave him experience with both corporate organization and public institutions. At Accion, both would matter. A useful financial product needs an organization capable of delivering it, and rules under which customers can rely on it. The résumé has plenty of impressive nouns. The harder part is making the verbs work.
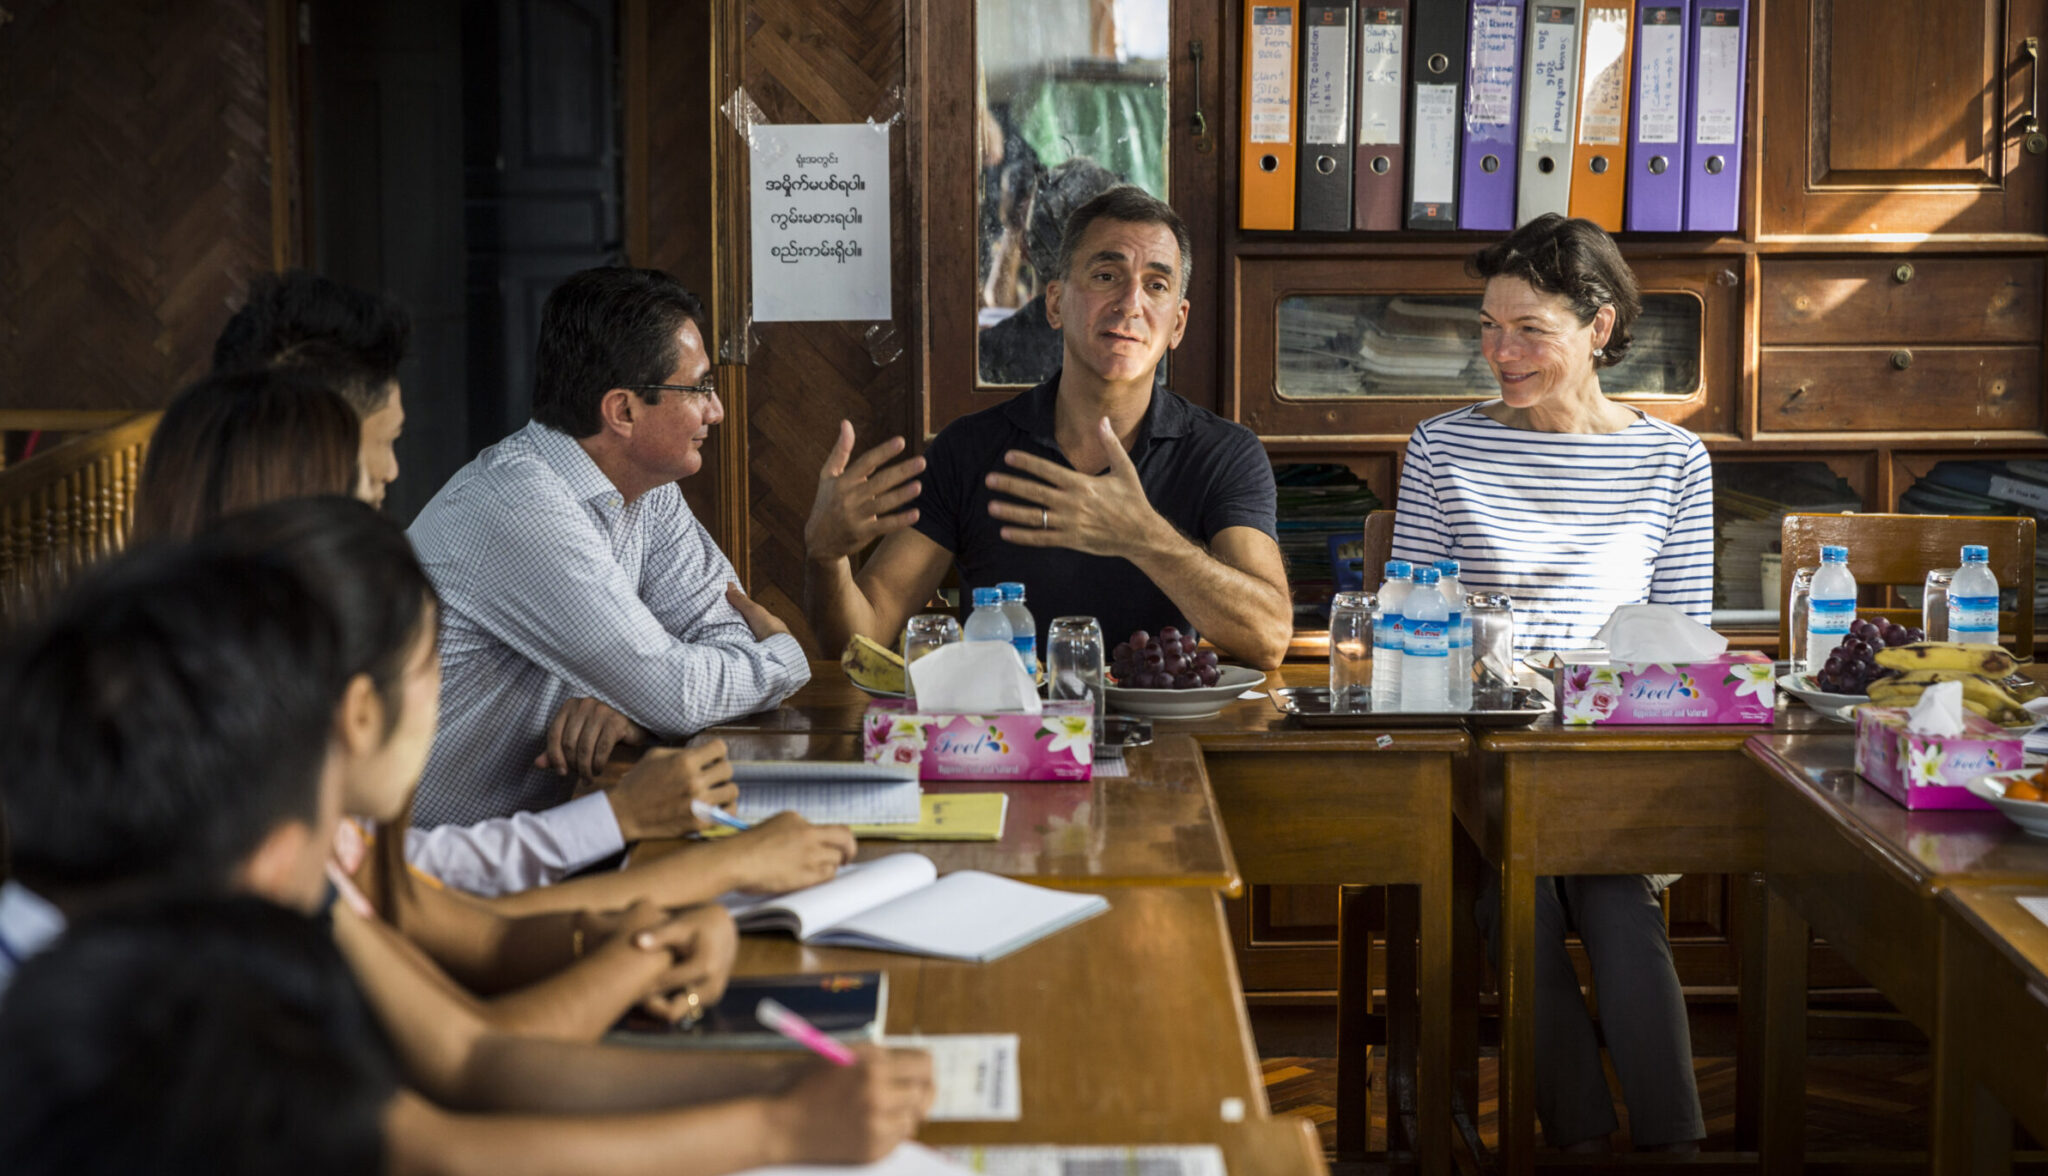
The route from Citi to a $300 problem
Work with the Citi Foundation drew Schlein toward microfinance and Accion. He joined Accion’s board in 2007 and became president and CEO in 2009, following Maria Otero’s departure. The move placed his banking experience inside a nonprofit with a long history of working with people commercial finance had overlooked.
Accion’s beginnings predated him by decades. Founded in 1961, it initially worked on community development in Latin America. In the early 1970s, small loans to entrepreneurs in Recife, Brazil, helped establish the case that low-income customers could be served by financial institutions. Later came support for locally led microfinance institutions and the conversion of nonprofit lenders into regulated financial institutions.
By Schlein’s tenure, the possibilities were widening. Mobile phones, digital payments, and new ways of analyzing information offered routes to customers who had been expensive or difficult to reach. Accion expanded its focus toward inclusive fintech and the modernization of existing providers.
Schlein has described the job as a culmination of his earlier work. In 2014, he put it plainly: “I’ve spent my whole life preparing for this job.” Preparation, in this case, included learning the financial system from several seats before asking it to make room for more people.
The city stays in the picture
His international work did not end his involvement in New York. In 2014, Mayor Bill de Blasio appointed him chair of the New York City Economic Development Corporation’s board. Schlein and de Blasio had worked together in the Dinkins administration. The appointment brought him back to the question of how economic policy reaches a city’s neighborhoods. He remained chair until January 2021.
The American small business connection has continued. He joined the board of the organization now known as Accion Opportunity Fund in 2020, following the combination of Opportunity Fund and the Accion U.S. Network. In August 2025, he was appointed its board chair.
That work gives the international mission a domestic counterpart. The geography changes; the need for affordable capital remains recognizable. A business owner must finance stock, manage uneven cash flows, and plan for the next month. Financial exclusion has no obligation to stay conveniently overseas.
Two funds, two routes to the customer
Schlein’s argument for scale involves commercial investment as well as philanthropic support. In a 2020 conversation, he said: “The only way to do it is to harness the capital market.” His point was that charitable resources alone could not meet the scale of global financial exclusion.
The approach can be seen in two separate fund announcements. In May 2024, Accion launched a $152.5 million Digital Transformation Fund, managed by Accion Impact Management. It provides growth capital and strategic support to financial institutions serving small businesses. Initial investments included Annapurna Finance and IKF Finance in India.
A different fund, focused on early-stage inclusive fintech, closed at $61.6 million in September 2025. The announcement also marked the change of name from Accion Venture Lab to Accion Ventures. The strategy began in 2012; by the 2025 announcement, it had invested in 76 companies across more than 30 countries.
One route supports emerging companies with new models. The other helps established institutions change the way they work. Both depend on teams, local knowledge, and execution. These are organizational efforts under Schlein’s leadership, with dedicated investment managers doing the investing. A CEO’s name may sit beside the announcement; the work has many authors.
Announced fund sizes. Capital supports providers and startups; these figures are not direct client loans or personal assets.
The customers a spreadsheet misses
At Web Summit Rio in 2024, Schlein described how embedded finance could reach small shops through the networks and platforms they already use. A supplier or commerce platform can hold information about what a business buys and sells. That record may help a lender understand an enterprise that lacks a conventional financial history.
The appeal is practical. A shopkeeper need not become familiar with every institution in the financial system before its daily activity can count. Services can arrive through an existing business relationship. The transaction trail begins to describe work that was already happening.
Schlein’s enthusiasm for data has conditions. In his 2023 writing on AI, he discussed sources such as utility payments, phone activity, and satellite images. He also asked whether data represents underserved groups, whether outcomes are fair, and whether teams understand algorithmic bias. His example of Apollo Agriculture in Kenya showed how satellite data could support farm financing and insurance.
Better analysis can widen access. Biased analysis can repeat exclusion at greater speed. Schlein places responsibility with the investors and leaders deciding which tools receive backing. A model that overlooks its intended customer has made a rather expensive mistake, however elegant the software.
“And I would love for that to be Ethiopia.”
Michael Schlein, on his hope for an influential African example of financial inclusion, May 2025
The plumbing deserves a little attention
Some of Schlein’s public writing concerns infrastructure: trusted identification, fast payments, and secure data exchange. These are the foundations that let financial providers build services people can reach. They are unlikely to steal the show at a product launch. They still determine whether the product works.
In 2023, he pointed to digital public infrastructure as a way to expand economic opportunity while warning about privacy, surveillance, and the costs passed to consumers. A government-led system needs safeguards. A public-private partnership needs them too. Internet and device access remain part of the problem.
His 2024 response to the UN’s Global Digital Compact emphasized the financial history created by digital payments. A transaction can do more than move money: it can help build a record that supports other services. He discussed Brazil’s Pix and India’s UPI as examples, while stressing that countries need approaches suited to their own people.
This is where his public service background becomes relevant to his present argument. Individual companies need shared systems, and shared systems need rules. The customer ultimately experiences all of it as a payment that goes through, a service they understand, or a problem they can get resolved.
Back at the clothing counter
In 2025, Schlein traveled to Ethiopia with Accion board members and donors. They visited Mohammed Side, owner of the Amazing Style clothing store in Addis Ababa. Working capital from Accion partner Dashen Bank had helped Side buy inventory, hire employees, and expand his business.
The visit brought the discussion back to garments, shelves, and the gap between paying for stock and selling it. Schlein wrote about Side’s energy and how much the business meant to his family. Dashen’s work with Accion and the Mastercard Center for Inclusive Growth included developing new credit-scoring models to reach more small businesses, especially those run by women.
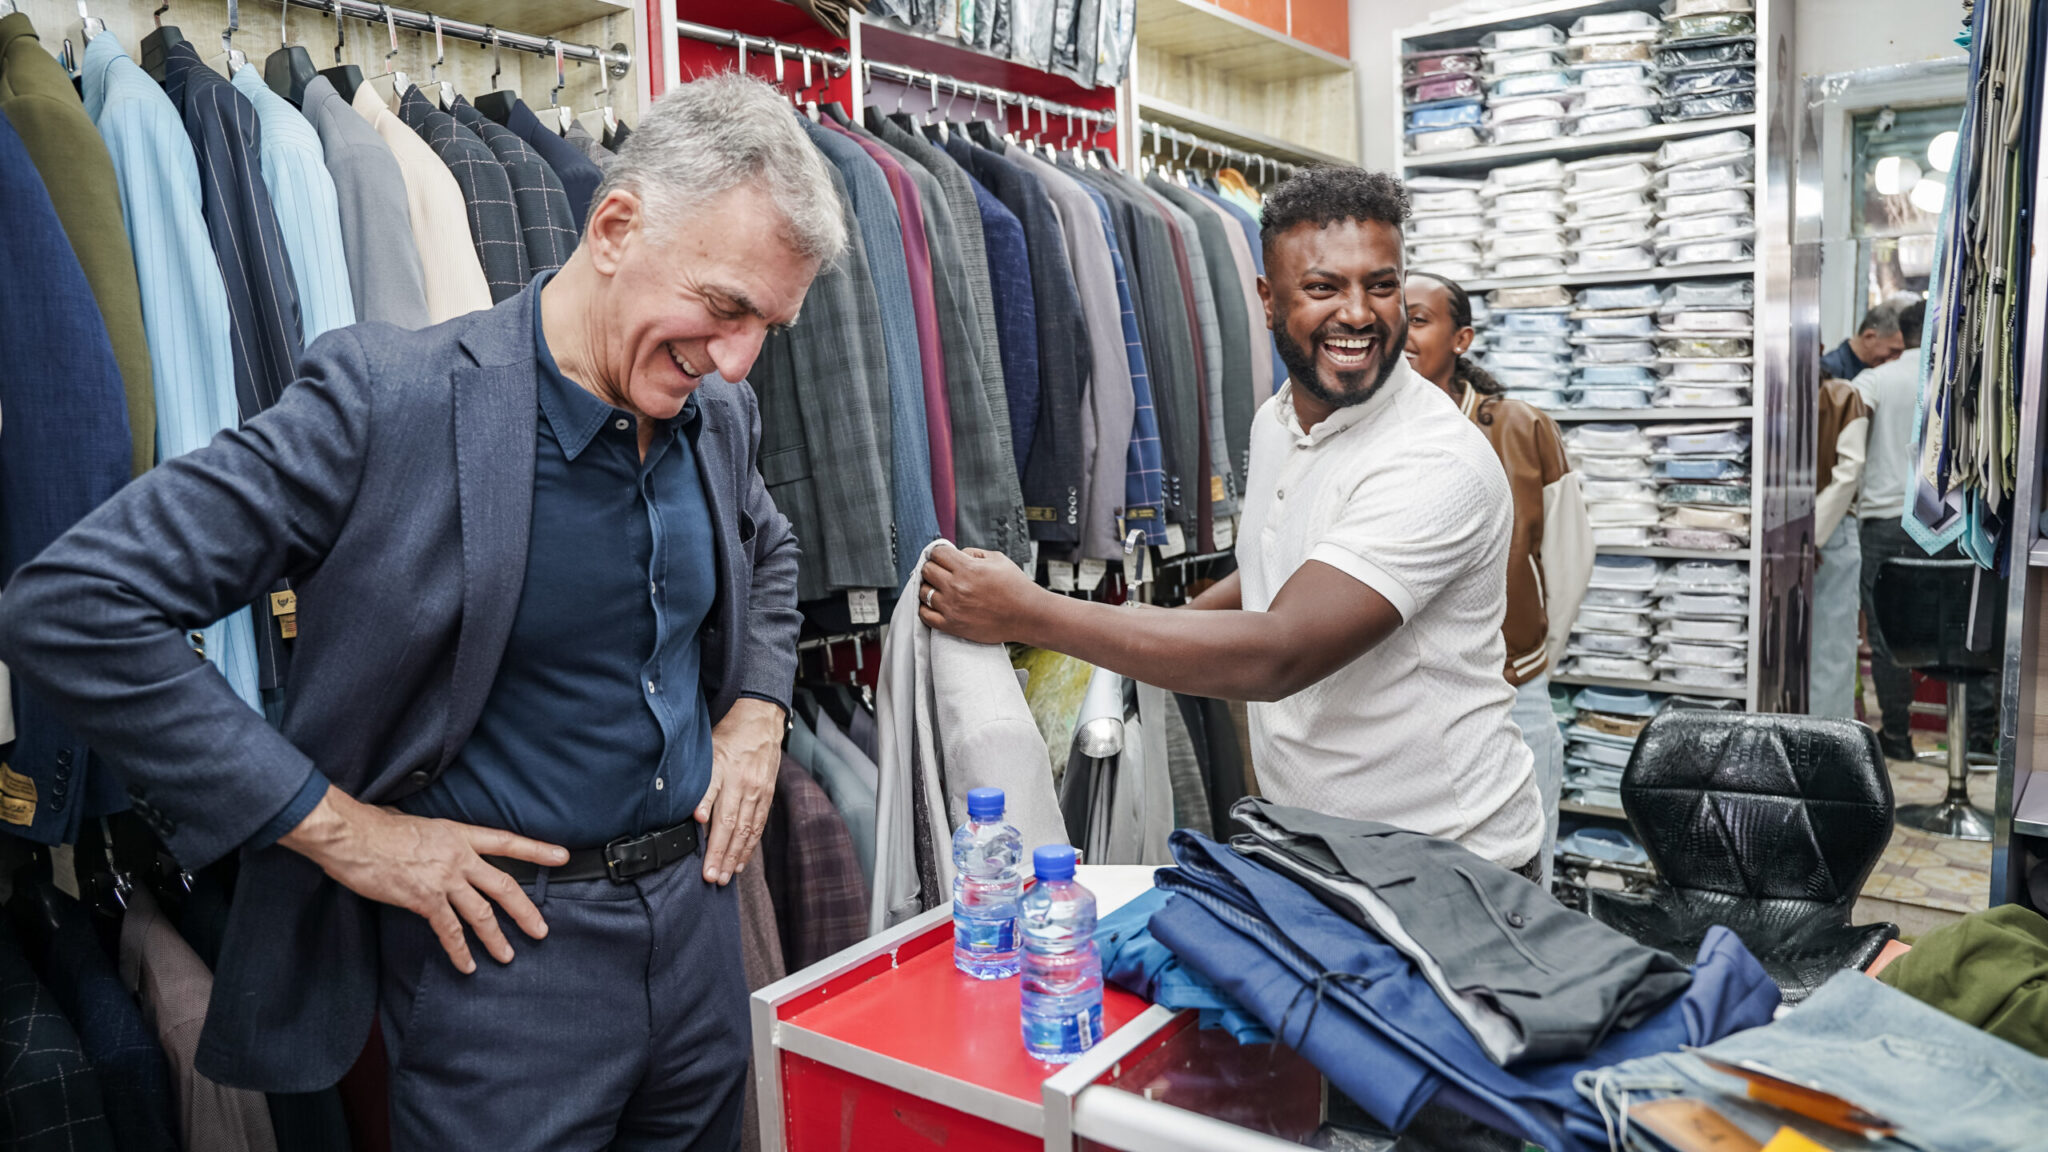
Earlier that year, Schlein had expressed a particular hope for Ethiopia: that it could become an African example of financial inclusion with the influence of India or Brazil. The ambition was about a country and its institutions, rather than a single application.
He also has room for limits. In a 2018 discussion of the American dream, he argued that impact investing could help, while broader economic and policy changes were necessary. In April 2026, marking Accion’s 65th anniversary, his emphasis was on services that are affordable, trusted, and responsible. Account access alone was insufficient.
That leaves a demanding measure for the next chapter. A provider can count accounts, investments, and transactions. The dressmaker would have had another calculation: how much of the day remained for making dresses. Schlein’s work sits between those ledgers. The afternoon still matters.