Michael Chu studied psychology and economics. Put the two subjects together and you have a useful preparation for a career spent asking why somebody will pay for one object, ignore another, and return next week for more. Economics accounts for the transaction. Psychology gets a vote on what goes into the shopping bag. Chu has spent much of his working life in the space between them.
In 1989, he co-founded the investment firm that became L Catterton. Its chosen territory was consumer businesses: companies whose prospects depend on the judgments people make at restaurant tables, in shops, and, increasingly, on screens. That gives the investor a peculiar assignment. A spreadsheet must eventually reconcile with a person who is hungry, distracted, delighted, price-conscious, or simply in the mood for something different.
Chu is now the firm’s executive chairman and co-founder. The change from his former global co-CEO role arrived in 2025. Scott Dahnke became global CEO. The succession places Chu in a different seat at an institution he has helped build across decades, while keeping him attached to its central subject: the consumer, that wonderfully uncooperative participant in every business plan.
Two subjects, several countries
His education began this part of the story in Lewiston, Maine. Chu graduated from Bates College in 1980, earning a bachelor’s degree in psychology and economics with highest honors. The combination is conspicuous in retrospect. One discipline examines behavior; the other examines choices under constraints. A consumer company lives with both, whether its founders have read the textbooks or not.
In 1983 he joined First Pacific, a Hong Kong-based investment and management company. His responsibilities took him well beyond a single financial specialty. He served as vice president and corporate treasurer at First Pacific in Hong Kong, finance director at Hagemeyer in the Netherlands, and vice president and treasurer at Hibernia Bank in San Francisco. New York roles included chief operating officer at Comtrad and at the advertising firm Doyle Graf Raj.
The geography is striking, but so is the range of work. Treasury, banking, finance, operations, advertising: each examines a business through a different window. Advertising asks what can persuade a customer. Operations asks whether the company can deliver. Finance asks what delivery costs. These responsibilities provide a concrete backdrop to Chu’s later consumer focus without requiring a tidy origin myth about a single revelatory afternoon.
Six years after joining First Pacific, he helped establish Catterton. He would co-lead the firm from 2003. There is a considerable distance between founding an investment partnership and sustaining an organization long enough for its own leadership to evolve. Chu’s career covers both tasks. The continuity lies in the subject matter, while the geography, partners, and financial instruments have expanded around it.
The consumer before the company
L Catterton describes its method as category-first. The sequence matters. It starts with changes in consumer preferences and then looks for the categories and businesses positioned to benefit. Demographics, technology, geography, and social and economic circumstances all enter the inquiry. A recognizable name is therefore one part of a much larger question about how people are living and spending.
This approach makes the supermarket aisle and the luxury boutique related research sites. Their prices differ considerably; both require someone to choose. For a consumer investor, the interesting question is how a business turns that choice into a relationship durable enough to support expansion. The firm explicitly emphasizes emotional connections and repeat relationships in its account of how it builds brands.
There is a practical tension here. Familiarity can encourage a purchase, but it can also conceal how much a company needs to change. An investor has to respect what customers recognize while examining the machinery behind it. Shops, distribution, product development, and management all have to keep pace. The affection may belong to the customer; the work of keeping the promise belongs to the business.
That work was visible in Catterton’s 2012 investment in Baccarat. Chu and Neda Daneshzadeh joined the crystal company’s board when the investment completed. Chu emphasized the contribution Catterton could make through brand, retail, and operating experience, with international development in view. Crystal is an unusually literal illustration of the problem: a brand’s appeal may be delicate, while the organization supporting it must be sturdy.
A French connection, without changing the question
The firm’s international ambitions took a consequential turn in January 2016. Catterton, LVMH, and Groupe Arnault announced the agreement creating L Catterton. The combination brought Catterton together with L Capital and L Real Estate. Chu and Dahnke were named global co-CEOs of the resulting business, which would have headquarters in Greenwich and London.
The announcement anticipated assets under management exceeding $12 billion after successor funds closed. Its network comprised more than 120 investment and operating professionals in 17 offices across five continents. Those figures described an intended global platform, with dedicated local teams continuing to manage their funds. Local knowledge remained part of the design, even as the map became much larger.
Bernard Arnault brought the perspective of LVMH and his family holding company to the partnership. For Chu, this joined an established consumer investment practice to a network associated with luxury and international brand development. The appeal of that arrangement is easy to understand. A company crossing a border encounters new customers, distribution systems, and expectations. Capital buys an introduction; experience helps with the conversation that follows.
Asia has remained part of Chu’s public discussion of consumers. In January 2018, he spoke with interviewer Sophia Yan in New York about China’s transition toward consumer-led services and the opportunities surrounding its middle-class market. The setting was the NEXT CHINA conference. It was a discussion about changing demand, rather than a tour of a portfolio.
In March 2024, L Catterton Asia announced an India-focused joint venture with former Hindustan Unilever leader Sanjiv Mehta. Chu connected the initiative to India’s population and economic growth, pairing Mehta’s consumer experience with the firm’s investment and operating approach. The partnership put a named operator alongside the investment thesis. Understanding a market becomes more useful when somebody also knows how to run businesses inside it.
What a sandal asks of its chairman
Chu also chairs Birkenstock’s board. The assignment brings the discussion of enduring brands down to something people actually wear. A board’s work concerns oversight, strategy, and accountability, while a customer encounters the finished product. The distance between those two experiences is where much of the work of consumer investing happens.
In his March 2026 letter to shareholders, Chu reported Birkenstock’s fiscal 2025 revenue of €2.1 billion, up 16%. He described a distribution approach combining wholesale relationships, owned retail, and digital capabilities. He also identified Gen Z as the brand’s fastest-growing awareness group. An old brand still has to make itself familiar to people encountering it for the first time.
These are company results, with a management team and workforce behind them. Their relevance to Chu’s story is the nature of the questions they raise. How should a familiar product reach new buyers? Which channels support that growth? How does a company add scale while preserving the reasons customers sought it out? Chairing the board puts those questions on an institutional agenda.
The pie has its own timetable
In a September 2026 conversation with Louisa Qiu, Chu used a domestic analogy for investing in luxury: “It’s like baking a pie.” Patience, in this account, belongs to the process. Raising the temperature cannot simply hurry the result. For an industry accustomed to discussing growth targets, the kitchen supplies an inconveniently sensible clock.
“It’s like baking a pie.”
Michael Chu, on luxury investing · September 2026
He discussed the difference between social-media attention and lasting brand value, pointing to loyalty, pricing power, margins, and the ability to extend a brand into other categories. A sudden audience gives a company an opening. What customers do afterward determines whether that opening becomes a business with staying power.
The analogy is appealing because it gives time a job. Waiting alone achieves very little; a pie left on the counter remains an unfinished assignment. The process needs ingredients, judgment, and the right conditions. Read alongside Chu’s career, the comparison suggests a useful way to understand consumer investing: money can support the work, while the relationship with the customer develops through experience.
A return address in Maine
For a more personal example of returning, there is Bates. Chu served on its board of trustees from 1995 to 2013. He and Elizabeth Kalperis Chu met at the college; their elder son, Christopher, graduated in 2012. In 2016, the couple committed $10 million, and two new residence halls were named Kalperis Hall and Chu Hall.
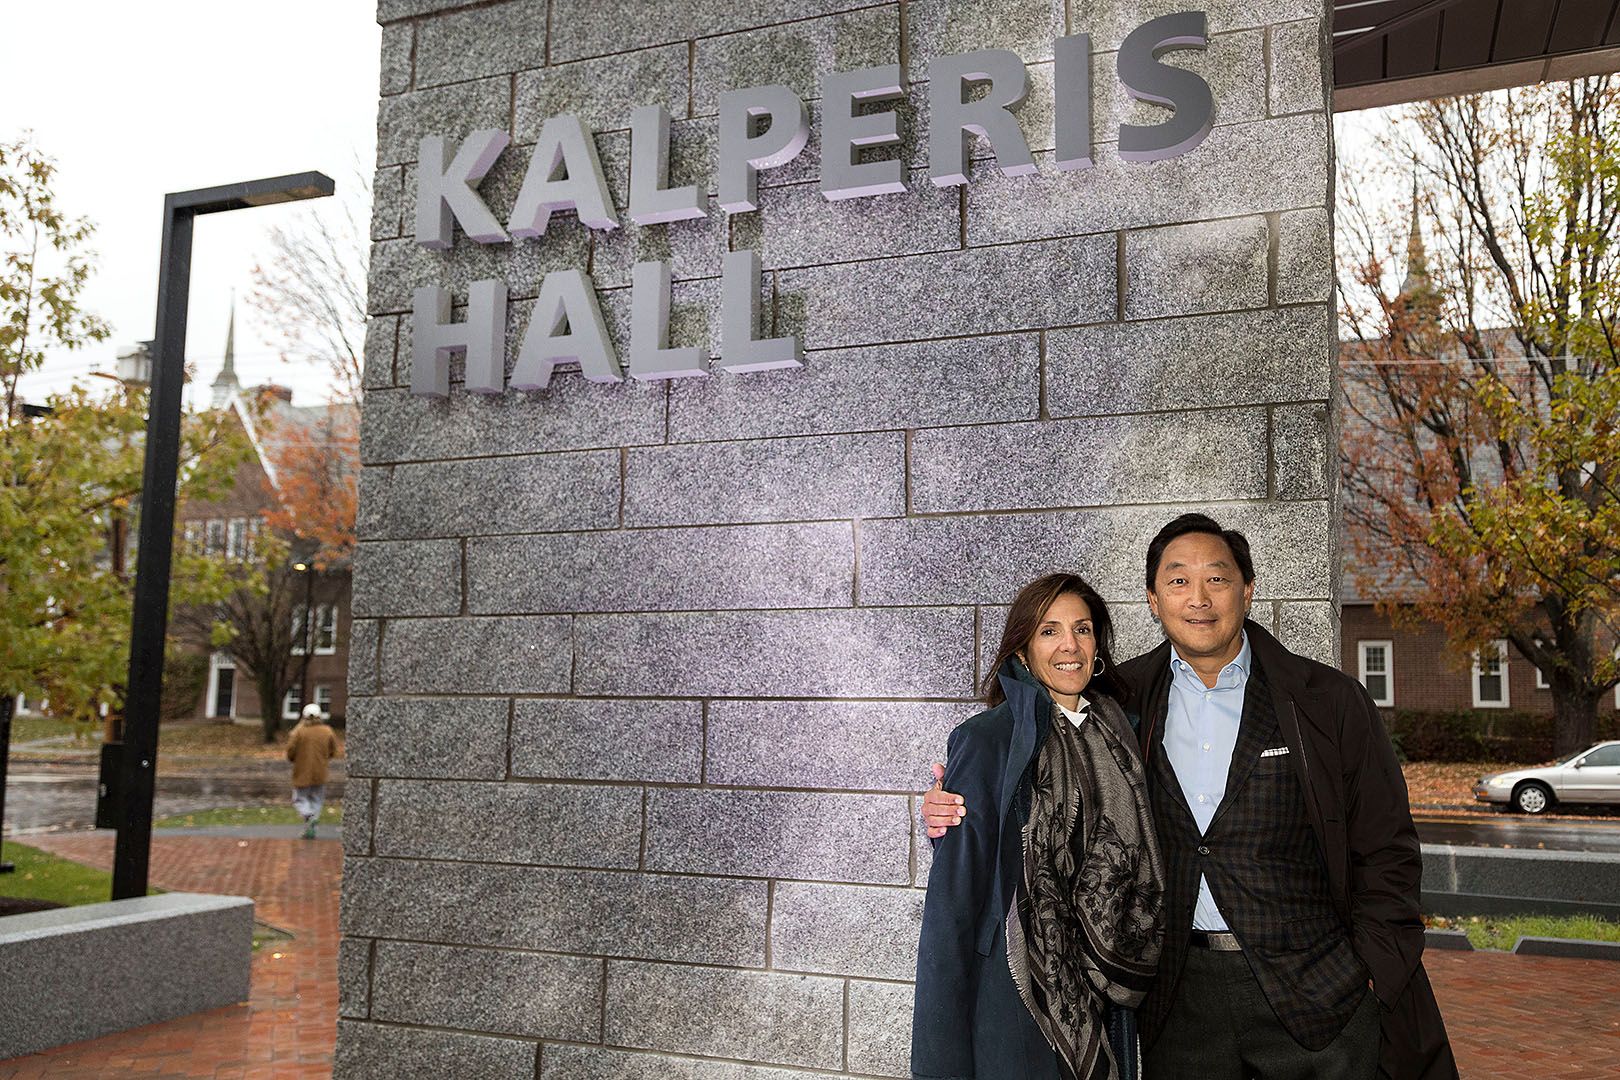
The scene is a pleasing change of scale: a couple beside a college building, rather than an executive beside a transaction announcement. Their joint statement described the education and friendships Bates had given them. “Bates gave both of us a remarkable education,” they said. The attachment had lasted long enough to include a second generation.
There is no need to convert that gift into an investment lesson. A college friendship and a consumer purchase have different meanings. But the return to Lewiston provides a human counterweight to the international career. Chu’s professional map stretches across markets; this particular connection has an address, a shared history, and buildings where other students can begin their own stories.
His public record contains plenty of large numbers. In May 2025, L Catterton announced approximately $11 billion in commitments across its latest fundraising cycle, including more than $6.75 billion for its flagship buyout strategy. Yet the more interesting thread in Chu’s career is the patient attention required by his chosen subject. People can be reached quickly. Giving them a reason to return remains a much longer assignment.