Michael Broughton was $10,000 short of his university tuition when he encountered an awkward feature of American finance: a person can need credit in order to get credit. He wanted a loan. Lenders wanted a history. The history, inconveniently, was something he had yet to be allowed to acquire. A promising college admission had come with an unadvertised entrance examination.
The rejection became a problem he kept working on. With fellow USC student Ayush Jain, Broughton eventually co-founded Altro, a business designed to help people establish credit through payments already woven into their lives. The idea had the appeal of a sensible question asked in a room accustomed to more complicated answers: if someone pays a recurring bill, why should that evidence go to waste?
A bill with no biography
Broughton grew up in South Korea and Japan in a military family before moving to South Dakota. Returning to the United States meant learning a financial system whose expectations were hardly self-explanatory. He has described asking about a credit card and encountering the same demand for an existing score. Every entrance appeared to require a ticket sold somewhere inside.
His account of the tuition gap is specific. His family could not provide the guarantee he needed, and the missing $10,000 threatened his route through USC. The experience gave his later work a particular audience: people trying to begin, whose lack of a financial record could be mistaken for a reason to keep them waiting.
That distinction matters to his story. He had arrived with an educational ambition and discovered a second curriculum. Understanding the machinery around an opportunity could take as much determination as pursuing the opportunity itself.
A seat on the other side of the table
By 2017, Broughton had been elected to USC Credit Union’s board. He later became vice chairman, helping guide a cooperative owned by its members. The student frustrated by financial institutions was learning how one worked from inside the boardroom. It was an unusually direct way to continue an argument.
Campus support also mattered. Through Blackstone LaunchPad, he connected with the credit union’s leadership and investigated the obstacles facing students seeking credit. An early version of the business appeared as Hatch Credit. A team drawn from USC brought different family experiences to a problem they understood personally.
There was useful friction between those settings: the classroom, the boardroom, the early company. Each asked him to explain the same difficulty in a different language. A student needed a practical answer. A financial institution needed to understand risk. A founder had to find something that could actually be built.
The tuition shortfall behind Broughton’s search for another way into credit.
Let the ordinary payments count
Altro’s later product description made the mechanism concrete: a $75 credit line for subscriptions people were already paying for. The line could cover services such as Netflix or Hulu, and payment activity could become part of a credit record. A modest recurring expense acquired a second job.
The distinction between a subscription and a credit product deserves attention. Watching television was never the accomplishment being measured. The relevant activity was paying the bill through a structure that could report it. The entertainment stayed entertainment; the payment gained an audience among the credit bureaus.
For Broughton, the attraction was a way to begin with familiar behaviour. Someone should not have to invent an entirely new financial life merely to make an existing one legible. The company’s early work also considered rent and other recurring payments, keeping that basic question of recognition at the centre.
A house, a cohort, a cheque
The business that became Altro was founded in 2019 and joined Y Combinator’s summer 2020 batch. During its Perch Credit period, it announced a $2.5 million seed round with investors including Marcy Venture Partners, Citigroup, SoftBank’s opportunity fund and Concrete Rose Capital. Financial education sat alongside the credit-building proposition.
There was also the less glamorous address: a hacker house. Broughton has said he spent two years living in one while building the company. Sharing a roof with a startup is an efficient arrangement, provided one accepts that the startup has rather expansive views about visiting hours.
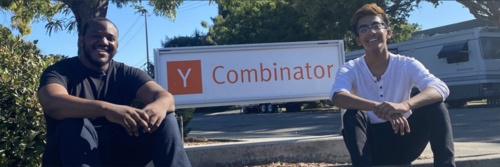
Recognition followed. Broughton became a 2020 Thiel Fellow. Altro announced an $18 million Series A in 2022, and Forbes selected him for its 2023 Consumer Technology 30 Under 30 list. His former university’s credit union celebrated the selection while pointing to his continuing board service. The institution and the young company had become overlapping parts of his working life.
The CEO on the telephone
One revealing detail from the Altro years involves the telephone. Broughton described calling members directly to learn how the app was working. He tried to ring after work hours, when people with ordinary jobs might actually have time to answer. The chief executive’s schedule accommodated the customer’s.
He also described deliberately onboarding people individually when introducing products. That approach put understanding ahead of the convenience of a crowded download chart. A financial tool had to make sense to the person using it, especially when that person was already navigating an unfamiliar system.
The same instinct appeared in Altro’s community experiments. Broughton later recalled COMMAS, a format for candid discussions about money and credit, which evolved into CONVOS. He credited relationships with community leaders and trusted voices as a growth driver. A conversation gave people room to explain what an account screen could only hint at.
His most interesting operating habit was therefore quite ordinary: ask, then stay for the answer. A company built around people being overlooked had reason to be careful about overlooking them itself.
The expensive education
Broughton’s account of the company’s exit includes a detail that resists the smoothness of a success story. He said Altro’s bank balance had been negative before the $18 million Series A closed. The large funding number and the precarious balance belonged to the same business. Announcements tend to give them separate rooms.
“Owning your future is far more fun than chasing valuations.”
Michael Broughton, reflecting on Altro’s exit
He has also spoken about repeated pivots and about hiring people whose backgrounds conventional employers might have dismissed, including former baristas and college dropouts. The account makes entrepreneurship feel like a series of decisions involving actual people, with all the obligations that follow.
Altro was acquired; Broughton’s personal site dates the acquisition to 2024. The founders’ farewell letter thanks customers, colleagues and investors, and recalls the early rent-reporting work. The chapter closes with a company that had travelled a considerable distance from a student’s tuition problem.
His reflections on what came next are pointed. He has criticised spending too much time in public and too little with committed users. He wants a smaller core team and quicker decisions. The lesson is expensive precisely because he can attach experience to it. General advice is abundant; a founder explaining which habits he intends to change is more useful.
- 2017Elected to USC Credit Union’s board
- 2019The business that became Altro begins
- 2020YC Summer batch and Thiel Fellowship
- 2022$18 million Series A announced
- 2024Acquisition dated on his personal site
A first sale in a pink stockroom
Broughton’s current venture is Growth Sync, which works on turning social interactions into commercial conversations. Its tools help brands deal with comments, story replies and direct messages: product questions, purchase interest and the moment a customer needs a human response. The setting has moved from a credit application to a social inbox.
His account of the first sale brings the work back to physical space. He and Roderick Henley II spent weeks in a client’s stockroom. When the sale came, they celebrated and took a Polaroid. He remembers the room as pink. For all the vocabulary surrounding social commerce, the beginning involved being close enough to a customer’s business to understand it.
In a separate reflection on his next company, Broughton said the business had bootstrapped to profitability and described a revenue target. The target was a forecast, but the change in emphasis was clear. He wanted money coming from customers and capital used to expand something already working. A sale had become a particularly persuasive form of encouragement.
Proof, please
His August 2026 essay, Multiplayer AI Framework, offers another view of that preference for evidence. It sets out five skills for researching, planning, building and checking software with AI agents. The handoffs depend on inspectable files and records of work actually performed. A human remains responsible for the decisions.
The essay separates producing a change from independently checking it. It is a practical concern, and an apt one for someone whose next business uses software to speak with customers. Confidence should survive inspection. A convincing account of progress needs something behind it that another person can examine.
Broughton also invests in other founders, listing interests that include financial mobility, commerce and quantum computing. His portfolio reaches across several kinds of business. The curiosity has widened, while the original attraction remains recognisable: find a process that leaves something useful unseen, then work out how to make it count.
He began with a bill he could not finance and an application that could not accommodate his circumstances. He now has a different company, a set of operating lessons and a public insistence on checking the work. The ambition has acquired experience. Happily, experience is one kind of history he no longer has to ask permission to establish.