James Garvey thought his credit card was on autopay. He and his wife were travelling in Argentina when he discovered it wasn’t. The missed payments damaged his credit, and an ordinary administrative mistake acquired the sort of afterlife usually reserved for a scandal. A bill can be settled rather quickly. A credit record prefers to keep the conversation going.
Garvey began investigating how to repair the damage. Secured credit cards were one route, but they commonly required money upfront. For someone who could spare a deposit, that was an inconvenience. For someone who couldn’t, it was a locked door with excellent instructions for opening it. He found credit unions using loans backed by deposits and began considering a different sequence: could the loan itself supply the money to be held as security?
That question became Self. It also gave Garvey a problem substantial enough to hold his attention for years. He had arrived as a customer who had made a mistake, rather than as a banker with a new distribution plan. His starting point mattered: the system was familiar to its operators and thoroughly puzzling to the person standing outside it.
Before the credit file
Garvey’s working education began in software. Around the dot-com boom, he worked for a startup while paying his way through college. He studied mathematics at the University of California, Davis, graduating with a bachelor’s degree. Code, customers and the practical matter of earning tuition were already sharing the timetable.
In 2005, he and a partner started Objective Loyalty, an email marketing business. They grew it to $2.5 million in earnings before interest, taxes, depreciation and amortization. Selling it proved less straightforward. An investment banker spent six months seeking a buyer without producing an offer. Garvey changed the approach, contacting strategic partners who already understood the company. An offer followed; negotiation increased it.
It is an instructive episode in a career often introduced through Self. Garvey had experience building and selling a business before he tried to work with banks. He understood direct marketing and software. Financial services demanded another education. His later account of starting Self is unusually candid about that gap: he had an idea and technical skills, but needed people who knew what he did not.
Applause was not a banking partner
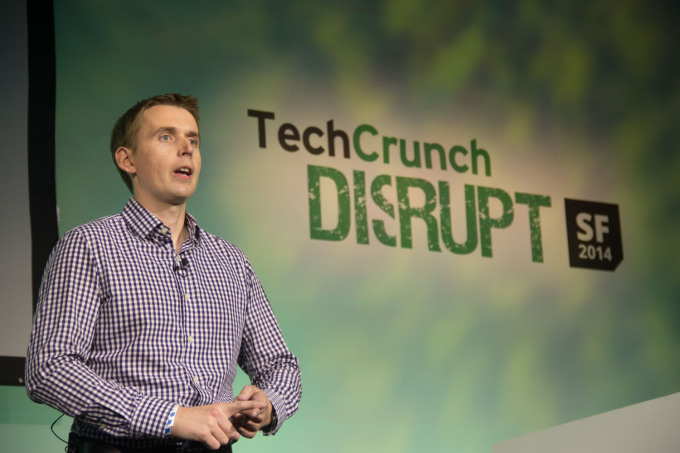
Self’s prototype reached TechCrunch Disrupt in September 2014. Getting onto the stage brought encouragement, but encouragement could neither issue a loan nor report a payment. Garvey needed a banking partner. Conversations with large banks went nowhere, and an early partnership within the founding team ended.
Then Techstars New York rejected the company. Managing director Alex Iskold pointed to limited traction and the absence of an operating team. Garvey acted on the criticism. He found Conor Swanson through LinkedIn and sent him a cold email. Swanson brought experience at Experian. Attorney Anthony DiChiara joined in a cofounding role, while John Atkins took on content and customer service. Garvey used his marketing experience to expand the registered user base.
Iskold subsequently connected him with Jason Seats at Techstars Austin. On March 20, 2015, Garvey moved to Austin for the accelerator. The geography of the business changed, and so did its access to people who could help. Self’s early progress depended on introductions, specific expertise and someone answering an email. The stage photograph was the visible beginning. Much of the actual beginning happened afterward.
The software under the software
The product sounded manageable: a bank would make a small installment loan and hold the proceeds in a certificate of deposit in the customer’s name. The customer would make scheduled payments, with payment history reported to credit bureaus. At the end, the remaining deposit proceeds would become available. Interest and fees meant it was a paid product, and payment behavior mattered.
Making that sequence work exposed a second problem. Existing bank software was costly relative to the revenue on a small loan. Garvey’s team built its own core technology, covering account opening, servicing, records and reconciliation. A simple customer experience required considerable machinery underneath it. The phrase “build an app” can conceal an astonishing quantity of accounting.
Self passed an audit of its processes and controls in October 2015, signed its banking agreement in November and launched in 43 states on February 27, 2016. Garvey’s account puts nine months between the first bank introduction and the signed paperwork. For a founder accustomed to software, this was a different clock: each dependency had to be satisfied before the next could move.
“How hard could it be?”
James Garvey, on the early product plan · 2016
- 01A loan, held in a depositThe bank places the loan proceeds in a locked account.
- 02A record, built over timeThe customer makes payments. Payment history is reported.
- 03A deposit, released at the endRemaining proceeds become available after completion.
The original model in outline. Interest and fees apply; a higher credit score is not guaranteed.
Saturday morning, in writing
One of Garvey’s more revealing habits came out of Techstars. Every Saturday morning, he wrote an update for shareholders, employees, advisers and even attorneys. It included challenges, successes, failures and a photograph. The picture might be a team selfie, an achievement or something funny. The numbers came along too.
He explained the routine in 2016 as a way to keep investors informed, keep the team together and make management accountable. It also reduced the work of bringing an adviser up to speed before asking for help. Candor had a practical return: people could be useful sooner when they already knew what was happening.
The accompanying pictures made a company’s progress look like people at work rather than a sequence of funding announcements. January 2016 began with 10 active customers; by December, Self had more than 7,000. Staff grew from six to 13. These were small enough numbers to describe without ceremony, and large enough changes to demand attention. Later, once the company passed 250 full-time employees, Garvey changed the rhythm to monthly employee updates and quarterly investor and board updates. The habit adapted to the audience.
January
December
A shorter name, a longer relationship
By the end of 2018, Self had launched its mobile app and grown from 17 employees to 31. Garvey’s year-end account recorded more than $100 million in credit builder accounts opened during that year. He also celebrated one million individual payments processed in September. Behind the aggregate sat the recurring act the product depended on: a customer making another payment.
In August 2019, Self Lender shortened its name to Self. Garvey presented the change as room for a broader set of tools. The name put the customer in the foreground and allowed the business to grow beyond the word “lender.” A secured Visa card followed in September, allowing eligible customers to use savings progress toward the security deposit.
The expansion addressed an awkward question for a business built around a finite loan: what happened when the customer finished? A credit card offered a continuing relationship. More products also meant more operational demands. Investors kept backing the company through successive rounds; in September 2021, Self raised a $50 million Series E. Its financing history had become considerably more elaborate than that of Garvey’s earlier bootstrapped business.
Garvey later described asking customers about the card’s features, pricing and appearance before launching it. The customers had already supplied the larger request: after completing the original product, they wanted a credit card. That gave the team a direction, followed by a set of smaller decisions to test. Listening could be concrete work, down to what a card should look like when someone took it out of a wallet.
Character on the jersey
Self’s name reached San Antonio Spurs jerseys through a connection inside the company. An employee knew someone at the Spurs, and a conversation turned into an introduction. Garvey had already considered another NBA sponsorship and declined it. With the Spurs, discussions about recruiting and character made the fit feel right.
The partnership was announced in June 2022. For a company asking consumers to trust it with unfamiliar financial products, recognition had a commercial purpose. Garvey’s explanation, however, dwelt on how the basketball organization chose its people. He was interested in the workings of the team as well as the space on its shirts.
That year he also won an EY Entrepreneur Of The Year Central South award. By the time he discussed Self’s growth in early 2024, he could describe a business that had raised about $127 million and grown to roughly 600 people. Those were milestones from the journey, rather than permanent readings on a dashboard. A company changes size; the decisions that got it there remain available for inspection.
- Self Lender founded
- CEO handoff; stays on the board
- Returns as CEO, March 17
Back at the desk
In October 2023, Garvey handed the CEO role to Julie Szudarek and stayed on the board. He had spent years leading Self, and he and his wife had welcomed their first child. During his subsequent sabbatical, he advised other companies and wrote down lessons from his own. Hiring, integrity, repeat investors and listening to customers all featured in the reckoning.
His public description of his interests remains technical and patient: credit access, regulated product design and businesses that can last for decades. He describes an appetite for structurally difficult problems. The credit system has provided an ample supply.
On March 17, 2026, Self announced that Garvey had returned as CEO. The company said it had helped more than four million people over its history. His agenda on returning included simplifying the organization, clarifying responsibility and improving execution. An October 2026 conversation with David Cohen revisited the experience of stepping away and coming back.
“Helping people move forward financially is why Self exists,” Garvey said on his return. The ambition still leads back to the original inconvenience: a person wants to establish a record and needs somewhere to begin. Garvey has now occupied several positions in that story - puzzled customer, builder, board member, returning chief executive. The credit file that sent him looking for answers has kept him rather busy.
The conversation continues
More from Garvey, in his own words, and the announcements along the way.
- Personal website & collected writing
- James Garvey on LinkedIn
- James Garvey on X
- Listen: Give First with David Cohen · October 2026
- Listen: Wharton FinTech · 2021
- Read: Seven lessons from building Self
- Listen: Selling Objective Loyalty
- Read: Building the software underneath Self
- The March 2026 CEO announcement
- Self Financial