A homebuyer sees a mortgage as a beginning: keys, boxes, the first night in a new place. A mortgage company sees another event approaching. It must fund the loan before it can sell that loan to an investor. Between those moments sits a financing problem. Merchants Bank IN has made a business of being useful in that interval. The customer holding the house keys may never encounter its warehouse lending team. The customer's lender might depend on it.
- Funds mortgage bankers between origination and loan sale.
- Connects housing finance with everyday banking.
- Specialization creates opportunity - and concentrated credit risk.
The opening other lenders left behind
In 2009, when other lenders were retreating from mortgage warehousing, Merchants entered the business. Its own history describes a deliberate move toward independent mortgage bankers who still needed financing. That decision makes more sense when you look backward. Michael Petrie and Randall Rogers had started PR Mortgage & Investments in 1990, concentrating on multifamily lending. They knew the machinery before they began financing more of it.
The business has several birthdays. The underlying Indiana bank dates to 1923. Petrie and Rogers acquired Greensfork Township State Bank in 2002; the Merchants Bank of Indiana name arrived in 2009. The distinction matters. This is an old banking charter carrying a business shaped by mortgage specialists. A depositor and a mortgage originator enter through different doors, but both become part of the same institution.
A warehouse with no loading dock
A mortgage warehouse stores funded loans temporarily, rather than boxes. Merchants supplies lines of credit and loan participations to single-family and multifamily mortgage bankers across the country. The practical benefit is continuity: an originator can keep financing customers while earlier loans move toward sale. The bank earns interest for supplying that capital.
Correspondent lending adds another connection. Merchants offers approved sellers agency and non-agency mortgage programs, delegated and non-delegated underwriting, and different sale-execution options. Warehouse financing gets a loan funded; correspondent lending offers a route for selling eligible loans. The two services address adjoining stages of the same process.
Through Merchants Capital, the business also reaches apartment developers and affordable-housing owners. Construction financing, bridge loans, permanent debt, tax credit equity, and servicing address different points in a property's life. Its relationships with HUD/FHA, Fannie Mae, and Freddie Mac give that work a connection to established housing-finance channels. The competitive proposition is coordination: fewer financing handoffs for a project with several kinds of capital to assemble.
For a mortgage banker comparing lenders, the questions become practical: what loans qualify, how the facility is structured, and how reliably funding arrives. A familiar retail brand answers only part of that decision.
The loan before the loan sale.
- 01FundWarehouse credit finances a mortgage.
- 02SellThe originator sells the eligible loan.
- 03RepeatRepayment frees capacity for another loan.
Growth sends an invoice
Specialization still needs funding. Parent company Merchants Bancorp went public in 2017. Including the underwriters' additional shares, the offering raised $115 million gross and approximately $106.2 million net. Underwriting discounts and offering expenses consumed about $8.8 million. Shareholders supplied expansion capital and received ownership in return.
The operating model combines interest earned on loans with fees and income from originating, selling, and servicing mortgages. Deposits help finance the balance sheet; deposit interest is a cost. Growth therefore requires attention to both sides of the business. More lending creates a larger demand for money.
By June 30, 2026, the parent reported $21.2 billion in assets and $14.3 billion in deposits. Those are consolidated group figures. They describe the scale surrounding the bank, rather than the bank subsidiary alone.
Gross proceeds, including overallotment.
$106.2m net · $8.8m discounts & expenses
The interval can get expensive
A short bridge is useful only if there is somewhere to land. Higher long-term interest rates can make the conversion to permanent financing harder. In its July 2026 results, management acknowledged pressure on loan-sale income, while pointing to servicing rights and derivatives as offsets. Different earnings streams help, but they do not remove credit risk.
The parent recorded $16.5 million in charge-offs in the second quarter of 2026, almost 95% associated with two multifamily loan relationships. That is a concrete cost of loans going wrong. Its provision for credit losses nevertheless fell to $9.2 million from roughly $53 million a year earlier. Recovery and risk were present in the same report.
Merchants has also changed its shape. In January 2024, it sold its Illinois bank branches and merged the remaining charter into Merchants Bank. Its annual report links that decision to concentrating on single-family and multifamily mortgage lending. Expansion does not always mean keeping every business acquired along the way.
Less provision. Still risk.
Bird toys belong in this story, too
The mortgage machinery can obscure ordinary customers. Merchants also offers checking, savings, home loans, business banking, and agricultural credit. Farmers can finance a production cycle, equipment, or land, with payment schedules intended to fit farm cash flows. Small businesses can seek SBA-backed financing for working capital, acquisitions, equipment, or real estate.
An October 23, 2026 update supplied three examples: a northeast Texas manufacturing acquisition, a western Colorado bird-toy wholesaler, and a family-owned Chicago baklava and pita bakery buying space for expansion. Merchants reported $9.4 million in combined financing.
Depositors get their own variations. The Flex Index CD uses a prime-rate index minus a margin, requires $1,000 to open and earn the advertised yield, and can impose an early-withdrawal penalty. Its rate can fall as well as rise. For organizations, treasury tools include ACH, wires, remote check deposits, and account controls. An October 2026 Vantaca partnership connects banking with community association management software, bringing another customer's daily work closer to the bank.
Build around the customer’s delay
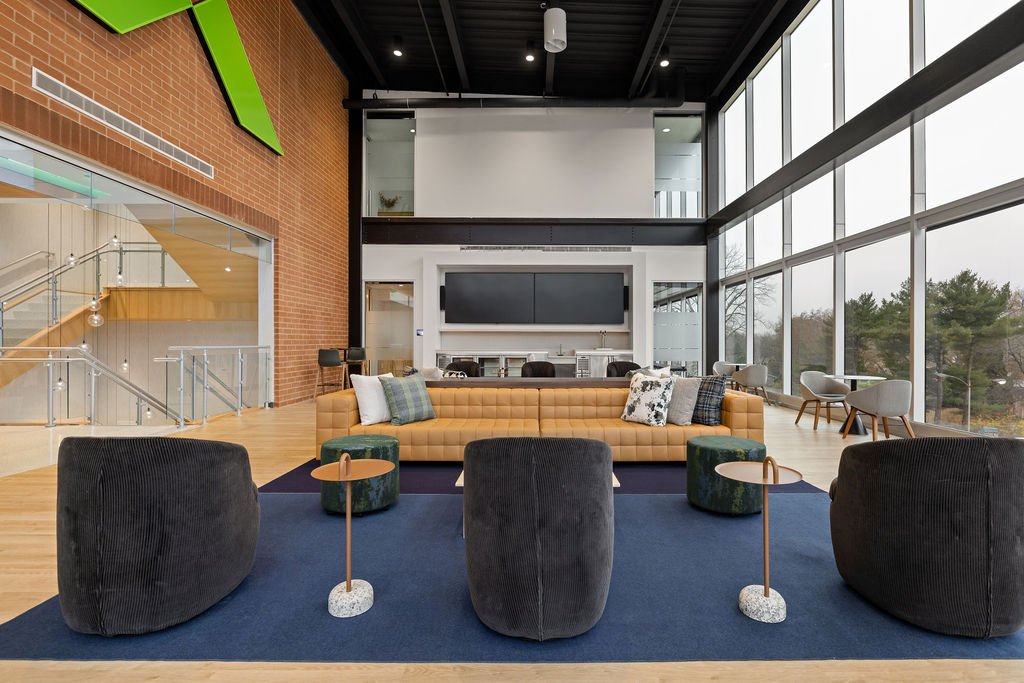
The physical business has grown alongside the financial one. A headquarters expansion opened in Carmel in October 2025, connected to the original building by a skybridge. Inside, the company advertises tuition assistance, paid volunteer time, and parental leave. Its stated values put execution alongside respect and teamwork. Those are promises employees can judge against daily experience.
“When people feel trusted and respected at work, they do amazing things.”
Michael Dunlap · 2019
The lesson worth borrowing is precise: find an interruption your customer cannot avoid, then develop the expertise to carry them through it. For Merchants, that means understanding loans, funding, and the eventual buyer. It works when those pieces stay connected. If funding tightens, collateral weakens, or the exit takes longer, the interval stops being a tidy commercial opportunity. It becomes something the bank must finance for longer than it expected.