Consider what happens when an experienced driver moves to Britain. The person arrives. The experience arrives. But the evidence of that experience may struggle to get through the door. A local insurance file can be short even when a driving career is long. Marshmallow’s founding insight sits inside that mismatch: unfamiliar paperwork can make a familiar activity look riskier than it is.
- Experience travels: qualifying overseas claim-free records count, without translation.
- The customer comes first: UK newcomers are the focus; UK-born drivers can apply too.
- The idea travels too: car finance and home cover extend the business beyond motor insurance.
The driver did not change
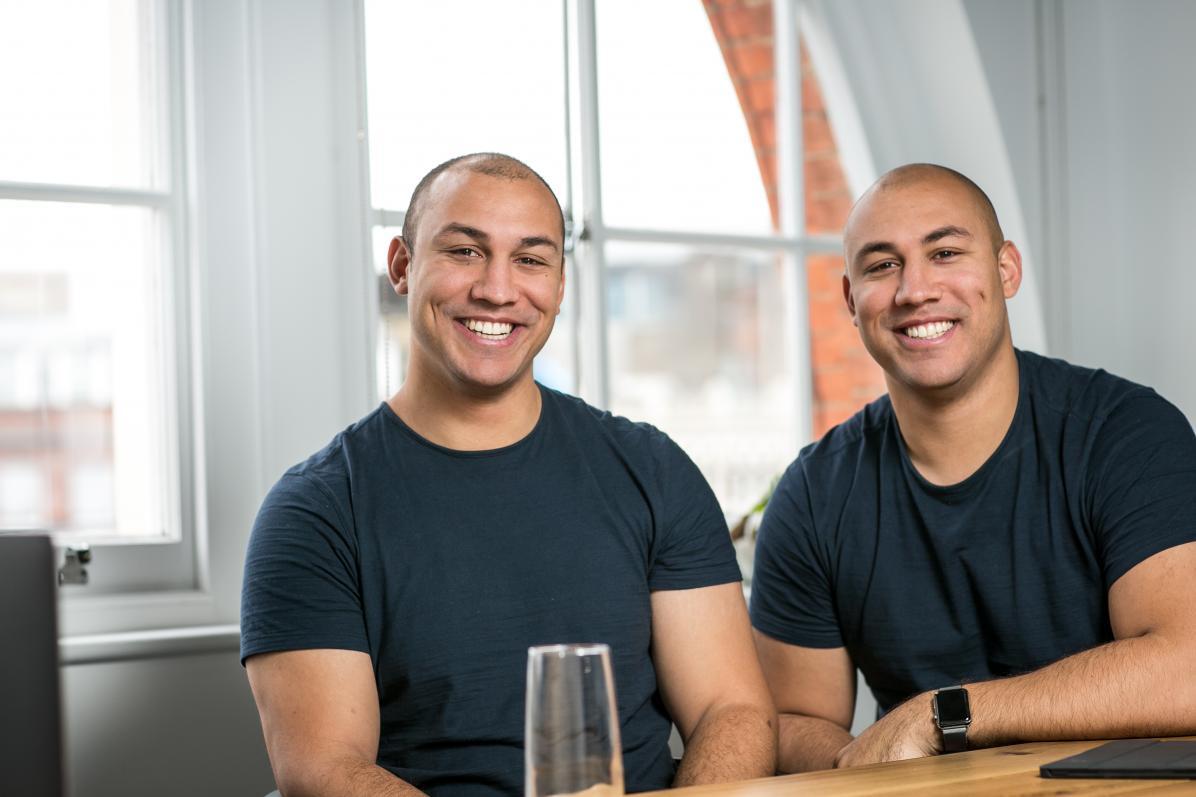
The origin story involves a South African unhappy with his insurance premiums. For Oliver and Alexander Kent-Braham, the twin brothers who founded Marshmallow with software engineer David Goate, that complaint exposed something more interesting than a bad customer experience. Here was a person whose circumstances had changed faster than the industry’s ability to understand him.
An insurance price is a prediction. The question is what information goes into it. If the useful record stops at the national border, the prediction may say as much about the insurer’s information limits as it does about the driver. A newcomer and a novice can start to resemble each other on paper. On the road, they are different propositions.
The founders began working on the business in 2017. Their early office was a gym cafe. Oliver later described a membership and desk costing £80 a month. There is a pleasing economy to that detail: an enterprise concerned with unnecessary expense began by avoiding some of its own.
A letter worth reading
Marshmallow’s distinctive act is wonderfully unglamorous. It accepts proof of claim-free driving from insurers in other countries, in other languages. No translation required. A closing statement, an insurer’s email or a no-claims certificate can help establish a record that otherwise might disappear from the calculation.
This changes the work behind the quote. Someone must decide which documents establish which facts, and how to check them. The company built its own pricing and fraud models for the customers it wanted to serve. Accepting unfamiliar evidence is an operational commitment, not simply a nicer sentence on an application form.
The promise has boundaries. The proof needs dates, claims details and the insurer’s contact information. A driving licence alone does not establish a no-claims record. Marshmallow asks customers to upload proof within seven days; it will not collect it from their previous insurer. A gap in cover longer than three years can disqualify a record. Missing acceptable evidence can mean losing the discount.
insurer record
verification
claim-free years
For a customer, the practical advantage is straightforward: existing experience can become usable evidence. For another business, the lesson is more demanding. Before classifying a customer as an exception, ask whether your process discarded the very information that would explain them.
Pink on the outside. Risk on the inside.
The app makes routine insurance tasks less cumbersome: policy documents, detail changes, uploads and live chat sit together. Customers can report an accident there too. But a convenient screen cannot settle the central question of insurance: will collected premiums cover claims and the cost of running the business?
Marshmallow’s insurance subsidiary received Gibraltar regulatory authorisation in December 2020. Its underwriting operation followed in 2021. Today, the distribution and risk-bearing roles remain distinct: Marshmallow Financial Services arranges policies, while the applicable insurer carries the risk. Home cover is underwritten by Wakam UK; car underwriting can involve Wakam and Marshmallow Insurance.
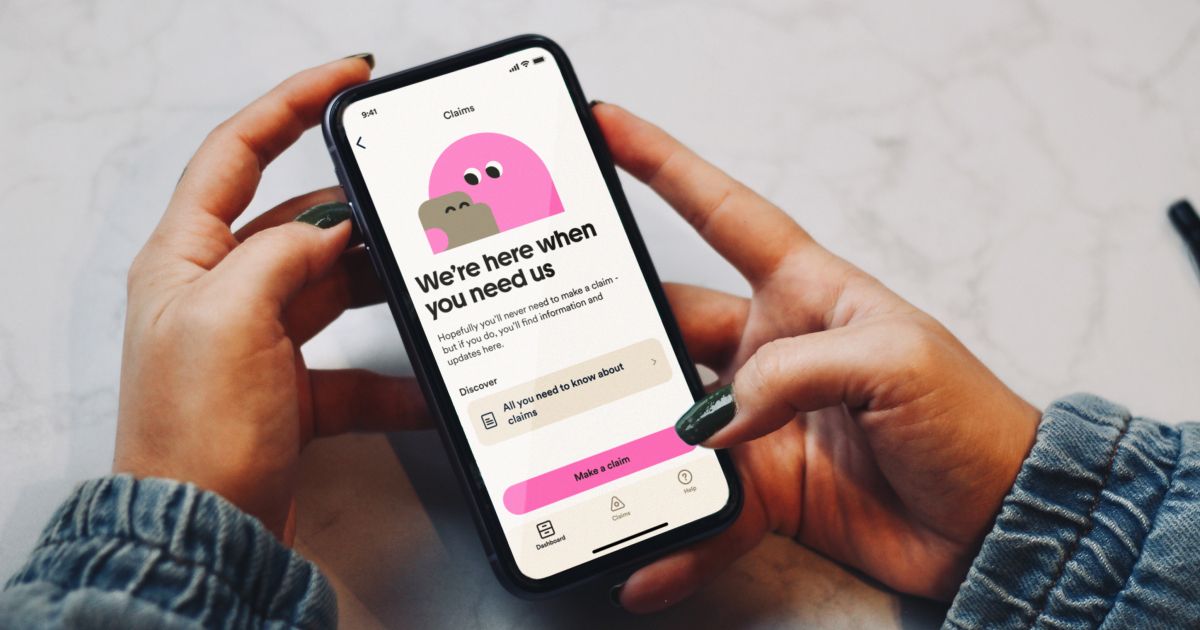
Marshmallow Move adds another stream of evidence. A small Tag pairs with the phone app to record driving behaviour using Cambridge Mobile Telematics technology. Speed, braking and phone use help shape a driving score. Safer driving may improve renewal pricing, but the product requires activation and ongoing participation. Other Marshmallow policies do not require telematics.
“You can’t quickly unwind an underwriting call because there’s always a claims lag.”Katie, Marshmallow Underwriting Manager
That observation puts the company’s appetite for speed in perspective. Software can change this afternoon. A claim from a decision made months ago can arrive later. Its expertise therefore includes fraud detection and underwriting discipline alongside engineering. The pink mascot has a cheerful job; the risk team has a patient one.
The next missing file
By April 2025, Marshmallow had insured more than one million drivers cumulatively. That month it announced $90 million in equity and debt financing, backed by Portage, BlackRock and Columbia Lake Partners, at a valuation above $2 billion. Those are measures of reach and investor confidence, rather than proof that every individual quote is competitive.
Not a count of active policies.
Customer conversations suggested another missing record: British credit history. A newcomer could need a car and still struggle to get financing. Marshmallow’s team began its lending project in summer 2024, after the business became profitable. It launched in eight months, limiting the first release to one distribution partner and concentrating its own development on pricing and lending decisions.
There was pressure after launch. Engineers helped answer customer enquiries as the team struggled to keep pace with growth. That is a useful wrinkle in the account. A focused launch reduces initial complexity; it does not remove the work of servicing the product once people start using it.
The lending product is hire purchase: Marshmallow owns the car until the agreement is completed. Its published representative example prices £10,000 over 60 months at 21.8% APR, with £15,867.60 payable in total, including specified fees. Better access remains paid borrowing. Looking beyond a thin credit file does not guarantee acceptance or make the money cheap.
Keep the evidence. Question the shortcut.
Home insurance joined the range in 2026. The connecting thread is the customer’s move, rather than a single insurance category. Yet each additional product needs its own judgement. Knowing how someone drives does not automatically establish how they will repay a loan, or what it costs to protect their home.
Marshmallow’s approach is useful where a market overlooks credible evidence and a company can afford to verify it. It becomes harder where that evidence cannot be obtained, where customers fall outside eligibility, or where claims and defaults overwhelm the pricing assumptions. The portable idea is precise: improve what you know about a person before deciding what that person should cost.