Rome Termini is an unusually literal place to start a company. Trains leave; founders hope their businesses will, too. Inside the station, LVenture Group assembled an operation that supplied young digital companies with money, advice and somewhere to work. The address was memorable. The proposition was practical: put the people who build businesses near the people who might finance or buy from them.
Founded by Luigi Capello in 2013, the venture capital business made the LUISS EnLabs accelerator, created with Luiss Guido Carli University, its operating centre. It invested early, helped founders develop their companies and aimed to make money when its stakes could be sold. Alongside that activity came corporate innovation programmes and workspace services. An investor, an accelerator and a meeting place occupied the same business.
That business now has another name. On April 1, 2024, Digital Magics merged into LVenture Group, and the surviving company became Zest S.p.A. Reading the old LVenture website as a current offer misses that turn. Its story is worth revisiting because it exposes a stubborn feature of venture investing: a company can accelerate its startups without accelerating the arrival of cash.
Five months, with homework
LUISS EnLabs gave the investment thesis a schedule. Its 2019 call offered a five-month programme with help on products, business models, technology, marketing, legal questions and fundraising. More than 50 advisors were available. Applicants needed a working prototype or validated minimum viable product, complementary team skills and a willingness to work full time in Rome or Milan.
This was a particular kind of customer: a founder who had something to test and needed help turning it into a financeable business. A loose idea was a poor substitute for a functioning team. The programme’s value lay partly in bringing several difficult jobs together. Product development, finding customers and preparing to raise money could be worked on during the same stretch of company life.
The money changed with the call. A September 2022 announcement for the 2023 edition advertised customised pre-seed investment of up to €200,000, supported by the Lazio Innova partnership. Eligibility for regional co-investment mattered. Elsewhere, the legacy startup page promoted seed investment up to €250,000. These figures describe different offers and stages; they are not a universal cheque size.
Selection → acceleration → Demo Day. The pitch ends; the investment keeps running.
The cost to a founder included ownership. LVenture invested for equity, so the headline amount was not a free grant. Founders also committed time and, in the 2019 call, relocation. The useful question was whether the capital and support justified that exchange. A team already selling confidently might value a different package from one still discovering who would pay.
A railway station with a second business
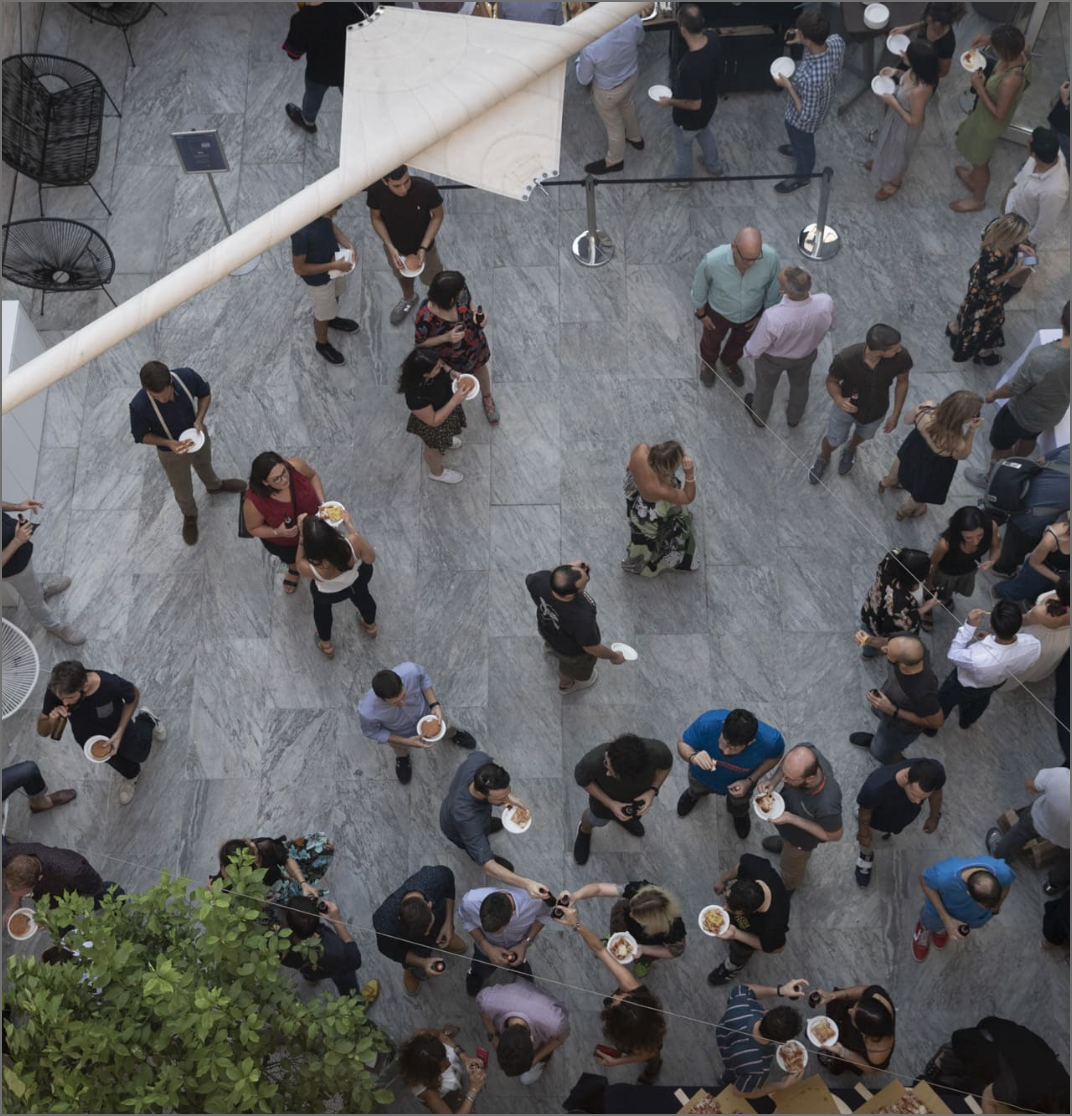
The physical hub helped make the introductions plausible. Capello described Termini as “un centro di creazione di business” - a business creation centre - in a 2023 interview. His point was about the mix of occupants and activities: startups, investors, the accelerator, education and corporate organisations within the same setting.
There was a second set of customers here. Established companies could buy help with entrepreneurship training, startup engagement, corporate venturing and growth. LVenture’s corporate offer included finding opportunities outside an organisation and encouraging ideas inside it. Those assignments used some of the same skills required to select and support startup investments.
The arrangement addressed a familiar coordination problem. A young company needs access to customers; a large organisation wants to find useful technology without examining every startup itself. LVenture offered to do some of that searching and translation. Its published services make the role concrete, although an introduction still leaves both sides with the work of agreeing a project.
Zest continues to market the Termini hub for offices, coworking and events. Its current hub page describes more than 50 corporate and startup residents and over 400 annual events. Those are successor-company claims, not a historical LVenture scorecard. They nevertheless show that the station remained part of the commercial proposition after the name changed.
Hotel software makes the arithmetic visible
LVenture’s portfolio was spread across digital businesses. Its legacy listings include Vikey, which combines hardware and software for remote holiday-apartment management, and Screevo, a voice assistant for controlling machines and software. Lybra Tech worked on hotel revenue management. Such products put specific operational problems behind the broad label “technology startup.”
Lybra also supplies a compact example of the investment model. LVenture’s 2020 annual report records €230,000 invested: €80,000 during acceleration and €150,000 in a seed round. The sale of its stake to Zucchetti produced €977,000. The reported cash-on-cash multiple was 4.25 times, with €747,000 above the amount originally invested.
4.25× reported cash-on-cash return on this investment. Gross proceeds, not a portfolio-wide return or an annual yield.
That is the transaction the accelerator business ultimately wanted to help produce. A product became useful enough for another company to buy a stake, allowing an early investor to collect cash. It is a much narrower achievement than proving every investment worked. One successful sale says little about the capital tied up elsewhere or the running costs incurred along the way.
The clock that Demo Day cannot reset
At LVenture’s tenth anniversary, Capello put a typical startup’s journey to exit at six to eight years. That was his estimate, not a promise. Set beside a five-month accelerator, it explains the awkward timing of the business: support can be delivered quickly while the asset remains difficult to sell.
The final full standalone year was uncomfortable. LVenture reported a €3.2 million loss for 2023, compared with €2.7 million in 2022. Revenue fell to approximately €6.3 million from €6.5 million, while annual investment declined to €1 million from €1.5 million. The company could point to its portfolio’s prospects, but its own accounts still showed a loss.
There is a distinction here between developing valuable businesses and recording a profitable year. Capello linked the 2023 venture downturn to macroeconomic and geopolitical conditions affecting investee valuations. A holding company carries both the operating expense of supporting businesses and changes in what those holdings are worth. A busy hub does not make either number disappear.
The lesson for another accelerator operator is to budget beyond the programme. The milestone after graduation matters: another financing round, a customer contract or progress toward a sale. An organisation that needs prompt, predictable cash cannot assume early-stage equity will provide it. That timing problem follows directly from the model, even when some investments turn out well.
ZERO brings industrial customers into the room
LVenture also took its method into a more specialised setting. ZERO launched in 2021 with CDP Venture Capital, Eni and ELIS. LVenture and ELIS managed the programme and co-invested with CDP. Eni supplied the main industrial partnership through its entrepreneurship school, Joule, while other corporate partners brought additional expertise.
The launch specified €4.6 million in initial resources and another €1.8 million committed for follow-on investment. Those were resources for the initiative, not money raised by LVenture itself. The target was 30 startups over three years, working on areas including emissions, waste, energy transition and the circular economy.
By February 2024, Eni reported that ZERO had accelerated 30 startups from 850 applications. About 30% of applications came from more than 50 countries outside Italy. For a founder, the attraction was access to people who understood the industrial problem. For an operator copying the approach, the essential ingredient is a partner able to evaluate and test the technology. A badge on a slide cannot do that job.
Then the investor needed more scale
Digital Magics was a natural company to compare with LVenture: another Italian startup incubator with investment and corporate relationships. The two chose combination. In announcing the merger plan in June 2023, Capello described an ambition to achieve enough scale to compete beyond Italy, in Europe. That is the documented strategic rationale; it does not require a story about a private epiphany.
The ownership arithmetic was explicit. Digital Magics shareholders would receive 46 shares in the combined company for every five they held. At completion, former Digital Magics shareholders held 63% and former LVenture shareholders 37%. Luiss subscribed a €2.5 million reserved capital increase ahead of the transaction, reinforcing the university’s financial involvement.
The combined operation separated investment management and corporate innovation into Zest Investments and Zest Innovation. That organisation made visible the two activities already running through LVenture’s story: taking stakes in young companies and selling expertise to established ones. Adjacent alternatives such as H-FARM also offered innovation support; LVenture’s particular combination included direct investment through a listed holding company and the Luiss partnership.
The next departure is labelled Zest
By July 2026, the successor had another development to announce. Zest and Eureka! launched Z_One, an AI and UrbanTech venture fund with a €55 million fundraising target and plans for up to 100 early-stage investments. Those numbers describe an intended scale, not €55 million already collected or 100 deals completed.
For founders looking for help now, Zest’s current investment and scouting channels are the relevant starting point. For corporate teams, the innovation business and hub offer different entry points. The old LUISS EnLabs calls remain useful evidence of how the approach worked, but their dates and terms belong to the past.
What can a reader borrow? Bring capital, practical help and potential customers into the same process. Make the next commercial or financing milestone explicit. Keep participant counts separate from investment returns. LVenture’s station experiment made those connections tangible. Whether a startup leaves the platform successfully still depends on a product someone wants and a business someone will eventually pay to own.
Follow the next chapter
Explore Zest’s current business, its news and Termini hub, or visit the LVenture archive and historical portfolio.
Find LVenture on LinkedIn, X, Instagram and Facebook. Watch its YouTube channel for company videos.