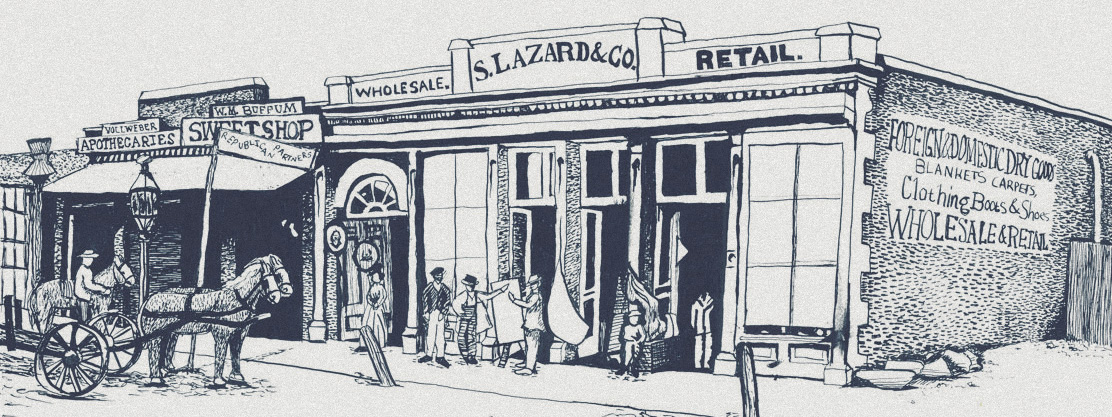
The sign above the shop says wholesale and retail. There are blankets to buy, carpets to inspect, a horse waiting outside. It is an unlikely family portrait for Lazard, the financial firm people now call when a company needs selling or a mountain of debt needs rearranging. But the old storefront contains a useful clue. Lazard learned to move money because it already knew the people who needed money moved.
- Independent advice on deals, financing and financial distress.
- Active investment management for institutions and private clients.
- A planned $575 million acquisition to expand private-capital advice.
Cloth, gold and the next customer problem
Alexandre, Lazare and Simon Lazard formalized their New Orleans dry-goods partnership in 1848. Their combined contribution was $9,000. The brothers followed the California Gold Rush, opening in San Francisco in 1851. Customers included French emigrants who wanted to send gold home. Helping them do that led into commercial drafts, foreign exchange and banking. In 1876, the remaining merchandise was liquidated.
The interesting invention was the relationship between one transaction and the next. A customer buying imported goods might also need a reliable way to send value across an ocean. The merchant could see both problems. Today, Lazard’s version of that proximity is the banker who understands a company’s shareholders, creditors and possible buyers before the company decides which conversation to have.
The adviser across the table
Lazard’s financial-advisory identity rests on a specific arrangement: it advises without serving as a lender or proprietary trader. A chief executive can ask whether to sell a division without also being offered a loan from the same balance sheet. The model reduces those particular conflicts. It still leaves clients with a sensible question about how the adviser gets paid.
For a board, the work can mean evaluating an acquisition, separating businesses or responding to an unsolicited approach. For a struggling borrower, it can mean negotiating with creditors, exchanging debt or comparing a sale with bankruptcy. Governments can seek help with sovereign finances; companies can buy geopolitical analysis or prepare for shareholder activism. These are services for consequential decisions, with terms negotiated around the assignment.
Evercore, PJT Partners, Moelis and Rothschild & Co. offer alternative independent-advisory routes. Large banks compete too, bringing financing capabilities. Lazard’s argument emphasizes its international relationships and local knowledge. Its London, Paris and New York houses operated separately for much of its history, formally uniting in 2000. That heritage helps explain the firm’s phrase, Local First, Global Second
.
Two businesses, two clocks
The other clock belongs to investment management. Lazard Asset Management, Lazard Frères Gestion and its private-wealth operation serve institutions, companies and families through research-led portfolios and investment advice. Their offerings span equities, fixed income, multi-asset strategies and alternatives. A pension institution choosing an investment mandate faces a different problem from a family seeking wealth planning, even when both want the same thing: money managed with care.
Advisory revenue includes retainers and transaction fees, often tied to completion. Investment-management revenue generally follows assets managed, with some performance fees. Deals can stall; asset values and client flows can fall. The combination gives Lazard different ways to earn fees, but neither business escapes markets. Active managers also face the inconvenient comparison with cheaper passive funds.
Assets managed for clients. This is neither Lazard’s revenue nor money it owns. Components rounded independently.
A reset with a real bill
Experience does not make an adviser immune to a quiet deal market. Lazard’s 2023 results disclosed $195.1 million in expenses associated with cost-saving initiatives, plus $4.9 million of related losses. Those figures describe the cost of changing the business, rather than the price a customer pays for advice.
Peter Orszag, CEO since October 2023, has pursued growth through senior hiring, private capital and a more commercially accountable culture. The company’s stated principles include empowerment and engagement; management also stresses collaboration and apprenticeship. Those ambitions matter because a relationship business must somehow make individual expertise travel across teams. Hiring another experienced banker helps only if the firm can turn that expertise into useful assignments.
A $575 million bet on private markets
In April 2026, Lazard agreed to acquire Campbell Lutyens, a private-markets adviser. The terms were unusually concrete for a business built on judgment: $460 million initially, subject to closing adjustments, $115 million two years later, and a possible $85 million earn-out. The planned combined business, Lazard CL, would handle fundraising, secondary transactions and capital advice for investment managers.
The logic is straightforward. Private funds need investors at the beginning and liquidity later. Their managers and portfolio companies need advice between those moments. Adding Campbell Lutyens gives Lazard more opportunities to serve that cycle. Separately, its Arini cooperation agreement connects advisory clients with potential private-credit financing, subject to duties and client consent.
The October 22 results anticipated an early-November launch for Lazard CL. They also supplied a useful reality check: third-quarter net revenue rose 9% to $814 million while GAAP net income fell 59% to $29 million. Expansion and earnings do not arrive together automatically. Paying for talent and integrating a business can consume money before the promised productivity appears.
“investment performance will continue to be the ultimate driver of flows”Peter Orszag / Lazard 2030 update, September 2025
The lesson outside the boardroom
A smaller company can borrow something here without hiring an investment bank. Look for the expensive problem next to the service customers already trust you to provide. Then check whether you have the expertise, incentives and resources to solve it. Proximity creates an opening; it does not confer competence.
For prospective clients, start with the decision. A board considering a sale needs transaction judgment. A borrower needs financing options and negotiating help. An investor needs a suitable strategy, understandable fees and tolerance for losses. Lazard cannot supply every ingredient by itself: independent advice still needs willing buyers, lenders or investors. The old merchant’s advantage survives only while the next customer problem is one the firm can actually solve.