The patient construction of a private-market machine
Private markets had no shortage of velvet ropes. A wealthy client might qualify for a fund, and an adviser might know why it belonged in a portfolio, yet the practical experience could still feel like being handed a boarding pass for a flight with no airport. There were documents, eligibility checks, capital calls, distributions and reports arriving on different clocks. Lawrence Calcano saw the inconvenience as a systems problem. The glamorous word was access. The useful word was infrastructure.
Calcano had spent his career near the junction of money and machinery. He began at Morgan Stanley, then spent 17 years at Goldman Sachs, where he became a partner and managing director and co-led the Global Technology Banking Group. His clients came from internet, digital commerce, software, services and hardware. The work trained him to notice what happens when an old industry meets a new operating system. It also gave him what he later called a front-row seat to the frictions of private equity, hedge funds and venture capital.
The biography contains one pleasing contradiction. At Holy Cross, Calcano studied economics and theater. He had grown up on Long Island and played hockey. Economics offered incentives, theater offered people, and hockey offered the useful discovery that a brilliant solo is still taking place inside a team game. He later earned an MBA at Dartmouth's Tuck School, graduating as a Tuck Scholar. By the time iCapital appeared in 2013, his education looked less eclectic than prophetic.
A marketplace begins with an awkward silence
iCapital was founded to help independent wealth advisers obtain and manage alternative investments for their clients. Those advisers could oversee substantial fortunes while running comparatively small businesses. They did not want to build an operations department every time a client bought a private fund. Asset managers, meanwhile, had systems designed for a few large institutional commitments rather than a crowd of smaller wealth-management accounts.
Calcano began advising the young company in 2013, leading strategic and business-development work, and became chief executive in 2014. The first obstacle was a familiar joke in marketplaces. Advisers asked which fund managers had joined. Fund managers asked which advisers and how much money were already there. Each side would be delighted to arrive second.
One investment, one connected journey
There was no theatrical reveal. The company had to add credibility one relationship and one completed workflow at a time. Its proposition grew beyond a shelf of funds. Education, due diligence, portfolio construction, subscription technology, servicing, reporting and data became parts of the same journey. The company later expanded into structured investments, annuities and broader data services. A marketplace had become an operating layer.
“We want to make investing in and owning these assets as easy as owning a mutual fund.”Lawrence Calcano on the purpose of the platform
The number is large. The verbs are small.
By 2024, iCapital had passed $200 billion in global platform assets. In July 2025, it raised more than $820 million in a financing led by T. Rowe Price and SurgoCap Partners, with participation from State Street and larger commitments from Temasek, UBS and BNY. The round valued the company above $7.5 billion and supplied capital for acquisitions, international growth, technology and data.
By 2026, iCapital said its platform serviced more than $1 trillion in client assets across more than 2,100 funds and supported 118,000 financial professionals. The leap in headline scale is striking, but Calcano's preferred verbs remain modest: learn, subscribe, manage, report. Private investing depends on a procession of ordinary actions being completed accurately. A platform earns its grandeur by making each of them less grandiose.
His argument for wider participation also contains a brake pedal. Calcano has repeatedly said education must accompany access. Private funds can be illiquid, complex and unfamiliar to individual investors. He has warned against moving so fast that people buy before they understand. A durable path to broader use, in his telling, may not be the quickest. It is a notably unfashionable message from someone paid to help a market grow.
The weekly note
Building the machine required another kind of infrastructure. For nearly a decade, Calcano has written an email to the entire company every weekend. It explains what iCapital is doing and why. Each note returns to two observations: the work must help clients succeed, and it must be done as a team.
He borrowed both principles from Goldman Sachs, where client interest and teamwork were treated as operating rules. At iCapital, he pared the message down because scale punishes elaborate catechisms. When colleagues make hundreds of choices without the chief executive nearby, they need a short compass, not a marble tablet. Every employee also has equity. The language of ownership is therefore backed by an actual stake.
“It's a thousand little things.”Calcano on how a company culture becomes real
The phrase is his answer to how culture sticks. Compensation matters. Promotion matters. Leaders' behavior matters more than the sentences printed on office walls. Consistency matters too. Calcano's weekly note is not a literary vanity; it is management by recurrence. In finance, compounding usually arrives with a percentage sign. Here it arrives on Sunday.
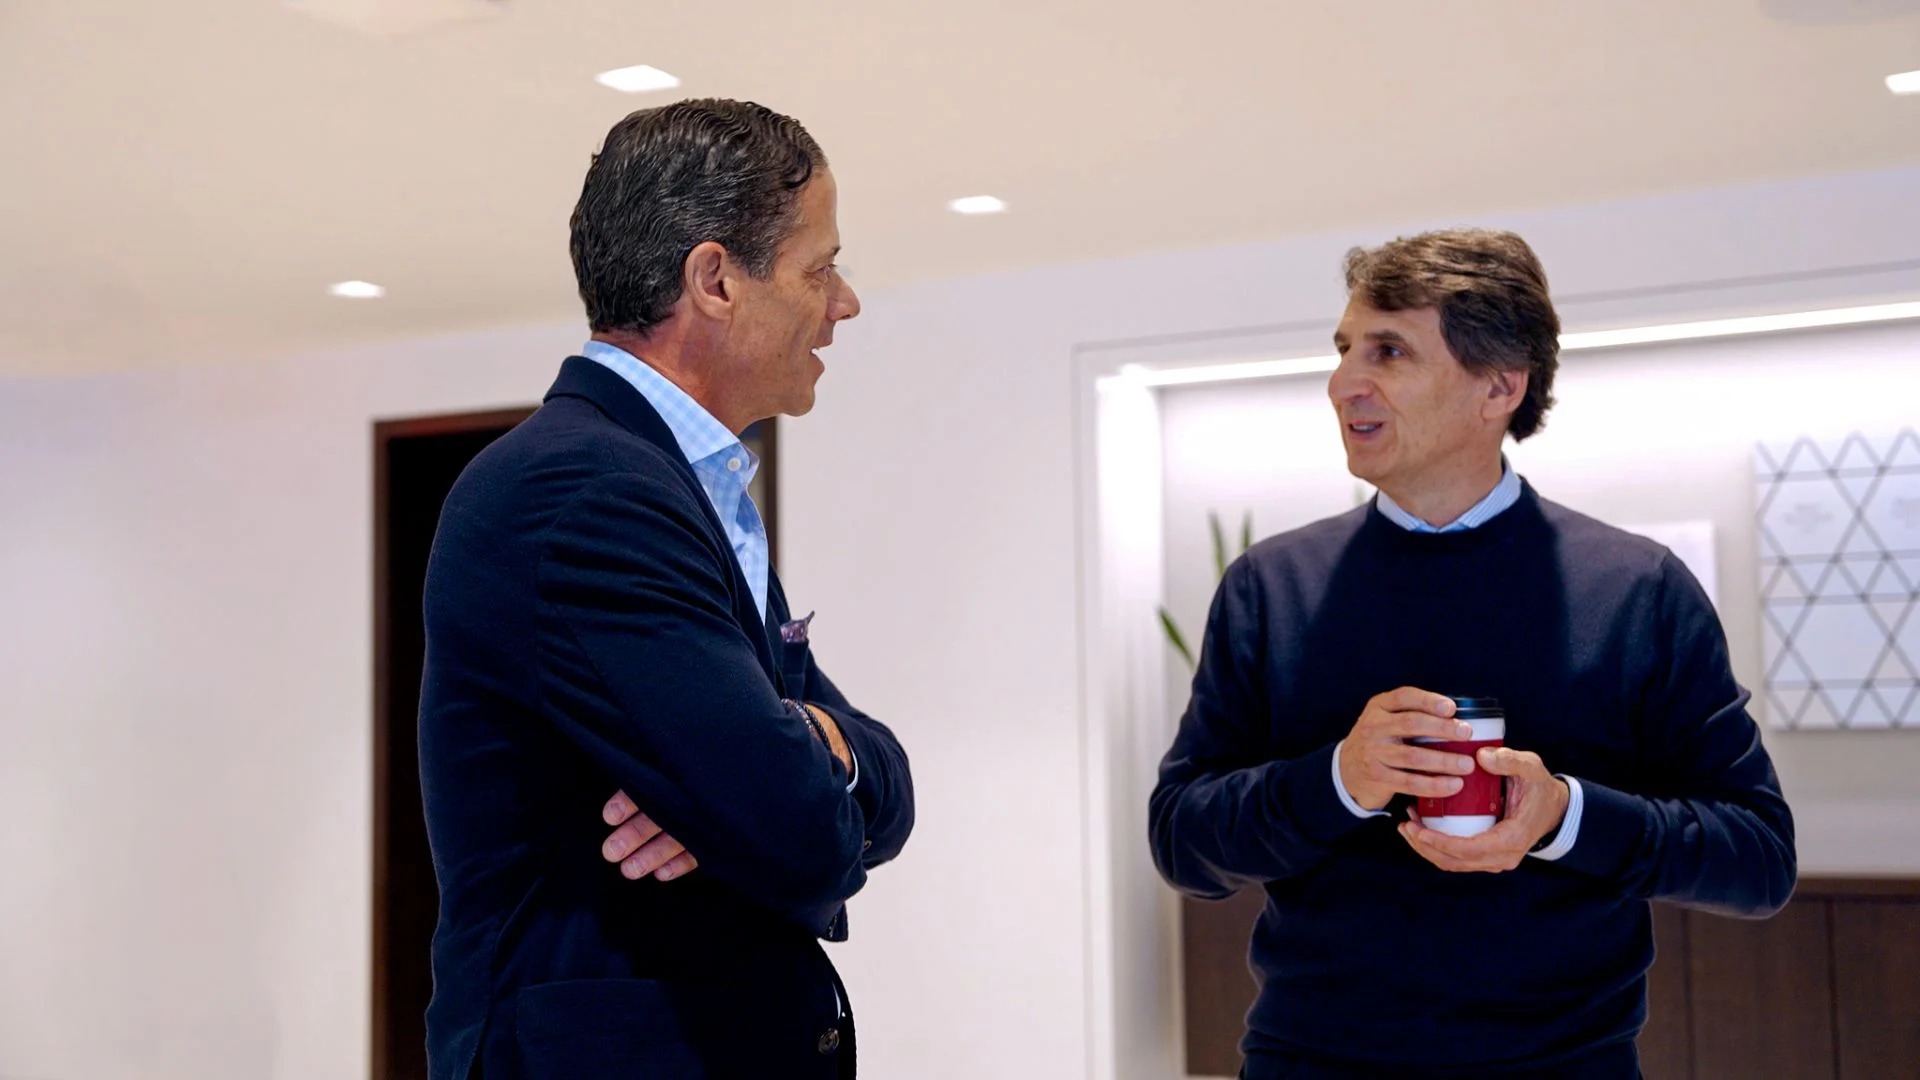
That interest in culture has also made Calcano an interviewer. On iCapital's The 19th Hole, he talks with investment leaders about their careers, organizations and mistakes. A 2026 conversation with Apollo co-founder Marc Rowan wandered through leadership, innovation and why people remain at firms. Calcano highlighted Rowan's observation that people join firms but stay for cultures. The host had found his chosen subject wearing somebody else's quotation marks.
Growth has also forced him to edit his own job. A founder-sized organization can run on proximity: everyone hears the same conversations and the chief executive can see the seams. A company spread across offices and continents cannot. Calcano has spoken about bringing in Gary Gallagher as president and handing more operating responsibility to other leaders, leaving him more time for strategy, clients, culture and the industry's larger questions. Delegation, in this version, is not a retreat from the details. It is an admission that the details have become too numerous for one desk.
His advice to younger colleagues carries the same plain-spoken edge. The world owes nobody a career, he has said; the work must be earned. He couples that severity with adaptability and the importance of becoming someone other people want beside them. The hockey lesson returns. Talent may win a shift. Trust determines who is sent over the boards when the score is close.
When “alternative” becomes an antique word
Calcano's longer wager is linguistic. He thinks investors may eventually stop treating private assets as an exotic appendix. A portfolio could be understood across public stocks, ETFs and private-company shares; fixed income could encompass corporate and government bonds alongside private and structured credit. The allocation would be judged as a whole. “Alternative” would survive as a historical curiosity, like calling an automobile a horseless carriage.
Technology alone cannot bring about that shift. Advisers must understand what they are recommending. Clients must understand the trade between potential return and limited liquidity. Managers need distribution that does not bury them in administration. Data must make unlike holdings legible together. Calcano's ambition is less a bazaar than a grammar, a way for different assets to appear in the same sentence without confusing the reader.
That is why his public conversations keep returning to the adviser. Digital tools are not offered as a replacement for judgment. They give advisers a cleaner way to exercise it, and clients a better chance to see what they own. Even artificial intelligence, tokenization and distributed ledgers enter Calcano's account as supporting machinery. The test is never whether the technology sounds futuristic. The test is whether it removes friction without removing comprehension. He remains a technology banker in this respect: fascinated by systems, suspicious of novelty without a client problem attached.
Begins his finance career at Morgan Stanley after Holy Cross.
Joins Goldman Sachs, later becoming a partner and co-head of global technology banking.
Starts advising iCapital and leading strategic and business-development initiatives.
Becomes chief executive and begins turning the marketplace into an operating platform.
iCapital raises more than $820 million at a valuation above $7.5 billion.
The company reports more than $1 trillion in client assets serviced.
Recognition has followed. Calcano received the Money Management Institute's Industry Leadership Award in 2024, appeared on InvestmentNews' Hot List three times and was named a 2023 ThinkAdvisor Luminaries honoree. In 2026, he won a Gold Stevie for Executive of the Year in financial technology. Such prizes are snapshots. The more revealing artifact remains the weekly note, dispatched while the plumbing keeps running.
The story of iCapital is easily told as a sequence of enormous figures. The more human version is about tolerance for the middle: the years between an idea and a network, the forms between interest and ownership, the explanation between access and understanding. Calcano chose a business whose success would make complexity recede from view. When infrastructure works, nobody applauds the pipe. They turn the tap and expect water.