The revealing object at Grasshopper Bank is an invoice. An invoice has to become a payment, a payment has to appear in an account, and somebody has to reconcile the result. For the owner of a small business, that somebody may also be the sales department. Grasshopper has built its pitch around shortening this unglamorous journey. The account holds the money. The surrounding tools are supposed to give the owner some time back.
- The customer: small businesses, startups and the fintechs building financial products for them.
- The proposition: deposits, payments, accounting connections and lending in a digital banking relationship.
- The catch: product eligibility and transaction charges still matter; a tidy interface cannot remove those decisions.
A bank is built twice
Grasshopper opened in 2019, led by founding CEO Judith Erwin and co-founder and CTO Minerva Tantoco. The name honors computing pioneer Grace Hopper. That is a useful clue to its ambitions: technology was part of the bank’s identity before there was much banking to do. Launching required approximately $116.2 million in private-placement capital, following a $15 million seed round. A national bank charter is an expensive starting line.
Then came a second beginning. Mike Butler became CEO in May 2021. By August 2022, Grasshopper was describing a rebuild of its entire technology platform, from its core banking system through account opening and fraud prevention. It added small-business banking and Banking-as-a-Service as deposit-gathering businesses, alongside new specialty lending lines. The original venture focus had become a broader commercial strategy.
The instructive detail is how much of the machinery changed. Narmi’s case study describes integrating its digital platform with Grasshopper’s FIS IBS core in less than five months. This was more substantial than refreshing a website. The underlying systems had to support the experience the bank wanted to sell.
“I think about things in simple terms: Time and Friction.”
Mike Butler, in Narmi’s Grasshopper case study
That is an unusually serviceable design brief. Count the questions. Count the clicks. Look at the work a customer is trying to finish. The rebuild marks a shift toward a broader market and a more flexible platform. It made fintech partners part of the offering, connecting their specialized tools to the bank’s own accounts.
The account is only the beginning
Today, Innovator serves small and mid-sized businesses, while Accelerator is aimed at startups. The banking experience includes digital invoices, bill payments, mobile check deposits and accounting connections such as Autobooks and QuickBooks. User permissions and approval workflows address a problem that appears as soon as the founder stops doing everything alone: who gets to see the money, and who gets to move it?
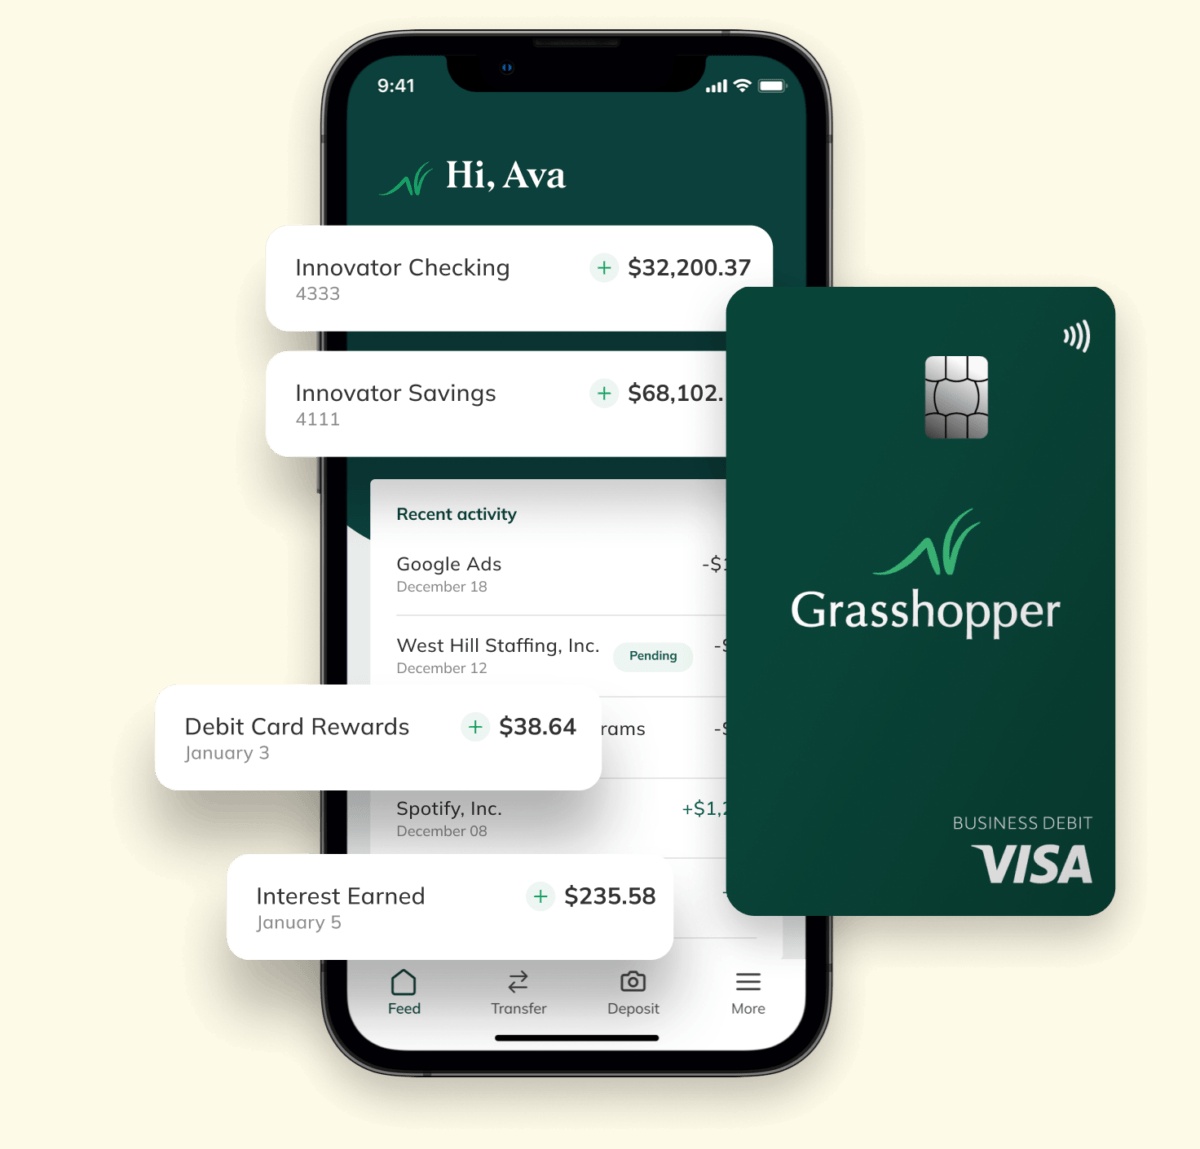
The pricing makes more sense when read as a working day. Innovator’s published table lists a $100 opening deposit and no monthly fee. Standard and same-day ACH cost nothing; an outgoing domestic wire costs $10. A business paying suppliers through ACH has a different bill from one sending frequent wires. “Free banking” is a poor substitute for counting your own transactions.
This places Grasshopper between familiar alternatives. Chase offers business accounts with branch access. Mercury offers business banking software with banking services provided through partner banks. Grasshopper combines its own national charter with outside technology. Its distinction lies in that combination and its business workflows. Owners who depend on regular teller service will need to weigh the digital model against their daily routines.
Its economics remain recognizably banking: gather deposits, make loans and collect interest and applicable fees. SBA lending, commercial real estate and investment-firm services extend the relationship beyond checking. With Lendio, Grasshopper added a digital SBA sourcing and decisioning channel in 2025. Instant offers for qualified applicants improve the entrance to the process; they should not be confused with instant cash in every borrower’s account.
Distribution without the branches
There is another customer here: the company that wants banking inside its own product. Grasshopper’s embedded finance and API services let partners offer accounts and payments. Instead of persuading every end user to discover a new bank, the bank can work through a service that user already knows.
The Auto Club Trust acquisition applied related distribution logic to consumers. Completed in April 2025, it made Grasshopper the exclusive bank behind deposit and lending offerings, excluding credit cards, for The Auto Club Group’s audience of more than 13 million members and insureds across 14 states. That is access to a market, not a count of Grasshopper customers.
Those two deposit figures deserve to travel together. Treating the larger number as entirely on-balance-sheet funding would blur the model. The bank also reported $60.64 million in 2025 revenue. Its growth story includes an acquisition as well as direct customer additions; an attractive percentage alone cannot explain which engine did the work.
Ask the account a question
The partner approach also explains Grasshopper’s AI experiment. Working with Narmi, it introduced an MCP connector in August 2025 and later added ChatGPT support alongside Claude. Authorized banking data can become the basis for conversational analysis. An owner can investigate spending and cash flow without first constructing every report manually.
The boundary is specific: the documented beta is read-only. It cannot initiate transactions or alter the account. That matters more than a futuristic product label. Analysis and execution carry different consequences. The useful experiment gives the assistant information while keeping payment authority elsewhere.
In June 2026, Waldo-powered Grasshopper Treasury added investment portfolios to the platform for eligible clients. These are investments, distinct from insured bank deposits. Together, the offerings suggest a practical operating lesson: connect adjacent jobs around the account. The approach depends on reliable integrations and customers whose work fits those tools.
A deal meets its limit
Even a well-connected digital bank faces decisions outside its software. Enova announced a roughly $369 million acquisition agreement in December 2025, then withdrew its regulatory applications in September 2026, citing concerns about the approval process. On October 16, the companies mutually terminated the agreement. Enova paid Grasshopper $4 million.
The bank remains a useful case in choosing what to simplify. An invoice, an approval and a cash-flow question are small events until they consume the owner’s afternoon. Grasshopper’s proposition earns its keep when those tasks become easier. The test is sitting in the customer’s unfinished work.