A phone sale looks finished when someone walks out of the shop. For the businesses behind it, that can be the beginning of several years of work. There are payments to collect, a cracked screen to handle, an old handset to value and, eventually, another sale to make. Glow Services has built its business around everything that happens after the celebratory unboxing.
- The customer keeps the brand. Glow supplies software behind telecom operators and electronics retailers.
- The monthly payment has company. Financing connects with insurance, warranty, fraud checks and trade-in.
- Capital matters. The pitch includes financing relationships and servicing, alongside the technology.
This is enterprise software with an unusually physical subject. Its fortunes are tied to objects people drop, lose, upgrade and sometimes misunderstand the ownership of. For a mobile operator, the phone is also a route to the service subscription. Making the device easier to buy can influence a relationship worth considerably more than the handset.
The financing came first.
The software followed.
Andrew Cole and Christiaan Ross co-founded Glow in 2014. Both brought experience from Asurion’s European business: Cole had been its regional chief executive; Ross had worked in finance leadership. Their expertise covered the less glamorous mechanics of selling and protecting devices, including the financial and operational decisions that follow the sale.
Glow’s corporate history dates its first financing contract to 2016. The revealing turn came in 2019, when it identified a technology gap and began developing a platform specifically for telecom and consumer electronics companies. In late 2020, Samsung UK committed to an outsourced captive finance strategy. Glow and Samsung then worked together on the white-label platform.
They went live in November 2021, offering interest-free credit on Samsung products for up to 48 months. That sequence matters. A financing business encountered a software problem and built around an identifiable customer’s requirements. The platform grew from a particular transaction, with particular obligations.
One checkout.
Several businesses.
The idea becomes concrete in Total Wireless Edge, announced by Verizon in December 2025. Verizon selected Glow as its strategic partner for the prepaid device financing program. Glow chose First Electronic Bank to originate the loans; Glow Financial Services Inc. services them. To the shopper, these separate responsibilities sit behind an offer from Total Wireless.
The launch promised access for existing customers with qualifying payment histories regardless of credit score. Its advertised device offers depended on eligibility and promotional credits. The disclosed loan range was 0% to 24.9% APR, subject to underwriting and state residency. A low monthly promotional price therefore tells only part of the financing story.
Separate roles. One branded buying journey.
EE offers another version of the arrangement. Its finance service launched in April 2024. In August 2025, Glow announced an additional EE-branded buy-now-pay-later proposition with three-, six- and nine-month interest-free terms. Loan origination, management and fraud detection were packaged behind the retailer’s identity. Glow sells to the enterprise; consumers encounter the resulting service through its partner.
Then there is the watch that rewards exercise. In July 2025, Glow announced a Vitality partnership, initially for Australia, to finance the Vitality Watch Program. Qualifying healthy activity can reduce the member’s watch payments. Glow described software flexible enough for someone to pay in one month and owe nothing in another, depending on activity. It is a useful example of specialization: the payment schedule has to reflect the program’s rules, rather than forcing every device purchase into the same installment plan.
Capital is part of the product
Glow combines B2B SaaS with optional managed services and financial expertise. A client can use software for lending or add support with servicing, receivables financing and securitization. This places Glow between specialist enterprise software, embedded lending and device lifecycle services. General-purpose payment companies overlap with parts of that territory. Insurers and protection administrators overlap with others.
In October 2025, Glow publicly announced a $65 million equity round involving Apollo-managed funds, Citi and John Malone’s Silver Spur Capital. Its investor page describes Apollo’s relationship as supporting financing originations too. Citi brings a separate history as a lender in Glow’s UK securitizations. These are relationships with potential uses beyond paying engineers.
Investment in the company. Distinct from the capital used to finance customers’ devices.
That distinction is easy to lose. Glow announced an approximately $800 million US telecom receivables transaction in August 2024. The number described underlying collateral, rather than sales earned by Glow. What the company was selling in that transaction was the ability to arrange a financing structure intended to improve an operator’s financial flexibility.
“Our tech helps telcos sell more phones.”Andrew Cole / Mobile World Live, November 2025
The return is where
the promise gets tested
Glow’s device subscription commentary offers a useful admission about the market it serves. Some operators, it wrote in 2024, had struggled with returns. Customers believed they owned the phone, then faced an unwelcome payment or upgrade decision. The apparent bargain at signup became disappointment at contract end. A smooth application could not repair a misunderstood agreement.
Its response connects financing with protection and trade-in, including end-of-term handling. The insurance proposition gained another component at MWC Barcelona in March 2025: Admin Inside, which embeds administration functions and regulatory requirements in software. Glow’s pitch is that operators can bring administration in-house using its platform and supporting insurance arrangements. The proposed efficiency still depends on an operating program around it.
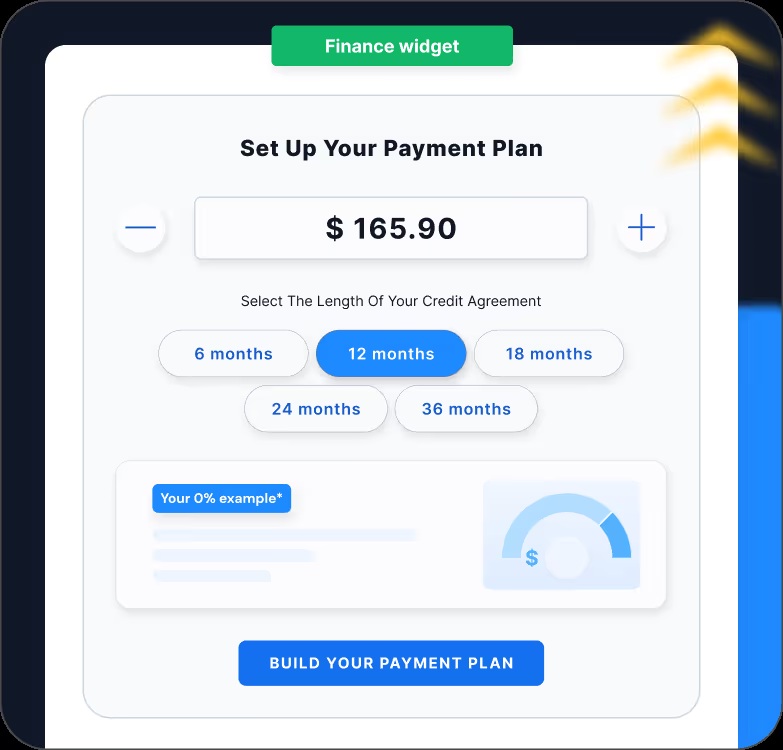
Availability also remains specific to a partner and country. Samsung Australia’s current page says new Samsung Finance by Glow applications paused from April 1, 2026 during a transitional period, while existing loans continue. A previous launch does not guarantee an open application window today. Regulated financial software has to live inside the changing conditions of an actual lending service.
A small lesson from
a complicated phone bill
The useful lesson is to follow the transaction beyond the moment everyone photographs. Glow has organized products around the awkward handoffs: approval to repayment, damage to claim, ownership to return. A retailer considering this approach needs the capital, permissions, integration and servicing capacity to support those promises.
For a builder elsewhere, the transferable idea is equally practical: learn where an industry’s everyday transaction gets difficult, then connect the work on both sides. The phone may be the attraction. The business sits in the years around it.