Consider the gutter. It has no screen, no subscription and very little to say for itself. Its job is to move water somewhere less troublesome. Gibraltar Industries has built a substantial business around objects with this sort of modest ambition: vents, flashing, mailboxes, roofing components. In February 2026, it paid $1.335 billion for OmniMax, a manufacturer of roofing accessories and rainwater systems. An unglamorous category had acquired a very consequential price tag.
- Buy the adjacent aisle. OmniMax adds roofing and rainware brands across the U.S. and Canada.
- Narrow the portfolio. Gibraltar completed its solar exit in July 2026; an infrastructure sale is pending.
- Watch the cash. Acquisition growth brings scale, integration work and a much larger debt obligation.
The interesting part is the direction of travel. A manufacturer once presented through solar, agriculture, housing and infrastructure is concentrating on building products and structures. The company’s question has become unusually concrete: which businesses deserve the next dollar, the next factory improvement, the next hour of management attention?
01The business is in the connections
Gibraltar dates its beginnings to 1972. It started in steel processing, went public in 1993 and gradually assembled specialist manufacturers. Today, its residential catalog touches several points where a house meets the outside world. Air Vent handles ventilation. Other businesses make flashing, trim, gutters and metal roofing. Florence and Architectural Mailboxes organize the arrival of the mail. Sunesta supplies retractable shade.
A homeowner benefits from those products, but the paying customer often sits upstream: a home-improvement retailer, wholesaler, distributor or contractor. That distinction explains the model. Gibraltar sells physical components through established channels; reliability, availability and a useful range matter alongside the component itself. A familiar brand on a contractor’s order sheet can matter more than recognition of the corporate parent.
The expertise is practical: forming metal, designing ventilation, fabricating structures and getting the resulting products into the right market. Its competitive position varies by aisle. Roof-ventilation buyers can also consider GAF, CertainTeed, Lomanco and Owens Corning. Gibraltar’s distinctive feature is the collection of related specialist businesses and channels. It still has to earn the individual sale.
Where the 2025 sales came from
02A billion-dollar move closer to the roof
OmniMax brings brands including Amerimax, Berger and Flamco, along with manufacturing operations in the United States and Canada. For Gibraltar, the attraction is adjacency: more products for overlapping building needs, a broader geographic footprint and opportunities to coordinate purchasing and operations. The company said the acquisition advanced its building-products growth strategy by three years. That is management’s assessment of the deal, rather than an independently measurable head start.
The purchase was announced at $1.335 billion in cash, subject to adjustments. The financing included two $650 million term-loan facilities and a $500 million revolving credit commitment, alongside existing cash. A credit commitment is borrowing capacity, so adding all three facilities together would overstate what the acquisition itself cost.
This makes the operating details consequential. In May, Gibraltar reported 22 integration planning teams and more than 500 milestones delivered in 90 days. Counting milestones cannot prove value creation. It does show how much coordinated work sits behind a transaction that can otherwise be summarized in a single price.
03The greenhouse has a cousin at the gas station
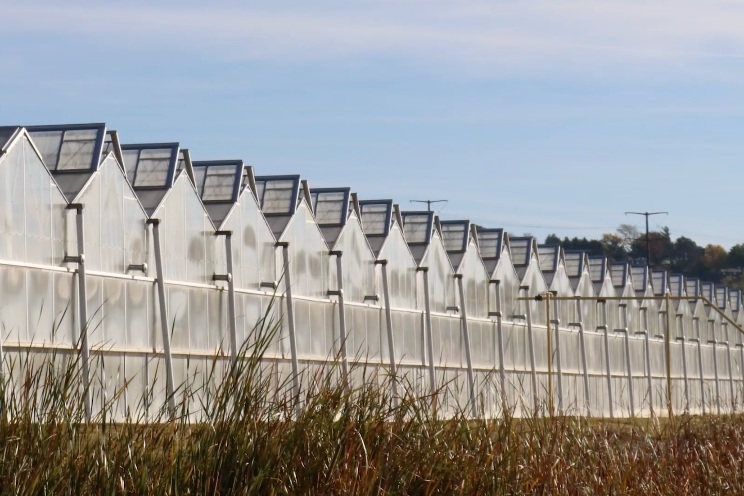
There is a pleasing wrinkle in the segment called Agtech. It contains Prospiant, which supplies greenhouses and their systems, and Lane Supply, acquired in 2025, which makes and installs commercial canopies. A grower’s greenhouse and a canopy over a fuel forecourt share a less romantic identity: both are engineered structures that somebody must design, manufacture and install.
Prospiant combines capabilities from Rough Brothers, Nexus and ThermoEnergy. Its work includes structures, heating, irrigation, environmental controls, renovation and service. Customers range from commercial growers to garden centers and research institutions. The value is coordination. A grower needs the structure and its systems to function together, with support after construction. Prospiant’s featured projects include Lucas Greenhouses and Goodness Gardens.
04Growth can conceal a retreat
The numbers complicate the tidy acquisition story. In 2025, continuing-operations sales rose 11% to $1.1355 billion. Acquisitions contributed $171.5 million of revenue. Ongoing operations declined by roughly $49 million, while portfolio changes reduced sales further. Agtech faced delayed project starts; residential mail and package products faced soft demand. Buying revenue and improving existing demand are different achievements.
Solar provided a separate reason to reconsider the portfolio. Early-2025 investor materials highlighted developer uncertainty around tariffs and trade duties. In June, the board approved an exit from Renewables. Chairman and CEO Bill Bosway argued that “a simpler portfolio” would support stronger growth, margins and cash flow. The stated rationale was the relative appeal of markets and returns. The public record does not reduce that decision to one broken product or one bad quarter.
The retreat carried an accounting cost: Gibraltar recorded a $162.7 million pretax Renewables impairment in the third quarter of 2025, followed by a $13.3 million year-end remeasurement adjustment. These were asset-value reductions, separate from the cash price of OmniMax. The exit finished in July 2026. Then, on October 15, Gibraltar announced an agreement to sell its D.S. Brown infrastructure business to Saint-Gobain for $208 million in cash, subject to adjustments. Closing was expected in the fourth quarter, subject to conditions. Gibraltar said proceeds would reduce debt. As of October 24, this was an agreement awaiting completion.
“a simpler portfolio”
Bill Bosway · June 2025The idea behind the exits. The work behind the acquisition.
05The test comes after the purchase
The lesson another operator can borrow is specific: expand around customers and capabilities you already understand, then examine the portfolio’s claims on money and attention. Gibraltar also publishes a useful cultural shorthand: “Make it better” and “Make it right.” Its stated emphasis on safety, ethics and teamwork belongs on the factory floor as much as in acquisition integration.
The conditions matter. A larger manufacturing network can help only if service, purchasing and production improve enough to justify its cost. Weak housing demand, commodity inflation, expensive debt or delayed greenhouse projects can overwhelm the benefits. In the second quarter of 2026, continuing-operations sales rose 64.6%, while net income fell 7.1%. Scale had arrived. The earnings case still needed work. For customers, the immediate proposition remains wonderfully plain: find the right component, get the structure built, keep the building working.
Company website ↗LinkedIn ↗Company news ↗Prospiant products ↗
WATCH THE STRUCTURES AT WORK