In the spring of 2024, two interns at Financial Independence Group spent a week in a department that rarely features in a sales pitch. Paul Matanovic and Graham Wald shadowed operations staff, spoke with carriers, and discovered how much work sits behind a policy. Their verdict was wonderfully candid: operations wasn’t the career for them. They had, however, found the right place to understand the business. Start with the people making those calls, and FIG becomes easier to explain.
- FIG gives independent advisors access to insurance products and specialist support.
- Its toolkit spans marketing, case design, education, and policy management.
- The latest push connects the systems that turn applications into policies.
The small firm with a large back room
The customer is usually a licensed financial professional serving households, rather than a household shopping directly for insurance. FIG occupies the space between that professional and the carrier. It helps with product research, case preparation, marketing, and operational follow-through. The advisor keeps the client relationship; FIG supplies some of the machinery around it.
That machinery matters because retirement planning crosses boundaries. An income question can become an annuity question. A discussion about family responsibilities can become a long-term care question. A small advisory practice may need expertise in each without enough work to employ a specialist in every category. FIG pools that expertise across a network it says exceeds 3,000 financial professionals.
Its core offerings include fixed and fixed indexed annuities, life insurance, care planning, and disability income solutions. Marketing and branding services address another constraint: finding clients in the first place. Business development resources extend to hiring and succession. In the interns’ account, senior vice president Leslie Lipscomb supplied a compact explanation of the sales culture:
“Relationships are my superpower.”
Leslie Lipscomb · FIG senior vice president
This helps explain the word marketing in the company’s web address. Distribution involves more than making products available. Advisors also need ways to attract prospects, explain unfamiliar products, and organize follow-up. Sharing those capabilities can reduce the number of separate vendors a practice has to coordinate. Their usefulness still depends on execution inside the advisor’s own firm.
Three people share the corner office
FIG’s own succession provides a useful wrinkle. William Cain founded Cain and Associates in 1976. An acquisition brought the Financial Independence Group name in 1987. In November 2019, Bill and Ericka Cain moved into Founder roles while Jim Cooper, Mike Mullan, and Brian Williams became co-chief executives. The founders explained that consensus had long guided their decisions.
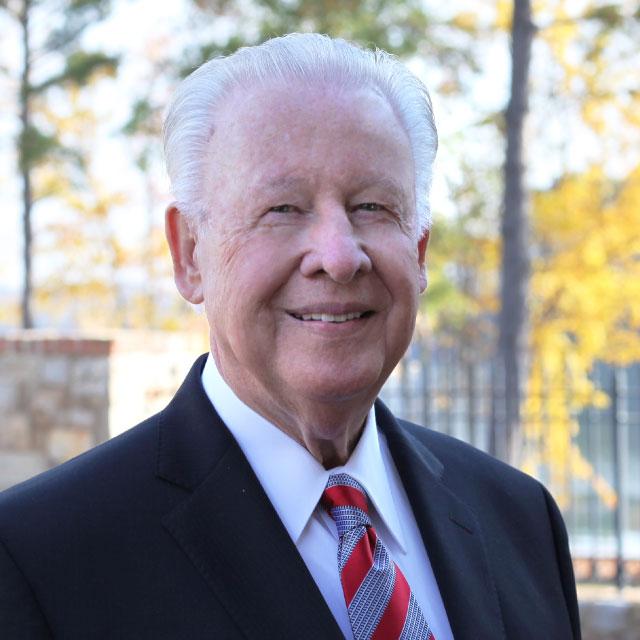
The arrangement makes more sense when independence is treated as an ownership and succession problem. FIG wanted leadership continuity without abandoning its structure. Its public materials explicitly connect succession planning with preserving independence. Three executives sharing authority is an unusual expression of the same proposition it offers advisors: keep your identity, assemble support around it.
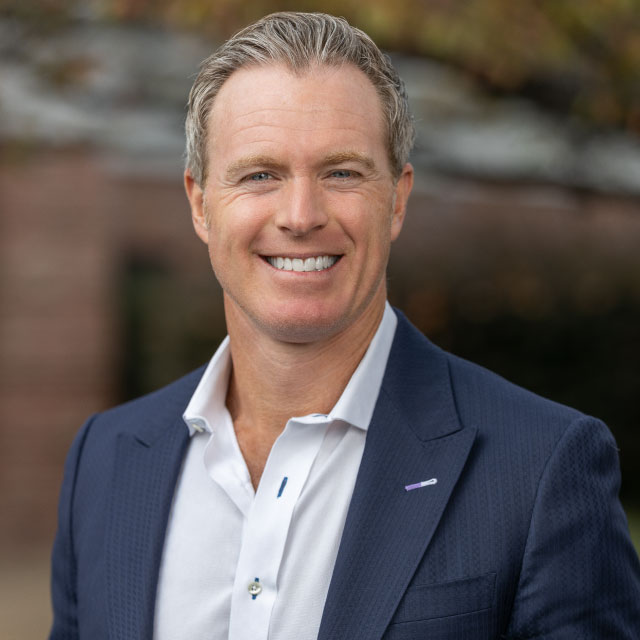 Jim Cooper
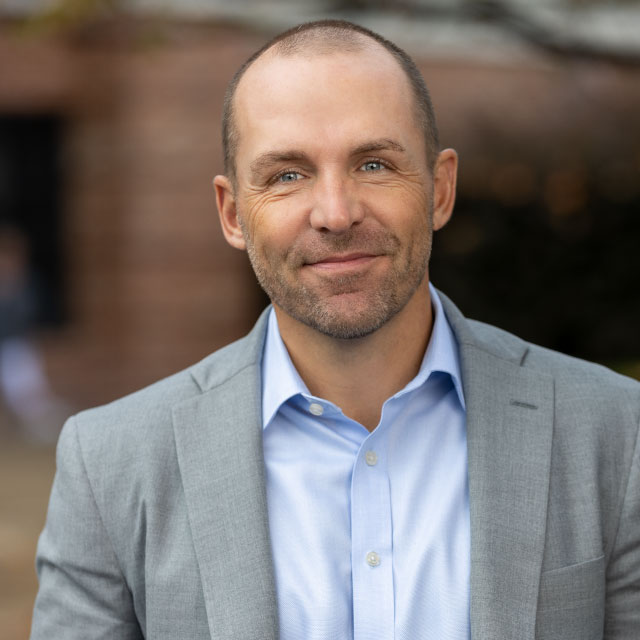 Mike Mullan
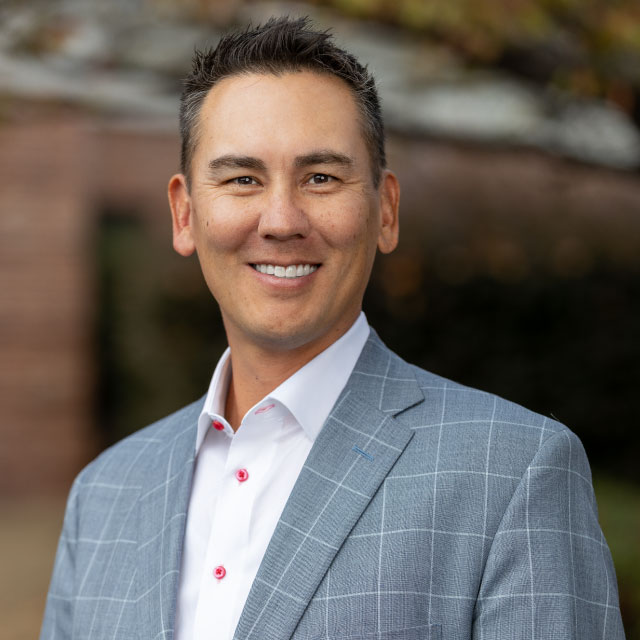 Brian Williams
The trouble lives between the tabs
Consider what follows a product recommendation. Someone must obtain illustrations, prepare the application, resolve missing information, track issuance, and eventually service the policy. Each handoff can mean another website, another login, another call. FIG’s technology partnerships concentrate on those seams.
A December 2023 collaboration brought Luma’s annuity technology into the picture. FIG introduced Lifecycle Manager in August 2024, describing policy information consolidated from more than 40 carriers, with customizable views and reporting. That figure described the feeds available at introduction; it did not mean every carrier or policy was covered.
- 01Find the fitResearch · compare · illustrate
- 02Build the casePrepare · apply · submit
- 03Close the gapsTrack · correct · issue
- 04Keep watchingMonitor · service · review
A workflow map, not a measured performance chart.
In April 2026, FIG became the launch partner and first live client for Luma’s life insurance platform. The workflow connected discovery, quotes, illustrations, electronic applications, placement, and ongoing management, including integration with iPipeline. FIG’s David Henry said earlier solutions had disappointed on value and ease of use. That is a specific account of what needed fixing: the experience of getting the work done.
September supplied an even more concrete example. The Standard connected FIG through Magnifact’s platform, using common industry interfaces for application and activity status. Teams could receive pending-annuity updates inside their own systems, including information about incomplete applications. A missing item could become visible where staff were already working.
Buying expertise, keeping the relationship
The same logic explains FIG’s partnership choices. Waterlily, announced in May 2024, adds personalized projections for long-term care needs and costs. Its role is to make a difficult planning conversation more concrete. The projections remain estimates, requiring judgment about the family and its circumstances.
Power of Zero adds a different kind of expertise: retirement tax-planning education, events, and case design. In November 2024, FIG announced an exclusive relationship and an equity stake after roughly 15 years of working together. A Holistiplan discount partnership had already added tax-planning software in 2021. FIG’s pattern is to connect outside capabilities to an existing advisor network.
People remain part of the investment. In September 2025, FIG announced a multi-year partnership with FinServ Foundation to support its fellowship and emerging-talent work. That commitment sits alongside FIG’s own internship rotations. Learning the organization means seeing the connections between departments, including the operational work that can otherwise disappear behind the person who makes the sale.
Follow the money, then the missing information
The economics deserve attention. Alphastar’s public disclosure describes carrier-paid commissions and overrides in the distribution chain, alongside production-linked marketing credits and other incentives. Support and compensation can therefore be connected to sales activity. FIG’s portal terms also assign responsibility for any incurred fees to the user or organization. An advisor comparing arrangements needs the actual contract, service charges, and compensation terms.
Alternatives include other distributors such as Advisors Excel, Simplicity, and AmeriLife. FIG’s proposition is the combination of specialist people, practice support, and increasingly connected software. Whether that combination helps depends on the advisor’s product needs, carrier relationships, and existing staff. A firm with established operations may value a different mix from a solo practitioner.
A useful evaluation starts with a real case: which carrier is available, who prepares the paperwork, where updates appear, and who handles the next review. That exercise makes the service tangible before a practice commits more of its workflow.
There is a practical limit to the technology story, too. In October 2026, FIG appeared among distributors urging carriers to adopt common data standards more widely. Better tools still depend on other organizations sharing usable information. The lesson a reader can copy is modest and useful: map the handoffs, locate the repeated chasing, and connect those steps first. The interns may have ruled out operations. FIG’s next chapter suggests they were looking at exactly the right department.