The frown line is small. The business built around it is considerably larger. Evolus arrived with Jeuveau, a prescription rival to Botox Cosmetic, and a proposition that sounded more like a beauty company than a drug company: make the brand desirable, make purchasing easier and give patients a reason to return. Then it added fillers. The ambition now extends well beyond the space between two eyebrows.
There is real business beneath the branding. Evolus generated $297.2 million in revenue in 2025, its sixth consecutive year of double-digit growth. Yet it also posted a $51.6 million net loss. That pairing captures the company better than either its coral butterfly or an upbeat earnings headline: it has established demand, while the economics of serving that demand remain a work in progress.
01The beauty counter meets the treatment room
Evolus occupies a particular corner of healthcare: elective, cash-pay aesthetics. Its direct customers are practitioners and aesthetic businesses; the people receiving injections are the consumers those practices must attract and retain. A product has to win two decisions. The injector must want to use it, and the patient must want the treatment enough to pay out of pocket.
Jeuveau, or prabotulinumtoxinA-xvfs, temporarily improves moderate to severe frown lines in adults. It is a botulinum toxin product, not a dermal filler. Evolysse Form and Smooth are hyaluronic acid gels approved for injection into or beneath the skin to correct specified facial wrinkles and folds, including nasolabial folds, in adults aged 22 and older. They give practitioners another treatment category, rather than another name for the same procedure.
That distinction matters in a market containing Botox Cosmetic, Dysport and Xeomin on the toxin side, and Juvéderm and Restylane among fillers. Evolus competes through its aesthetic-only positioning, product evidence, commercial terms and practice support. A consumer-friendly identity does not make the products interchangeable. Jeuveau’s label explicitly says its potency units cannot be converted into those of other botulinum toxin preparations.
Temporarily reduces the appearance of adult frown lines through its effect on muscle activity.
Injectable material for correcting approved facial wrinkles and folds. A different tool for the practitioner.
02The first obstacle was the paperwork
Incorporated in 2012, Evolus secured rights to Daewoong’s toxin and was acquired by Strathspey Crown in 2013. Scott Cannizzaro is identified as a co-founder in Wharton alumni news. David Moatazedi, the executive now associated with its commercial identity, arrived as chief executive in May 2018 after a career that included running Allergan’s U.S. medical aesthetics business. The challenger hired someone who knew the incumbent’s territory.
The IPO that February initially raised $60 million before fees and expenses. The product was still awaiting approval. In May, Evolus reported an FDA complete response letter concerning chemistry, manufacturing and controls. Its first major public regulatory setback concerned the application’s manufacturing-related material. Jeuveau ultimately received FDA approval on February 1, 2019, and launched that May.
A more expensive complication followed: intellectual-property litigation involving Daewoong, Medytox and Allergan. A February 2021 settlement allowed Evolus to continue commercializing its toxin. The arrangements included $35 million in cash payments over two years, royalties and roughly 6.8 million shares issued to Medytox. A separate Daewoong agreement provided $25.5 million to Evolus and other relief. These were distinct transactions, not a single tidy legal bill.
For a company built around one licensed product, the lesson was unusually concrete. Access to a supplier’s medicine includes exposure to disputes around that medicine. Consumer marketing cannot repair an interrupted right to sell.
03A second box on the same order
The 2023 Symatese agreement gave Evolus a route into fillers without building the underlying manufacturing business. Its original U.S. terms called for €16.2 million in payments, including €4.1 million upfront, plus a mid-single-digit royalty and a product transfer price. Evolus planned to finance the transaction and related work through an available $50 million debt tranche. The price of entry extended beyond the signature on the contract.
The commercial argument was straightforward: existing representatives, ordering systems, rewards and practice relationships could support a second category. More products could make each customer relationship more valuable without requiring the business to start again. Moatazedi described the goal when the agreement was announced:
“transforming Evolus into a multi-product aesthetics company”
DAVID MOATAZEDI · MAY 2023
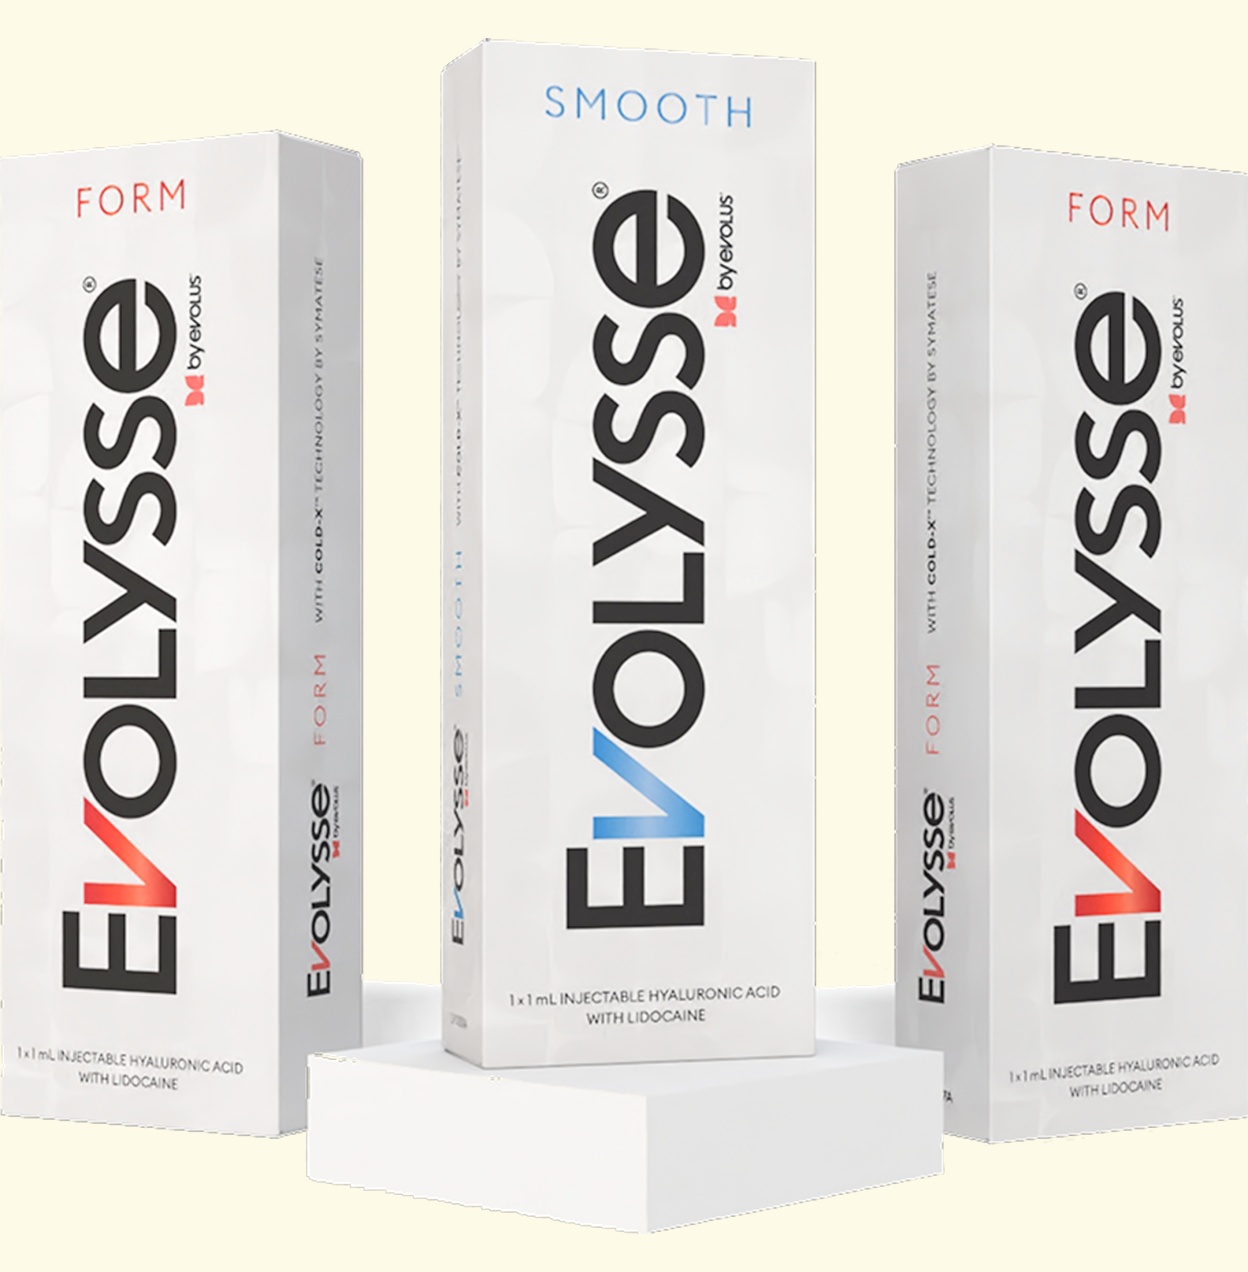
Evolysse Form and Smooth won FDA approval in February 2025 and launched in April. Symatese’s Cold-X technology is designed to preserve the structure of hyaluronic acid during production. The U.S. pivotal study involved 140 patients in a randomized, blinded, split-face comparison with Restylane-L. Both products met the primary non-inferiority endpoint. Such a comparison is more informative than a packaging claim, though it does not establish superiority over every filler for every patient.
For patients, the practical benefit is another professionally administered option. For Evolus, it is an opportunity to sell more through relationships already won. The two propositions overlap, but they are not identical: a practitioner still has to decide which treatment fits the person in the chair.
04A $49 price tag with a 90-day clock
Club Evolus turns the repeat appointment into a recurring payment. The advertised charge is $49 every 30 days. After three payments, a member becomes eligible for a 20-unit Jeuveau treatment at a participating practice; prepayment can bring that first treatment forward. Further treatments require at least 90 days between visits. The subscription concerns a defined treatment benefit, not unlimited injections.
20 units of Jeuveau per eligible treatment
Minimum 90 days between treatments
The small print changes the value calculation. Unused units do not accumulate when a member waits longer. Additional treatments are paid to the provider separately, and joining Club Evolus opts a patient out of Evolus Rewards. Someone who prefers occasional treatment should examine that schedule carefully. A monthly price can look modest while buying something the customer does not use often enough.
There was an experiment before the rollout. Forbes reported a year-long pilot involving 250 patients at five practices; Moatazedi said about 90% renewed. That is an encouraging company-reported result from a small selected group, not a promise about every clinic. The useful idea to copy is the test: learn whether a payment plan changes return visits before extending it across a network.
05The forecast got a reality check
The filler deal originally accompanied a $700 million revenue target for 2028. By March 2026, management had reduced that ambition to $450 million-$500 million, citing a more conservative U.S. market outlook. A new product can enlarge the addressable market without making that market grow at the speed a forecast assumes.
The adjustment had operational consequences. Evolus took expense-reduction measures in August 2025 and recorded $1.4 million in restructuring costs, primarily one-time severance benefits. The company’s third-quarter commentary emphasized lower costs alongside continued sales growth. This was a change in spending as well as language.
The latest reported quarter offers progress with qualifications. In August 2026, Evolus reported second-quarter revenue of $84.1 million, up 21%, and $4.7 million in adjusted EBITDA. It also reported a $4.5 million GAAP operating loss. Management raised the bottom of its full-year sales range to $330 million, leaving the upper end at $337 million. Adjusted earnings and accounting profit are answering different questions; readers need both.
The customer numbers also need their labels. More than 18,600 customers had purchased since launch by June 2026, and Evolus Rewards had passed 1.5 million enrollments. Those cumulative totals describe reach. They should not be read as the number of practices ordering this quarter or patients currently paying a subscription.
06Coral outside, clinical work inside
Evolus’s culture page has little patience for pharmaceutical solemnity. It promises catered meals, learning opportunities and even occasional ice cream taste tests. “Our culture is our secret weapon,” the page declares. That is the employer’s own account, but the presentation is revealing: the consumer brand and the recruitment pitch speak a similar language.
Behind the cheerful portraits, the work requires clinical development, regulatory knowledge, practitioner education and reliable distribution. Jeuveau carries a boxed warning about the distant spread of toxin effect, including potentially life-threatening swallowing or breathing difficulties. A loyalty program cannot determine medical suitability. The practitioner’s judgment remains central, however breezy the checkout experience becomes.
That is also a boundary on the business model. Aesthetic medicine depends on people who can afford elective care, clinicians willing to adopt the products and patients satisfied enough to return. Rewards may support those relationships. They cannot substitute for them.
07The next deal comes with homework
In July 2026, Evolus agreed with Switzerland’s IBSA to develop and commercialize Profhilo in the United States. The product targets skin quality, adding another proposed category beside toxins and fillers. The agreement required no upfront payment and used a transfer-price model. Evolus, however, took responsibility for the work required to secure U.S. regulatory approval. An inexpensive signature is not the same as a costless launch.
Internationally, the company has used Nuceiva for its toxin and Estyme for HA gels. It expanded its Symatese agreement in August 2026 to include Canada, Australia and New Zealand. Distribution rights create an opportunity; local approvals and commercial execution still determine when that opportunity becomes a treatment someone can buy.
08Copy the relationship before the subscription
The transferable idea is to make the next product useful to the customers already buying the first. Evolus’s filler expansion has that logic: a practitioner relationship, an ordering system and a consumer audience can serve more than one approved treatment. The membership experiment adds a second lesson about testing the frequency of demand before designing recurring charges around it.
The conditions are demanding. Products must meet real clinical needs, suppliers must deliver, practitioners must reorder and patients must keep choosing elective care. If any of those assumptions weakens, more promotion can mean more expense rather than more profit. Evolus has made itself a participant in the injectables business. Its next achievement has to show up after the costs are paid.