On October 2, 1930, eighty-six people became members of a credit union organized by the management of Eli Lilly and Company. The first branch was inside Lilly Corporate Center. There is something revealing about that address. A person worried about money could find help in the same place they went to earn it. During the Great Depression, Lilly management wanted to protect employees from street lenders and loan sharks. The solution began with proximity: put a different kind of lender within reach.
- A member-owned credit union offering everyday banking, loans and financial guidance.
- Employer relationships bring the service into the benefits package.
- Shared branches and digital banking extend access beyond Indiana.
Today, that institution is Elements Financial. Its product list looks familiar: checking, savings, mortgages, car loans, credit cards. The more interesting question is how a financial institution built around one employer learned to serve people far beyond it, while keeping the workplace at the center of its approach.
01 The workplace was the distribution plan
In 2008, the credit union launched At Work Financial Services. It offered other companies the banking relationship developed for Lilly employees. The annual report made a straightforward pitch: employers could add the service without extra cost, while workers gained a convenient way to handle money. Four new companies joined its field of membership that year, alongside a fifth, larger corporate relationship.
This was a decision about where to find customers. An employer already had a relationship with people who needed mortgages, savings accounts and advice. Financial education could arrive alongside the benefits people were already learning to use. For a service business, the lesson is transferable: find the existing gathering place, then make the next useful action easier.
The name eventually caught up with the audience. On January 6, 2015, Eli Lilly Federal Credit Union became Elements Financial. By then, a name tied to one company had to represent a broader membership. The chemistry reference preserved a little of the old connection.
Reaching that wider audience carried a marketing bill. In November 2015, the Indianapolis Business Journal reported a naming-rights agreement for the Blue Ribbon Pavilion at the Indiana State Fairgrounds: $80,000 a year for five years. That was one visible expense in the broader campaign. A business can extend its service through partners, but it still has to explain its new name to people who have never walked through the original employer’s gates.
02 Borrow the network
Physical closeness becomes harder when members move. Elements addresses that problem partly by sharing infrastructure. Its 2026 careers page lists four proprietary branches, all in Indiana, alongside access to more than 5,600 shared branches nationwide and 85,000 surcharge-free ATMs globally. Those are different kinds of access, and the distinction matters.
in Indiana
nationwide
Participating locations, not Elements-owned offices. Access figures reported on its 2026 careers page.
The shared counter belongs to another participating institution. Members should check the locator for the services they need. Two of Elements’ own branches, at Lilly facilities, require an active employee badge. Anyone choosing a primary account around a convenient lunch-hour visit should check which doors they can actually open.
For someone comfortable banking by phone and using participating locations, this arrangement offers a useful compromise. A customer who wants a nearby Elements branch for every problem may find the footprint restrictive. The network solves distance better than it solves a preference for one familiar teller.
03 A $5 doorway, with details attached
The membership ritual is modest. Elements says it puts $5 into a Member Savings account to get a new member started. The account has no monthly maintenance service charge. Earning dividends requires a minimum daily balance of $100. These details explain why the account is an entry point; a larger savings balance deserves its own product comparison.
Beyond that doorway sit certificates, IRAs, home equity borrowing and commercial banking. The range lets members handle several financial needs with one institution. Elements’ cooperative structure is intended to return value through rates and fees, although a member still needs to compare the particular account or loan being offered. Deposits help fund lending; loan interest and other operating income support the institution. The ownership model changes who the business serves, while leaving the ordinary demands of running a lender very much in place.
The quieter service is free, confidential credit counseling: a credit-report review, help building a budget and an action plan. The review uses a soft inquiry that does not affect the credit score. Investment advice is available through Elements Wealth Management’s LPL Financial representatives. Those securities and insurance products are separate from credit union deposits, are not NCUA-insured, and can lose value.
04 One app, a little homework
In September 2026, Elements brought more of the relationship into a consolidated digital banking experience. Card controls joined account management. Members could use savings goals, spending forecasts and secure access for a trusted person without handing over their own credentials.
The transition also required effort. Current tutorials tell members to recreate alerts, card controls and budgeting settings. Retail desktop remote check deposit was retired in favor of mobile deposit. A cleaner interface can still impose a switching cost on someone whose old routine worked perfectly well.
“Scams today are sophisticated, emotional, and constantly changing.”
Charlie Clarke, Chief Information Officer · March 2026
Security adds another reason to keep adapting. In March 2026, Elements joined the National Member Protection Initiative with Charm Security and Curql Collective. The program brings credit unions together around scam prevention, education and emerging approaches to protection. Participation establishes a commitment to the work; it does not establish a measured reduction in fraud losses.
05 Put the promise on the calendar
Elements’ community activity has some measurable edges. Employees receive eight hours of volunteer paid time off each year. The company reports 1,104 employee volunteer hours in 2024. Purpose Day turns volunteering into a scheduled company event, with teams working on projects selected with local nonprofits.
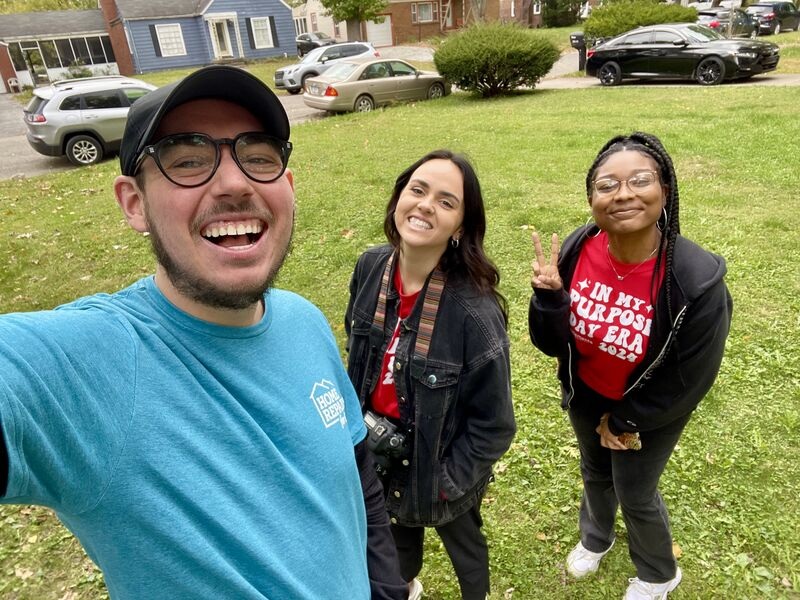
In December 2025, Elements announced $100,000 in grants to four organizations. One $27,500 award had an unusually concrete purpose: help Englewood Community Development Corporation furnish eleven housing units for families transitioning out of homelessness. The stated use makes the promise easier to picture, and later to assess.
That specificity is what a prospective member can borrow. Compare the actual fee. Locate the actual counter. Ask what the counseling session includes. Elements’ long-running idea becomes useful at that scale: a financial relationship close enough to make the next decision a little less difficult.