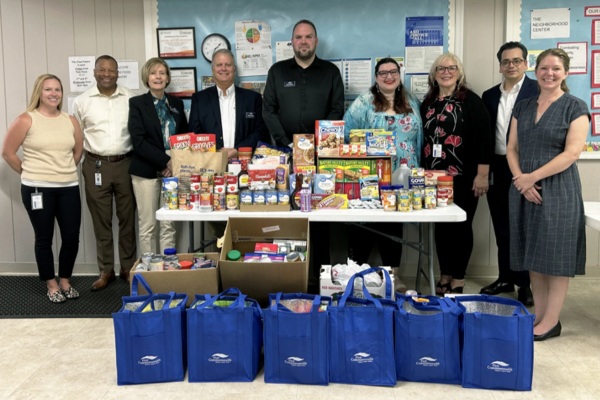
In Easton, Pennsylvania, First Commonwealth Federal Credit Union opened a financial center with an unusual feature: it was cashless. The setting was the Easton Area Neighborhood Center, a nonprofit with a food pantry. The offering was financial guidance. In a business measured in dollars moved, here was a place organized around a conversation.
- Member-owned banking for households and businesses in Pennsylvania and New Jersey.
- Everyday accounts and loans, with free financial counseling alongside them.
- Digital convenience, local locations, and specialized services for cannabis businesses.
The choice of location matters. A person worried about groceries may also be worried about a credit card balance. Putting guidance inside an existing community institution brings those concerns into the same room. It is a useful way to understand First Commonwealth: the familiar banking menu, delivered with deliberate attention to the person trying to use it.
A basement with a $200 ceiling
In 1959, the institution was called WeAllen Federal Credit Union. It served Western Electric employees in Allentown from the basement of the company’s Union Boulevard building. Its modest menu included savings accounts and loans up to $200. Opening hours were limited. The customers already shared an employer; the cooperative gave them another thing to share.
During the 1980s, membership expanded to employees of other Lehigh Valley companies. In the 1990s, the name became First Commonwealth, reflecting a membership that had outgrown its original identity. That history explains the institution’s position today. It operates between the narrow workplace cooperative it once was and the broad financial supermarket a household now expects.
The customer gets a vote
First Commonwealth is a not-for-profit financial cooperative owned by its members. A member-elected volunteer board governs it. Members have equal voting standing, rather than influence determined by how much bank stock they own. Earnings support the institution, its products, member pricing, and community programs. The ownership structure changes whose interests management is supposed to serve.
It still has to earn money. Deposits support lending and investments; interest income and service charges help pay the bills. In 2025, operating expenses were about $56.9 million, including roughly $29 million in employee compensation and benefits. The credit-loss provision was another $10.5 million. Cooperative ownership does not make staffing, technology, buildings, or bad loans disappear.
“Our mission goes beyond banking”Donna LoStocco, President & CEO
June 2025 community announcement
A household can grow into the menu
The consumer offering stretches from youth savings and teen checking to auto loans, mortgages, home equity, credit cards, HSAs, and IRAs. A family can start with ordinary bill-paying and later seek financing for a car or home. Investment planning is available through LPL Financial representatives; those securities are separate from insured credit union deposits and can lose value.
The app handles much of the routine work: check deposits, bill payments, transfers, card controls, and alerts. Direct-deposit distribution can move a paycheck into different First Commonwealth accounts. Linked financial tools help members examine spending and debt. These are practical capabilities, although the tutorials specify that mobile-deposit enrollment requires at least 60 days of membership.
Cashback Checking adds an incentive to consolidate activity. Its three tiers reward qualifying purchases and eligible loan payments. Higher tiers require more transactions and additional conditions, including direct deposits and electronic statements. The top tier also requires an eligible active loan and other account activity. Rewards are capped at $50 monthly across purchases and loan payments; transactions below $10 do not qualify.
That is where a useful comparison begins. Someone who already meets the conditions may value the rewards. Someone who would need to rearrange their finances should calculate the benefit first. The advertised maximum is a ceiling. It is not a forecast of what an individual member will receive.
The small business has a different problem
For a business owner, the bottleneck may be collecting payments or giving an employee limited account access. First Commonwealth offers business checking, term loans, credit lines, commercial real estate lending, and digital cash management. ACH payments, remote deposit capture, domestic wires, accounting exports, and separate employee permissions address the daily mechanics. Some services carry fees.
Its cannabis offering makes the specialization explicit. Eligible dispensaries, medical marijuana distributors, hemp businesses, laboratories, and other operators in Pennsylvania and New Jersey can seek deposit services, cash management, and business lines of credit. Here, the competitive proposition is concrete: a financial institution willing to build an offering around a particular customer’s operating needs.
Growth has a conversion cost
Expansion creates its own chores. The Bellco merger completed on June 1, 2024, adding Sinking Spring and Wyomissing locations. The conversion guide told members that credit card numbers would change. Borrowers paying automatically from another institution needed to update routing and loan numbers. A larger network arrived with a household administration project attached.
The same year, First Commonwealth’s leadership described persistent high interest rates and rising defaults as financial pressures. Those details temper the growth story. More locations do not remove credit risk, and a broader membership does not spare members the friction of changing systems. Good execution includes explaining those transitions precisely enough that people can complete them.
An algorithm, then a person
First Commonwealth joined Upstart’s referral network in December 2024, announcing the partnership the following April. Eligible personal-loan applicants receive offers and move into a First Commonwealth-branded membership and closing process. Its lending chief described the goal as reaching more creditworthy borrowers, including people with lower and moderate incomes, while connecting them with financial counselors. Approval remains conditional.
The lesson others can copy is operational: pair a transaction with help using it, and put that help somewhere people already go. First Commonwealth’s free wellness tools, counseling, and GreenPath relationship give members several starting points. For a prospective member, the first steps are equally specific: check eligibility, compare the complete fee and loan terms, and book a counseling conversation. Membership starts with a $5 savings deposit. The next useful number may come from understanding the budget.
Keep exploring
Go straight to the useful bits.