The sign outside the branch at 56 Haddonfield Road said Bethpage. The address was in Cherry Hill, New Jersey. That small mismatch captures the problem facing a credit union with roots in an aircraft factory and ambitions well beyond Long Island: a familiar name could tell a stranger the wrong thing.
- Bethpage became FourLeaf on March 3, 2025. It remained the same credit union.
- Membership is available nationwide, subject to approval and a maintained $5 savings account.
- Its appeal combines cooperative ownership, everyday banking and access through shared credit union networks.
For existing members, Bethpage carried history. For people unfamiliar with it, the name apparently carried a boundary. The institution’s surveys found that people perceived it as small and local, available only if they lived or worked nearby. The organization had widened its reach. Public understanding had lagged behind.
01 / A name with an invisible fence
In November 2024, Bethpage announced that it would become FourLeaf. Research involving members, nonmembers and employees helped inform the decision.
“the Bethpage name, while so close to our hearts, was limiting.”Linda Armyn / President & CEO, November 2024
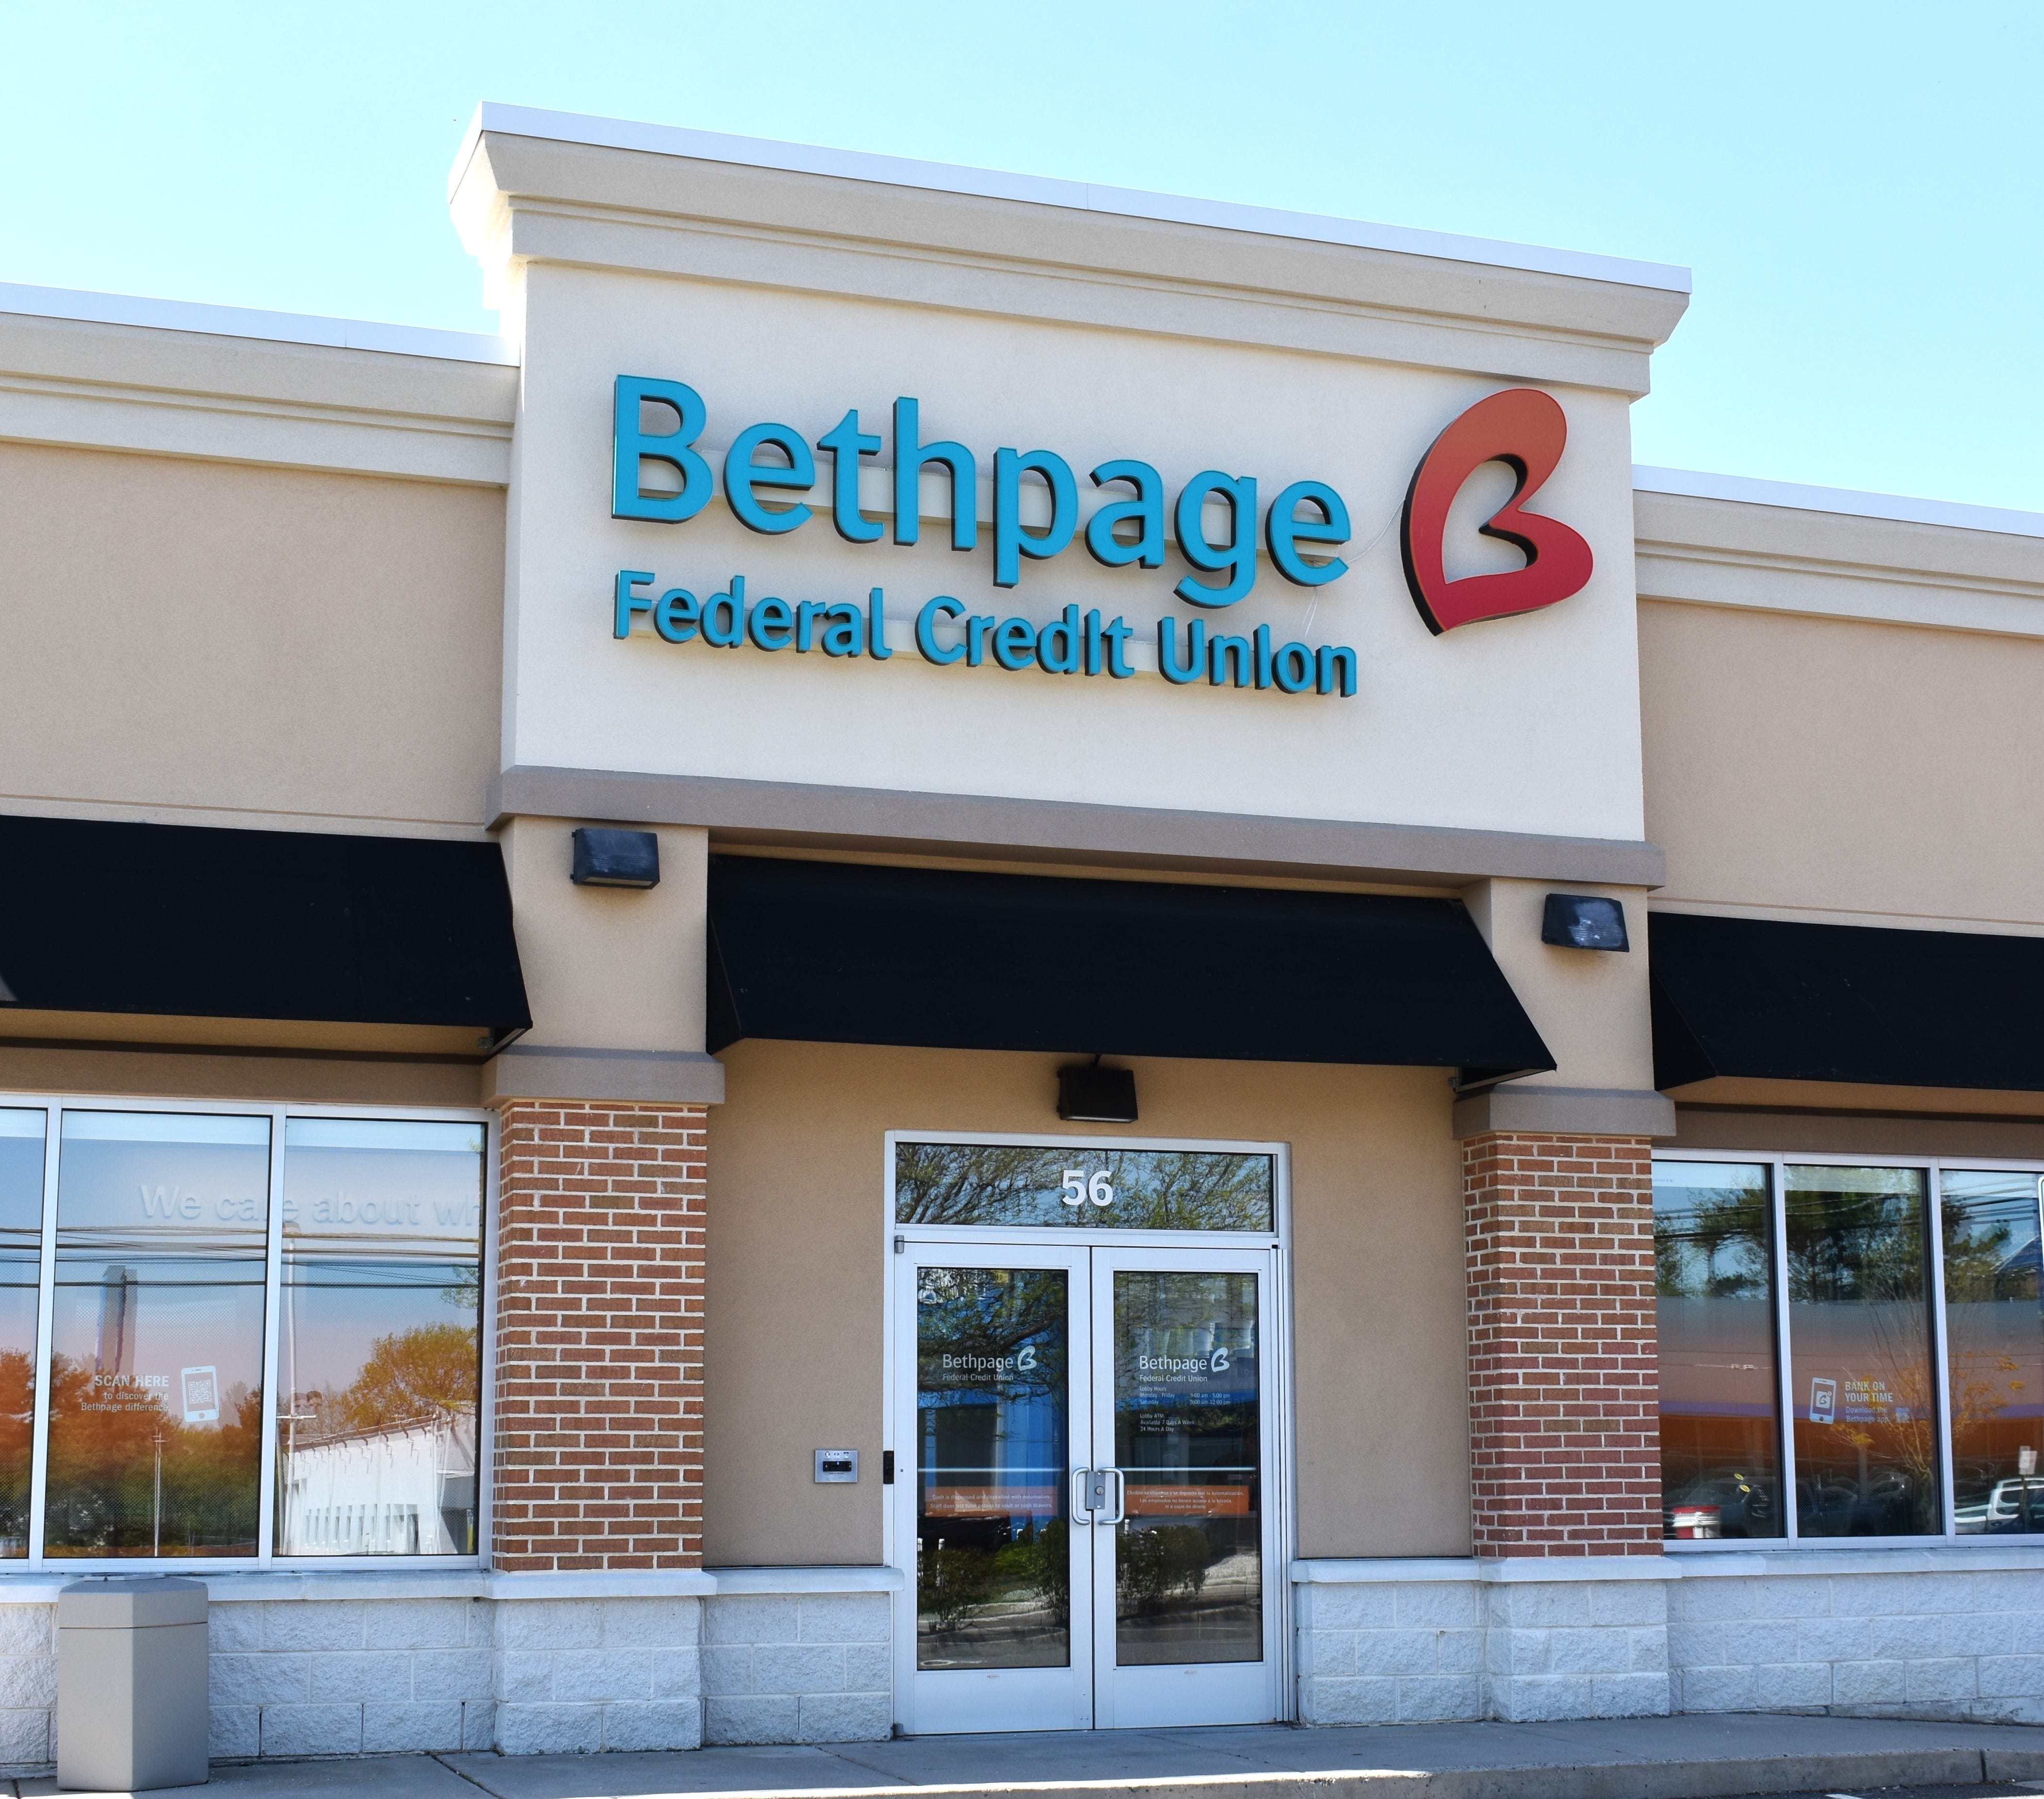
The change became official on March 3, 2025. Account numbers, usernames and passwords stayed the same. Existing loan and bill payments continued. The credit union explicitly said the rebrand did not result from a merger or acquisition. That continuity mattered: a new identity would be a nuisance if members had to rebuild their financial routines around it.
Orange survived from the Bethpage identity; a deeper blue nodded to the Grumman connection. Two intertwined infinity symbols formed the new mark. The operational promise was more interesting than the symbolism: make the institution easier for newcomers to understand while preserving the working relationship existing members already had.
02 / The factory keeps getting bigger
In 1941, the institution opened as Grumman Plant 1 and 2 Federal Credit Union, serving aircraft employees. It began with 114 members. The original proposition was practical: give workers a financial alternative for managing their earnings. Its history is a sequence of expanding circles, each one making the original audience less representative of the whole.
employees
Suffolk
eligibility
A community charter widened membership across Nassau and Suffolk counties in 2003. The 2016 acquisition of Montauk Credit Union brought an open charter and nationwide eligibility. Cherry Hill became its first branch outside New York in April 2024. By January 31, 2026, FourLeaf reported 517,393 members and $14.2 billion in assets.
Those assets are a balance-sheet measure, not a price tag or a venture valuation. This is a member-owned, not-for-profit cooperative. Its bylaws describe a volunteer board and a mission of meeting members’ credit and savings needs, especially those of modest means. The $5 savings requirement establishes a continuing membership stake.
03 / Follow the money, then the fine print
The product menu looks familiar: checking and savings, money market accounts, certificates, mortgages, home equity lines, auto loans, personal loans and credit cards. Families can open a child’s savings account; small businesses can use deposit accounts, payment services and borrowing facilities. Financial planning extends the relationship into college, investments and retirement.
The difference lies partly in where earnings go. FourLeaf earns interest on loans and investments, pays for deposits and borrowing, and collects fees and commissions. In its audited 2025 accounts, total interest income was $701.020 million. Dividends on members’ shares were $295.979 million. Net income, after expenses and credit-loss provision, was $68.020 million.
Dividends on members’ shares
$68.020mNet income retained in the business
The institution also spent $32.073 million on education and promotion, compared with $25.896 million in 2024. These are broad expense categories, so treating the increase as the cost of changing the name would be misleading. What the accounts do show is that cooperative banking still pays for staff, technology, premises and attracting customers.
Ownership alone cannot settle a product comparison. FourLeaf’s Free Checking dividends require direct deposit, ten posted point-of-sale debit purchases each month, and online banking with eStatements. Miss the qualifying requirements and that month earns no dividends. A saver who will not use the debit card that often needs to judge the account accordingly.
04 / Borrowing a bigger footprint
National availability raises an obvious question: where does a member go? FourLeaf participates in networks offering more than 30,000 surcharge-free ATMs and over 5,000 shared branches for basic transactions. These are network locations, rather than thousands of buildings owned by FourLeaf. Members need participating locations; an unrelated ATM can still charge its owner’s fee.
Digital banking handles another part of the distance: account access, check deposits, transfers and card controls. Its tutorial library includes demonstrations of registration, alerts and locking a card. For someone comparing it with a neighborhood credit union or a national bank, the useful test is whether those actual transaction routes match everyday life.
05 / Keep something worth being local for
Local usefulness remains visible in less glamorous work. FourLeaf reports approximately $2 million in community donations, over 150 free financial education seminars and more than 6,900 employee volunteer hours in 2025. Its tax-assistance program prepared 1,005 returns that season, helping taxpayers receive $1,151,875 in refunds. These activities make community commitment observable.
The educational effort is evolving, too. A September 2026 collaboration with Jean Chatzky’s HerMoney adds resources to Money Like A Woman. In October, a partnership with Northwell’s Katz Institute for Women’s Health brought breast-health education into its community outreach. Both extend the institution’s relationship with people beyond a single account.
The lesson for another organization is specific: ask prospective customers whether they think your service is meant for them. A changed name helps when it corrects a real misunderstanding and the service can support the wider promise. At FourLeaf, the enduring test is ordinary: can the person walking through the door get useful banking on terms that fit?
Official website ↗ · Checking terms ↗ · Newsroom ↗ · Member newsletter ↗
LinkedIn ↗ · X ↗ · Instagram ↗ · Facebook ↗ · TikTok ↗