The first obstacle is the name. NASA Federal Credit Union sounds like a place where someone might ask for a security badge before discussing your checking account. Yet its membership page offers a remarkably accessible route: a complimentary, one-year affiliation with the National Space Society. Open a savings account with at least $5, complete the application, and the institution with the specialized name becomes a possibility for an ordinary household.
That small detail changes how the whole business reads. A credit union rooted in a scientific community now serves consumers nationwide. The interesting question is how an institution built around belonging makes itself useful to people who live far beyond its original circle.
- You can qualify without working for NASA.
- Membership starts with a $5 savings deposit; services can carry separate fees.
- Mobile banking extends its reach; business lending remains regional.
The name on the door
Begin in 1949. Seven members of the scientific community started the credit union with $2 in deposits. NASA itself opened in October 1958. There is something pleasantly backward about this chronology: the financial institution predates the space agency whose name makes it recognizable.
The connection became part of its visual identity, too. NASA’s official history of its emblems records the credit union’s approved use of a blue version of the agency’s worm logotype. The space association is real, with paperwork behind it.
Today’s customer list stretches from NASA employees and retirees to partner-company employees, relatives, household members and people qualifying through the society affiliation. In July 2026, NASA Federal reported more than 238,000 members and approximately $5.7 billion in assets. Those are dated figures, but they establish the scale: this is a substantial lender wearing a club’s name.
Five dollars buys a share
The word “member” has a precise meaning here. A federal credit union is a cooperative owned by its members. A savings deposit establishes that relationship; voting power follows membership, with one vote per member. A larger balance does not buy a louder vote.
Member deposits help fund loans and investments. Interest income and service charges support operations, reserves and member benefits. The institution still needs earnings, sound underwriting and enough capital to absorb losses. Its ownership structure changes who the enterprise serves and how its surplus can be used.
The practical offering is familiar: checking, savings, money markets, certificates, car loans, personal credit, mortgages and home-equity financing. Financial planning extends the relationship into retirement, college savings and estate strategies. Securities and advisory services come through LPL Financial; those investments can lose value and do not carry NCUA deposit insurance.
The phone had to catch up
For a national membership, the phone becomes a particularly consequential branch. According to Alkami’s account of NASA Federal’s earlier setup, mobile and desktop banking differed in appearance and functionality. Integrating outside vendors also demanded substantial internal development. A familiar name could bring someone to the door; inconsistent software complicated what happened next.
NASA Federal launched its Alkami platform in November 2023. Preparation included employee training and member communication. The selection emphasized consistent access across devices, easier integrations and continuing feature releases. In a November 2024 case study, Alkami reported that the mobile app’s rating had moved from 1.3 to 4.9. That is a partner-reported historical comparison, rather than proof that every member’s experience improved equally.
Ratings out of 5. Historical comparison reported by Alkami, November 2024.
“Finding good software is not difficult.”
Liam Petraska, Digital Banking Manager, in Alkami’s case study
Look past the rating and the features become more revealing. Members can lock a card, photograph a check for deposit, set alerts and view a credit score. In January 2025, Alkami announced push provisioning, allowing members to use eligible cards digitally while the physical card was still in the mail. It solves a small, recognizable irritation: waiting for an envelope before being able to pay.
There is a useful operating lesson here. Select a platform around recurring member tasks, prepare the people who must explain it, and measure what happens after launch. NASA Federal’s 2026 digital-transformation recognition at Alkami Co:lab adds an industry accolade. The more persuasive detail remains the task a member can finish.
The less visible work happens behind the account screen. In July 2026, NASA Federal announced a Celent risk-management award for modernization using DataVisor. The credit union reported a 41% reduction in manual review time and fewer anti-money-laundering false alarms after bringing fraud and compliance signals together. These are company-reported results. Their relevance is practical: an institution serving members remotely must also handle the suspicious transactions that arrive remotely, without making every legitimate transaction harder.
The price of everyday banking
The $5 deposit is an entry requirement, not the total price of banking. NASA Federal’s October 2026 fee schedule lists Everyday Checking at $8 a month, waived with a $200 average daily balance or at least $500 in monthly direct deposit. Premium costs $7 monthly; Elite costs $10. Those paid tiers bundle additional benefits. Whether the bundle earns its keep depends on what a household actually uses.
| Account | Monthly fee |
|---|---|
| Everyday | $8 Waiver conditions apply |
| Premium | $7 |
| Elite | $10 |
Savers face a different calculation. Certificates exchange access to money for a defined term and fixed yield; early withdrawal penalties can reduce earnings. Borrowers must compare loan terms and eligibility. NASA Federal competes for those decisions with other credit unions, banks and online providers. Member ownership does not settle every comparison in advance.
Geography matters as well. Shared branches, ATMs and digital access support consumers nationally, while business credit products are limited to approved industries operating in Maryland, Virginia and Washington, D.C. Someone who wants a nearby dedicated branch, or a business loan outside that territory, has a different problem to solve.
A different kind of launch money
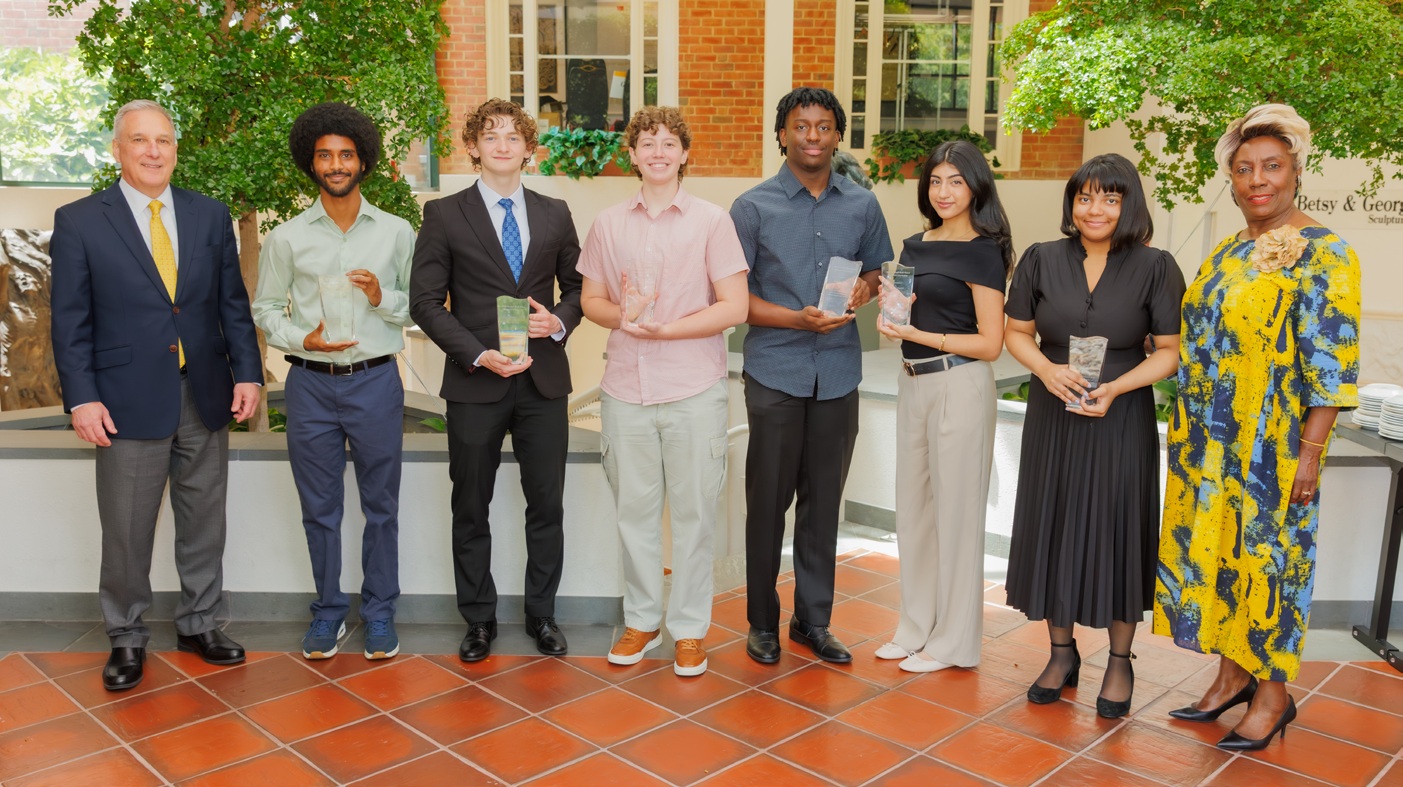
The cooperative idea becomes tangible in its scholarship program. Established in 1983, it asks young members to connect educational ambitions with financial literacy and a plan for paying for college. In June 2026, NASA Federal announced awards for seven high-school seniors, ranging from $2,000 to $12,000.
NASA Federal’s useful trick is making a narrow identity accommodate broad, everyday needs. A customer can arrive for a certificate, stay for a car loan, and manage the relationship through a phone. The decision still comes down to access, terms and cost. The invitation, at least, is easier than the name suggests.
Take a closer look
Explore the accounts, check the terms, or watch the tools in action.