The trouble began with an address. In a case ECS Fin describes at a Malaysian regional bank, corporate payment instructions arrived with beneficiary details written as free text. A person might understand them. The receiving systems wanted structured fields. Validation failed, repair queues grew, and payments slowed. The bank already had a payment hub. The information entering it was still making work for people.
- ECS Fin connects financial messages with the workflows that move money.
- Its customers include banks, investment firms and corporate treasury teams.
- The useful test: can everyone follow a payment when something goes wrong?
ECS Fin’s response combined language models with validation rules to separate addresses into usable components. Uncertain results could go to human review; transformations were logged. The company reports fewer manual repairs and better processing. The revealing detail is the location of the friction: inside the instructions, before the money could move.
01 / A bank is a relay race
That is a useful entrance to this company. Founder and CEO Jacob Aruldhas sells software built around the journey of a transaction. His argument is that institutions organize themselves into departments, then buy applications for those departments. The payment, inconveniently, has to visit several of them.
ECS Fin began as a consulting firm in 1999. Its account of those years describes a recurring problem: multiple vendors, complex integrations, long implementations and unhappy users. Out of those observations came IMS, its integrated platform. The organizing unit became the transaction and everything needed to complete it.
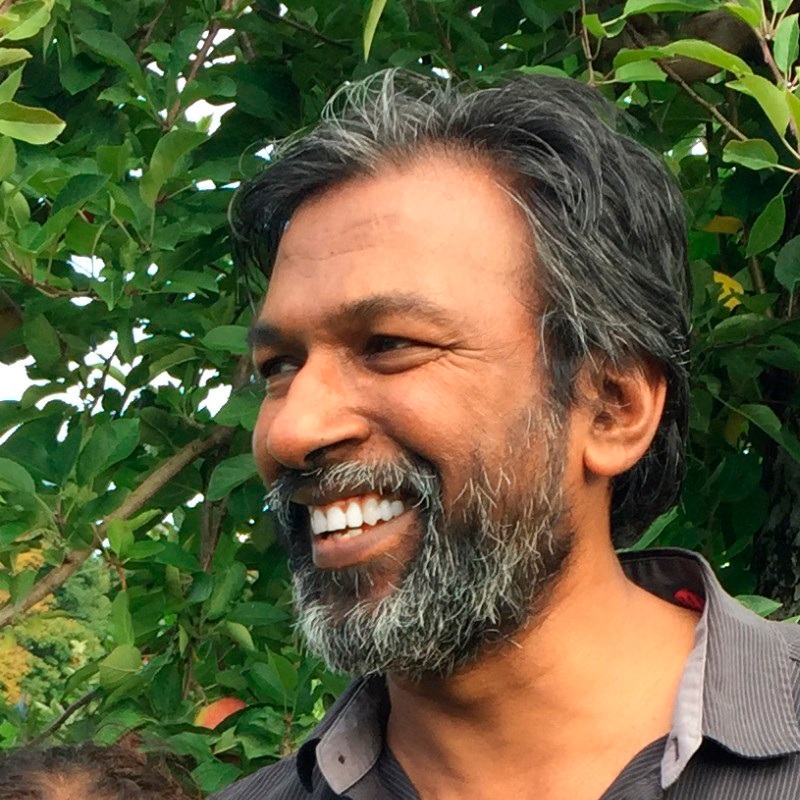
The company’s stated mission connects two ambitions: help large enterprises become leaner and give smaller institutions more independence. Its published philosophy also asks leaders to mentor and treat employees with respect. Both ideas suit a business concerned with how people and systems cooperate.
“Efficiency is a must-have; not a nice-to-have”
ECS Fin’s corporate philosophy
02 / One transaction, three jobs
Consider the product family as a division of labor. IMS Gateway captures, converts, validates and distributes financial messages. IMS Payments manages payment workflows from initiation through settlement and subsequent reporting. IMS Securities handles post-trade processing. IMS Treasury tracks cash positions, balances and related money movements.
ECS Fin describes three processing levels: message, transaction and account. A message has a format and destination. A transaction has a state: accepted, progressing, rejected or settled. An account has balances and positions affected by that activity. Keeping those views connected is the point of the architecture.
Sending is the middle.
Check formats, enrich data and validate network requirements before choosing a route.
For a corporate treasury team, that can mean connecting enterprise applications to several banks while monitoring cash. For an investment manager, it can mean tracking settlement instructions and exceptions. The common requirement is a usable view of work moving between systems and counterparties.
03 / The banks make it concrete
The relationship with Malaysia reaches further back. In December 2012, AmBank Group announced its IMS deployment. Its treasury-operations head described spending more than a year evaluating vendors, then gaining confidence during the first month of the project. That is a helpful distinction: a long buying process can precede an implementation that earns trust quickly. The bank’s executives pointed to operational efficiency, customer service and cost savings as the benefits they were seeing.
At Malaysia’s MBSB Bank, an October 2023 announcement described retail e-payment modules and ISO 20022 readiness for Swift and RENTAS. The bank’s payment-operations head reported shorter processing times and the introduction of QR-code payments. Here, modernization meant adding services while connecting them to existing bank systems.
ECS Fin’s October 2023 report across multiple Malaysian bank deployments. A dated operating snapshot.
Zenus Bank supplies another example. In June 2024, ECS Fin announced that Zenus had integrated Visa B2B Connect through IMS Payments. The integration included pre-initiation checks, country-specific validation, transaction-status updates and handling for rejects and recalls. Access to the network came with workflows for managing what happened on it.
An expanded partnership with INSTANT, also announced that June, applied the same logic to treasury and trade settlement: connect transaction progress with financial information, positions and balances. Knowing that money is moving becomes more useful when the organization can see what that movement means for liquidity.
04 / Permission to trust the plumbing
This is enterprise financial infrastructure, sold with integration, connectivity, hosting and support. IMS has been offered as SaaS, infrastructure services and on-premise software. ECS Fin describes value-based pricing and evaluation before commitment. The commercial proposition includes the work of fitting software into an institution’s operations.
Credentials matter here. In October 2025, ECS Fin announced Swift compatibility validation for IMS Payments in Payments and Swift GPI. Federal Reserve Financial Services also lists ECS Fin among providers supporting FedNow, describing standalone, hub-module and service-based deployment options. Such credentials help establish a vendor’s relevant capabilities; buyers still have to evaluate their own implementation.
ECS Fin also offers a Swift Service Bureau. Its messaging platform prepares and validates outgoing instructions, processes incoming messages, and provides departmental views and repair tools. Hosting and connectivity services let institutions acquire operational capabilities alongside software. For a smaller organization, that combination can matter as much as the feature list: maintaining a specialized messaging operation is itself a job.
The competitive field includes payment-hub vendors such as Finastra and Fiserv, both listed as alternatives considered by ECS Fin reviewers on Gartner Peer Insights. ECS Fin’s pitch emphasizes shared processing and visibility across the lifecycle. A buyer can also assemble separate tools, then take responsibility for their connections.
05 / Make the demo misbehave
The practical lesson is to evaluate a journey. Give a proposed platform an awkward instruction. Have a network reject it. Ask an operator to repair it. Then check who sees the updated status, how duplicate action is prevented and whether the account records reconcile. Those are editorial buying tests suggested by the architecture.
A shared platform still needs dependable inputs and people who agree on ownership. If departments retain separate exception processes, the old coordination problem can survive the installation. If the requirement is simply one isolated connection, a narrower service may be sufficient. Scope should follow the operational problem.
Ask the teams to perform that evaluation together. Operations, treasury, technology and compliance each see a different consequence of the same payment. A demonstration that connects their questions is more informative than four demonstrations that leave the handoffs unexamined. Each team should be able to explain the next step and name the person responsible for it.
Return to that beneficiary address. A successful payment depends on small details remaining understandable across organizational boundaries. ECS Fin has built a business around those boundaries. For a buyer, the decisive question is how much easier the next difficult transaction becomes to finish.