In 1938, William Dillard borrowed $8,000 from his father and opened a store in Nashville, Arkansas. He had studied business at Columbia and completed a management training stint at Sears. Then he returned to a small town to sell things. The interesting part of the story is how often the business that followed would return to that unglamorous task: choosing merchandise, knowing the customer, watching the money.
Today, Dillard’s sells clothing, shoes, cosmetics, accessories and home goods through a mostly mall-based American store network and its website. It occupies the territory between everyday mass retail and designer luxury. The shopper might need a wedding outfit, a work wardrobe, a fragrance or dinnerware. The proposition is several departments, recognizable brands and human help, gathered in one place.
- National brands plus labels exclusive to Dillard’s.
- Inventory control helped reduce markdowns after 2020.
- Flat sales can still produce substantial profit.
The dress has a deadline
Fashion has an awkward property. A dress can remain perfectly wearable while becoming much harder to sell. A season passes. A color falls out of favor. The retailer still owns the dress, but the ticket price starts to look optimistic. Markdowns turn that error in judgment into a smaller margin. Buying well includes deciding how much to buy.
Dillard’s had been working on that problem long before online shopping. Its early use of centralized computers helped track sales and stock. Local knowledge mattered alongside the machinery. A department store in one trade area need not carry precisely the assortment that works in another. The expertise lies in editing a large selection into something the nearby customer actually wants.
That makes its competitive position more specific than simply being another place to buy shoes. Macy’s, Belk and Nordstrom compete for overlapping shopping occasions; Amazon and off-price chains compete for spending too. Dillard’s case rests on its assortment and service. A shopper who wants the cheapest interchangeable item has plenty of alternatives. Exclusive merchandise gives someone a reason to choose this particular door.
A label you cannot comparison-shop everywhere
Antonio Melani and Gianni Bini illustrate the idea. Both started in footwear in 2001 and expanded into apparel. They make Dillard’s a developer of merchandise as well as a reseller of national brands. An exclusive collection reduces the chance that a customer will inspect an item here and buy the identical thing somewhere else.
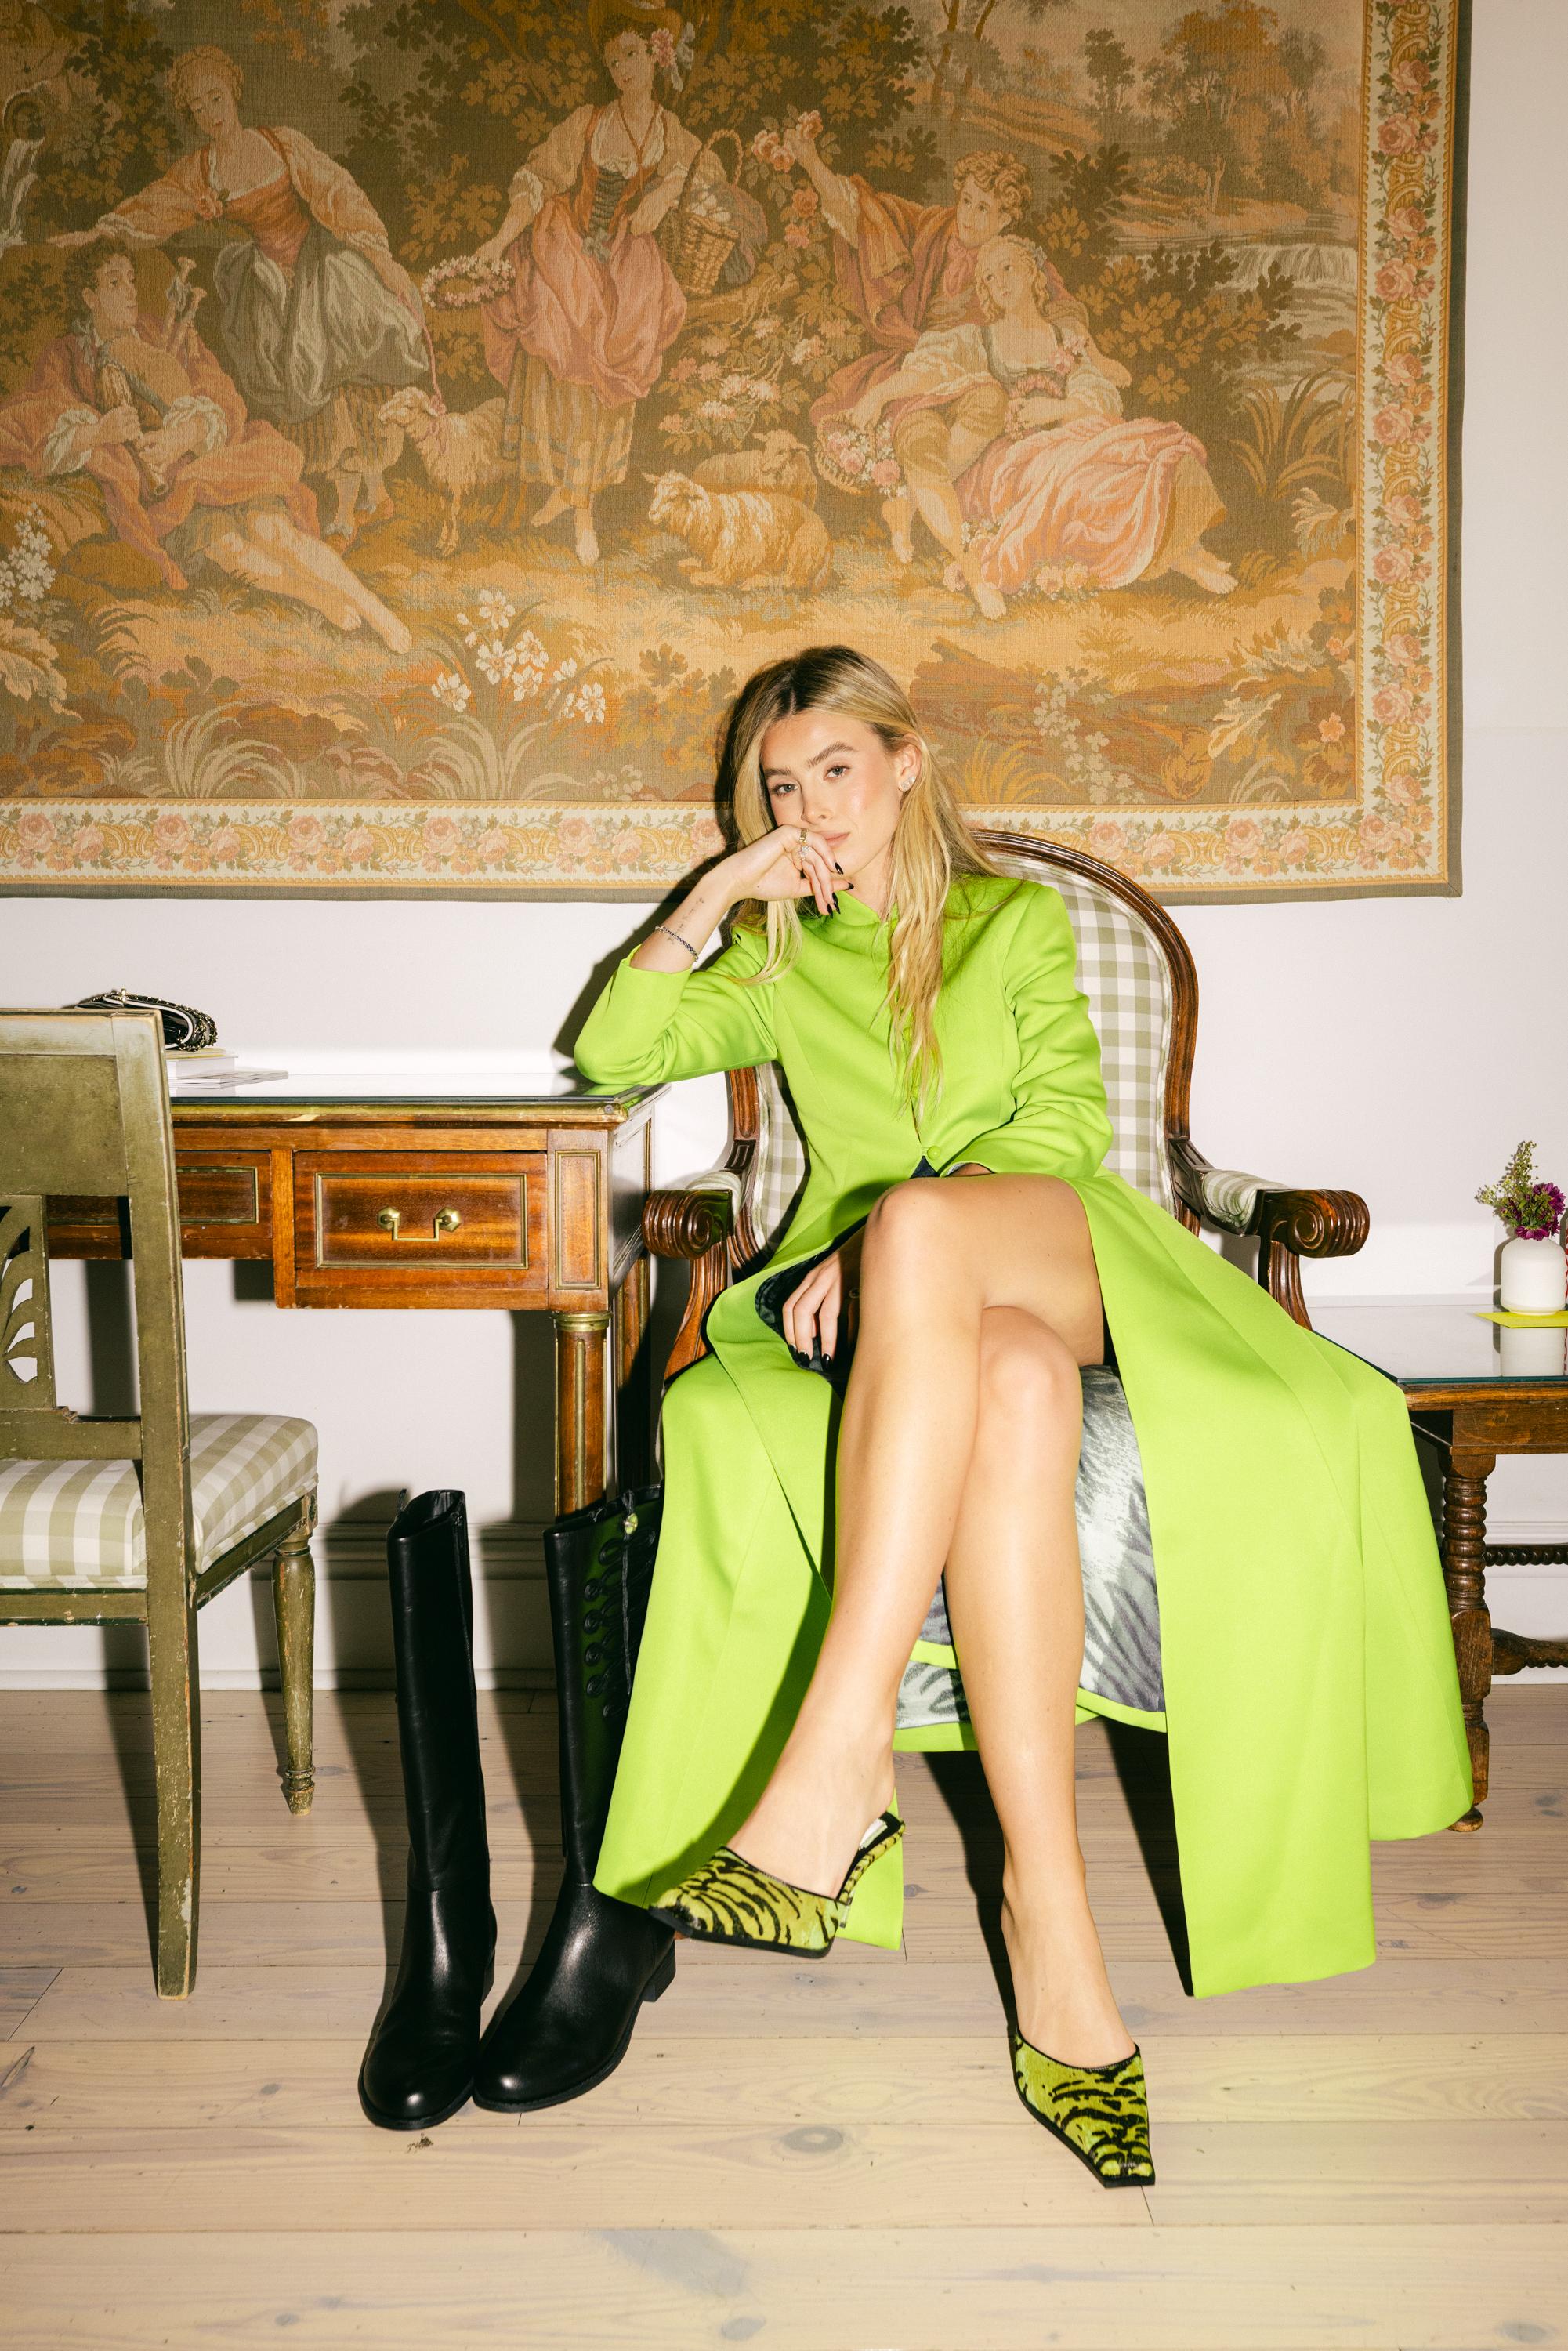
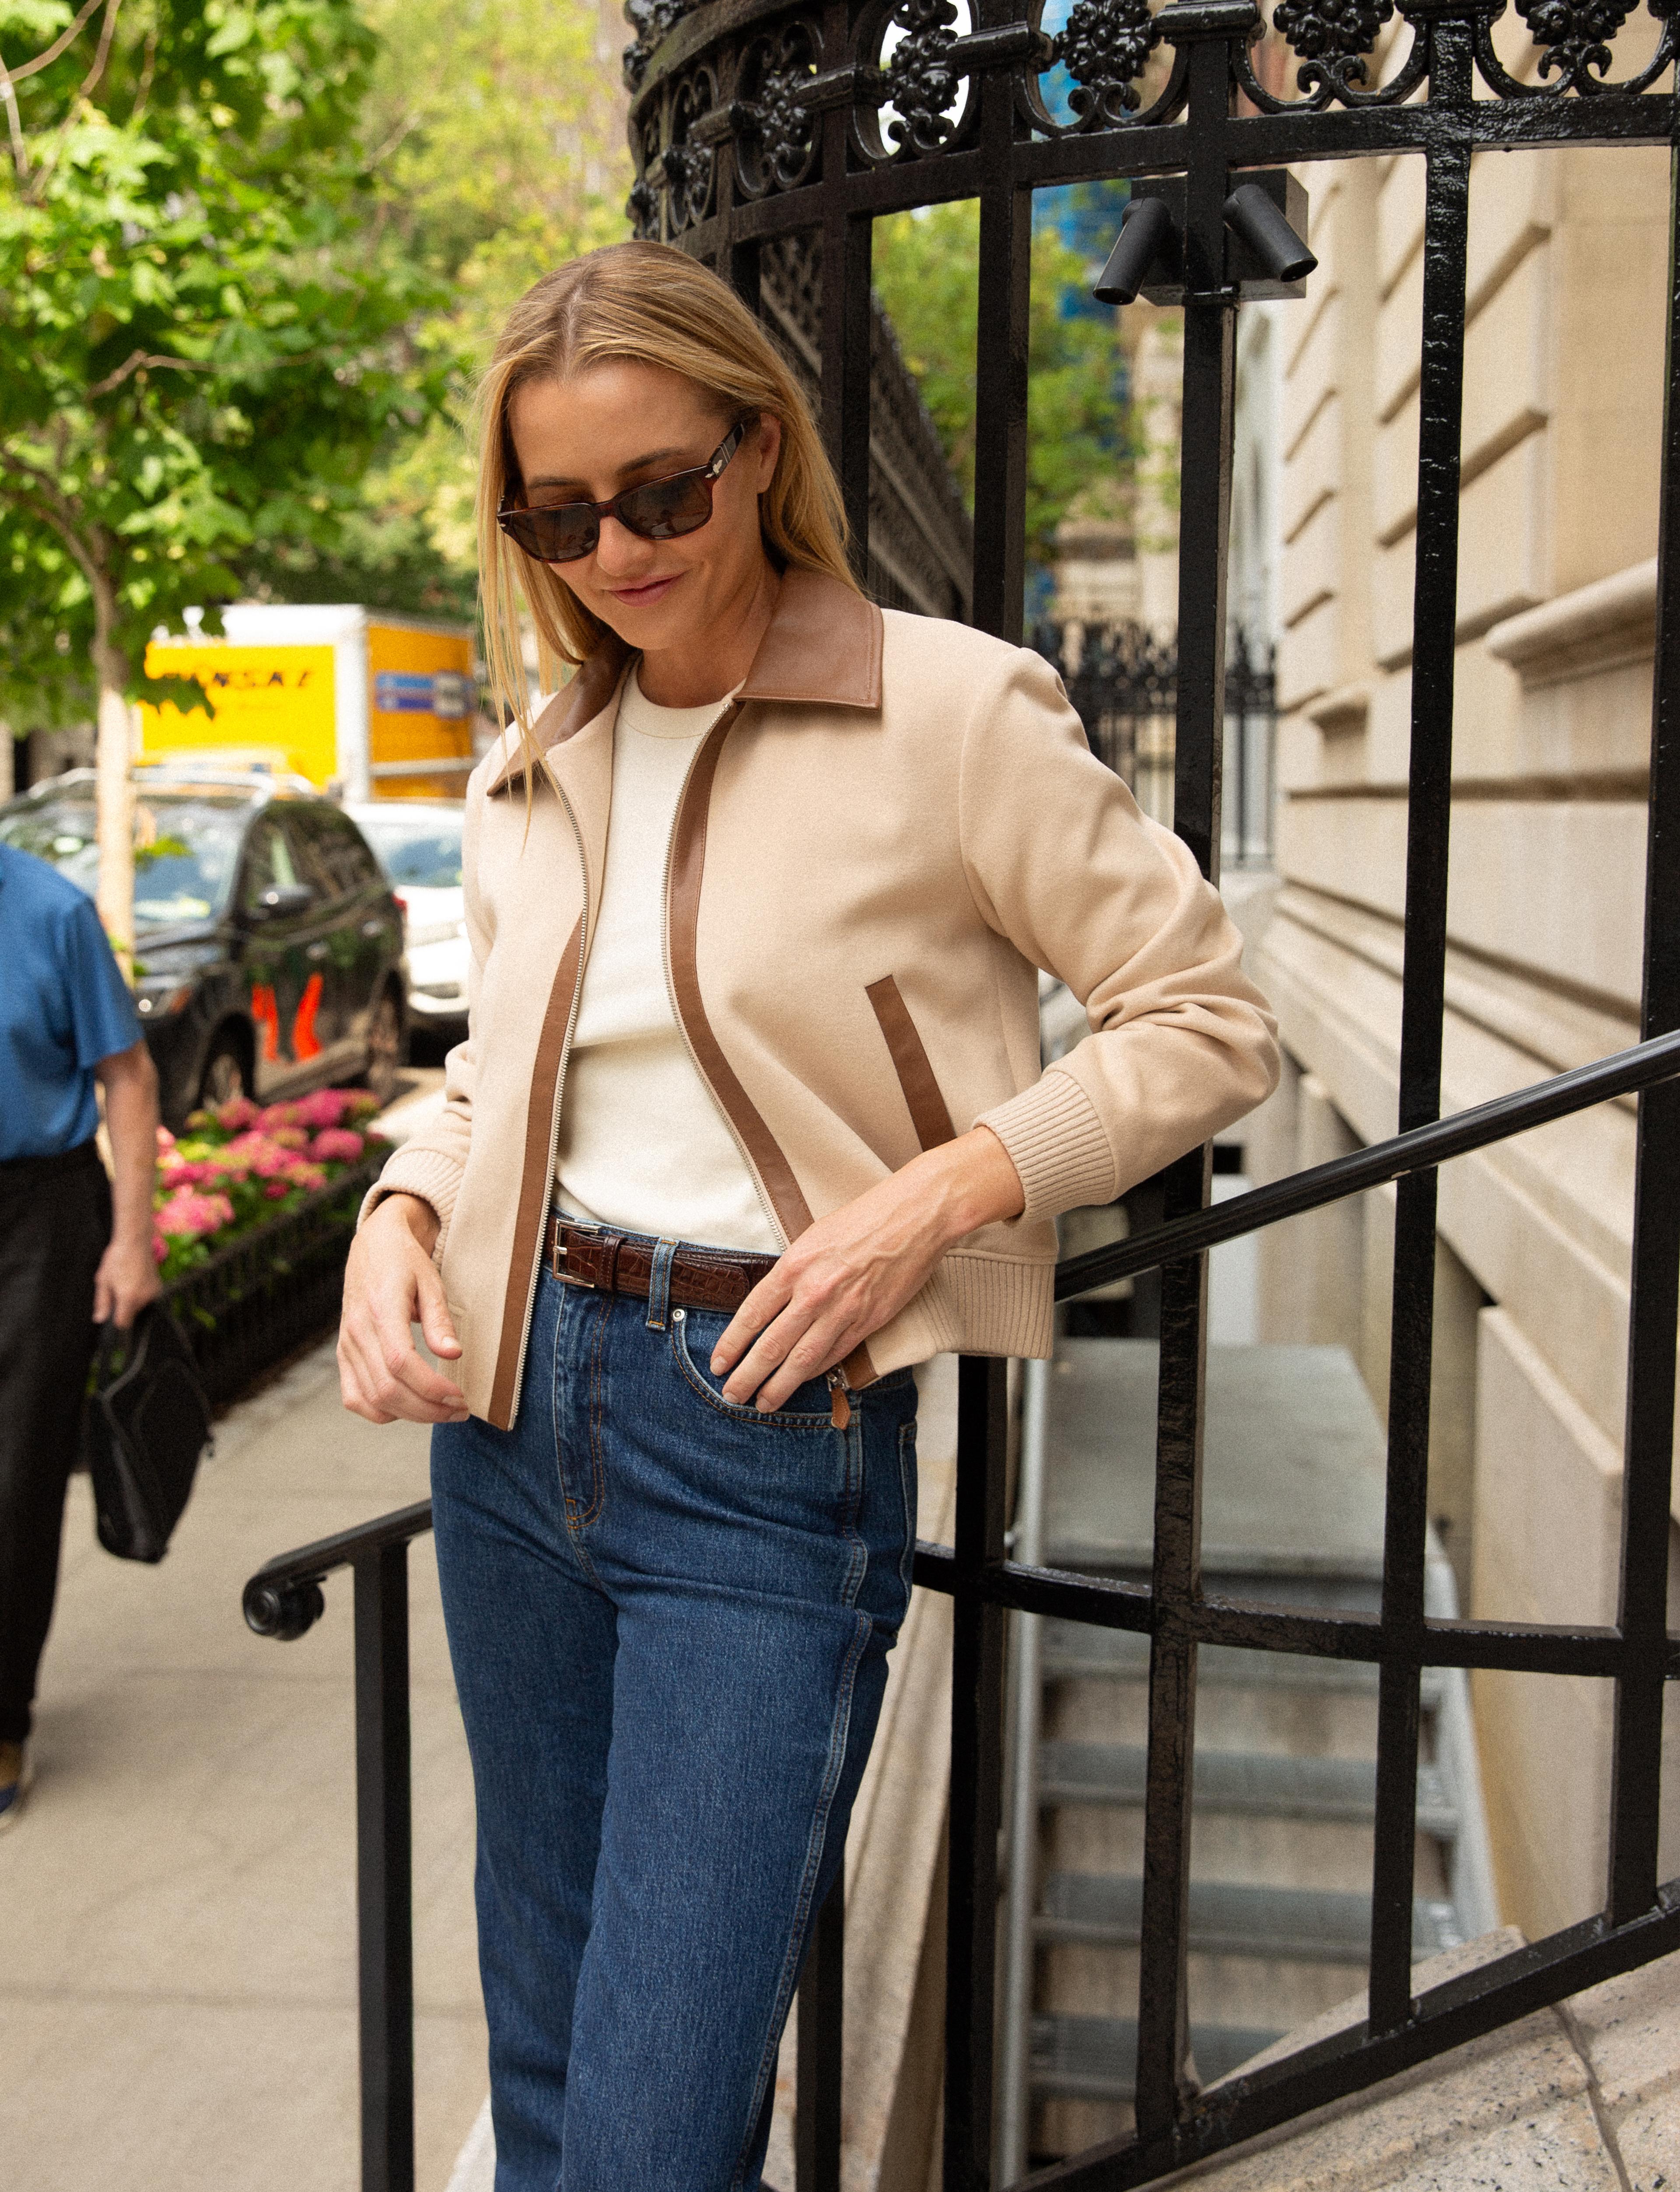
The company refreshes those labels through collaborators with audiences of their own. In August 2026, fashion editor Kristen Nichols introduced an Antonio Melani capsule featuring tailored separates, outerwear and kitten heels. In October, Hadley Greene’s Gianni Bini collection brought statement jackets, dresses and footwear. Familiar retail infrastructure gets a new point of view without needing a new storefront.
There are practical services behind the clothes. Customers can create wedding, baby and gift registries. An in-store wedding registry can be updated online, and the registry remains available for twelve months after the event. Citi issues the store’s credit cards, with Mastercard providing the co-branded network. International online orders run through Zonos, which calculates shipping, duties and taxes. The American mall business has an overseas checkout.
When the customer disappeared
In the first quarter of 2020, the machinery met a problem it could not solve by selecting a better dress. Pandemic closures removed customers from stores. Retail sales fell 47%, and Dillard’s recorded a $162 million net loss. Merchandise was already there. The occasions that made people want it had suddenly vanished.
The following year showed what changed the economics. Demand returned, supported by reopening, vaccines and stimulus. Dillard’s also controlled inventory more tightly. Management attributed improved margins to stronger demand and better inventory management, which reduced promotional activity and markdowns. Fiscal 2021 ended with $862.5 million in net income, against a $71.7 million loss the year before.
The tempting interpretation is that discipline alone produced the rebound. That gives management too much credit. People were shopping again under unusual conditions. But the company could decide how much stock it held when they returned. It also operated with fewer associates and reduced hours. Better profitability carried an operating tradeoff; it did not arrive as a free upgrade.
What survives the sale
The useful test comes after the rebound. In fiscal 2025, which ended January 31, 2026, total retail sales were essentially flat at $6.232 billion. Retail gross margin was 40.8%. Consolidated net income reached $570.2 million, including property-sale gains and a tax benefit. These are different measures: gross margin pays the operating bills before it becomes profit.
There is another wrinkle in the accounts. Dillard’s owns construction business CDI Contractors. Consolidated net sales of $6.474 billion include that operation, so they should not be mistaken for merchandise sales. The company spent $1.759 billion on selling, general and administrative expenses during the year. Running the departments remains expensive even when the buying is careful.
Its physical commitments are substantial, too. At fiscal year-end, 248 of 271 store properties were owned outright. Ownership reduces exposure to a landlord’s rent decisions, while tying capital to buildings and locations. Inside those buildings, experience is part of the service model: roughly three-quarters of salaried store managers had risen from hourly store jobs as of December 2025.
“We reported a respectable year.”
William T. Dillard II
Fiscal 2025 results · February 2026
Copy the buying discipline. Read the fine print.
The lesson another operator can use is concrete: track what sells, adapt the assortment locally, and judge a purchase by the cash left after markdowns. Give customers something they cannot obtain identically everywhere. A smaller retailer can practice that without owning hundreds of buildings. Buying less indiscriminately, however, risks empty shelves and missed sales.
The latest numbers also reward skepticism. Second-quarter 2026 retail sales rose 1%, while reported retail gross margin reached 40.9%. Tariff refunds supplied 2.6 percentage points of that margin; the company said it expected no further significant refunds. Inventory was up 5%. A higher headline margin does not automatically mean the underlying buying operation improved by the same amount.
This approach needs customers willing to pay for the selection, enough demand to move seasonal stock, and enough financial room to absorb mistakes. Weaker mall traffic or rising merchandise and payroll costs can upset it. Dillard’s began with borrowed money and a shopkeeper’s judgment. Its continuing question is wonderfully ordinary: after the customer takes the purchase home, how much does the store get to keep?