The revealing number in Chris Nard's career is not a rate, a reserve or a balance-sheet total. It is forty. In January 2026, the FortiFi chief executive stood before the Alachua County Commission in Florida and described roughly forty property assessments caught in an argument over tax bills. It was a small number by the standards of national finance. It was large enough, however, if your house was one of the forty.
Nard explained that FortiFi had financed projects in the county in 2023 through the Florida PACE Funding Agency. PACE, short for property assessed clean energy, lets qualifying improvements be financed and repaid through an assessment tied to the property. The county and tax collector objected to placing those assessments on the tax roll, litigation followed, and the machinery stopped behaving like machinery. Some property owners paid directly. Others did not. By Nard's account, delay could leave the latter group several payments behind and complicate a future refinance or sale.
His request was plain: with the court fight concluded, the parties should put the assessments where borrowers had expected them to be and do it before the quarter ended. In three minutes of public comment, an abstract financing structure became a calendar, a ledger and a group of homeowners. This is where Nard tends to appear in the public record - after a promise has been made, asking what happens next.
“So now that the court system's run its course we'd like to work with you guys to try to get these assessments on the tax roll.”Chris Nard, Alachua County Commission remarks, January 2026
The photograph before the storm
There is an older scene, preserved in Old Republic International's 2008 annual report. Seven executives from the office of the CEO of Republic Mortgage Insurance Companies pose in a formal room. Nard stands at the center in a pinstripe suit and an orange tie. Everyone looks composed. The mortgage market outside the frame was anything but.
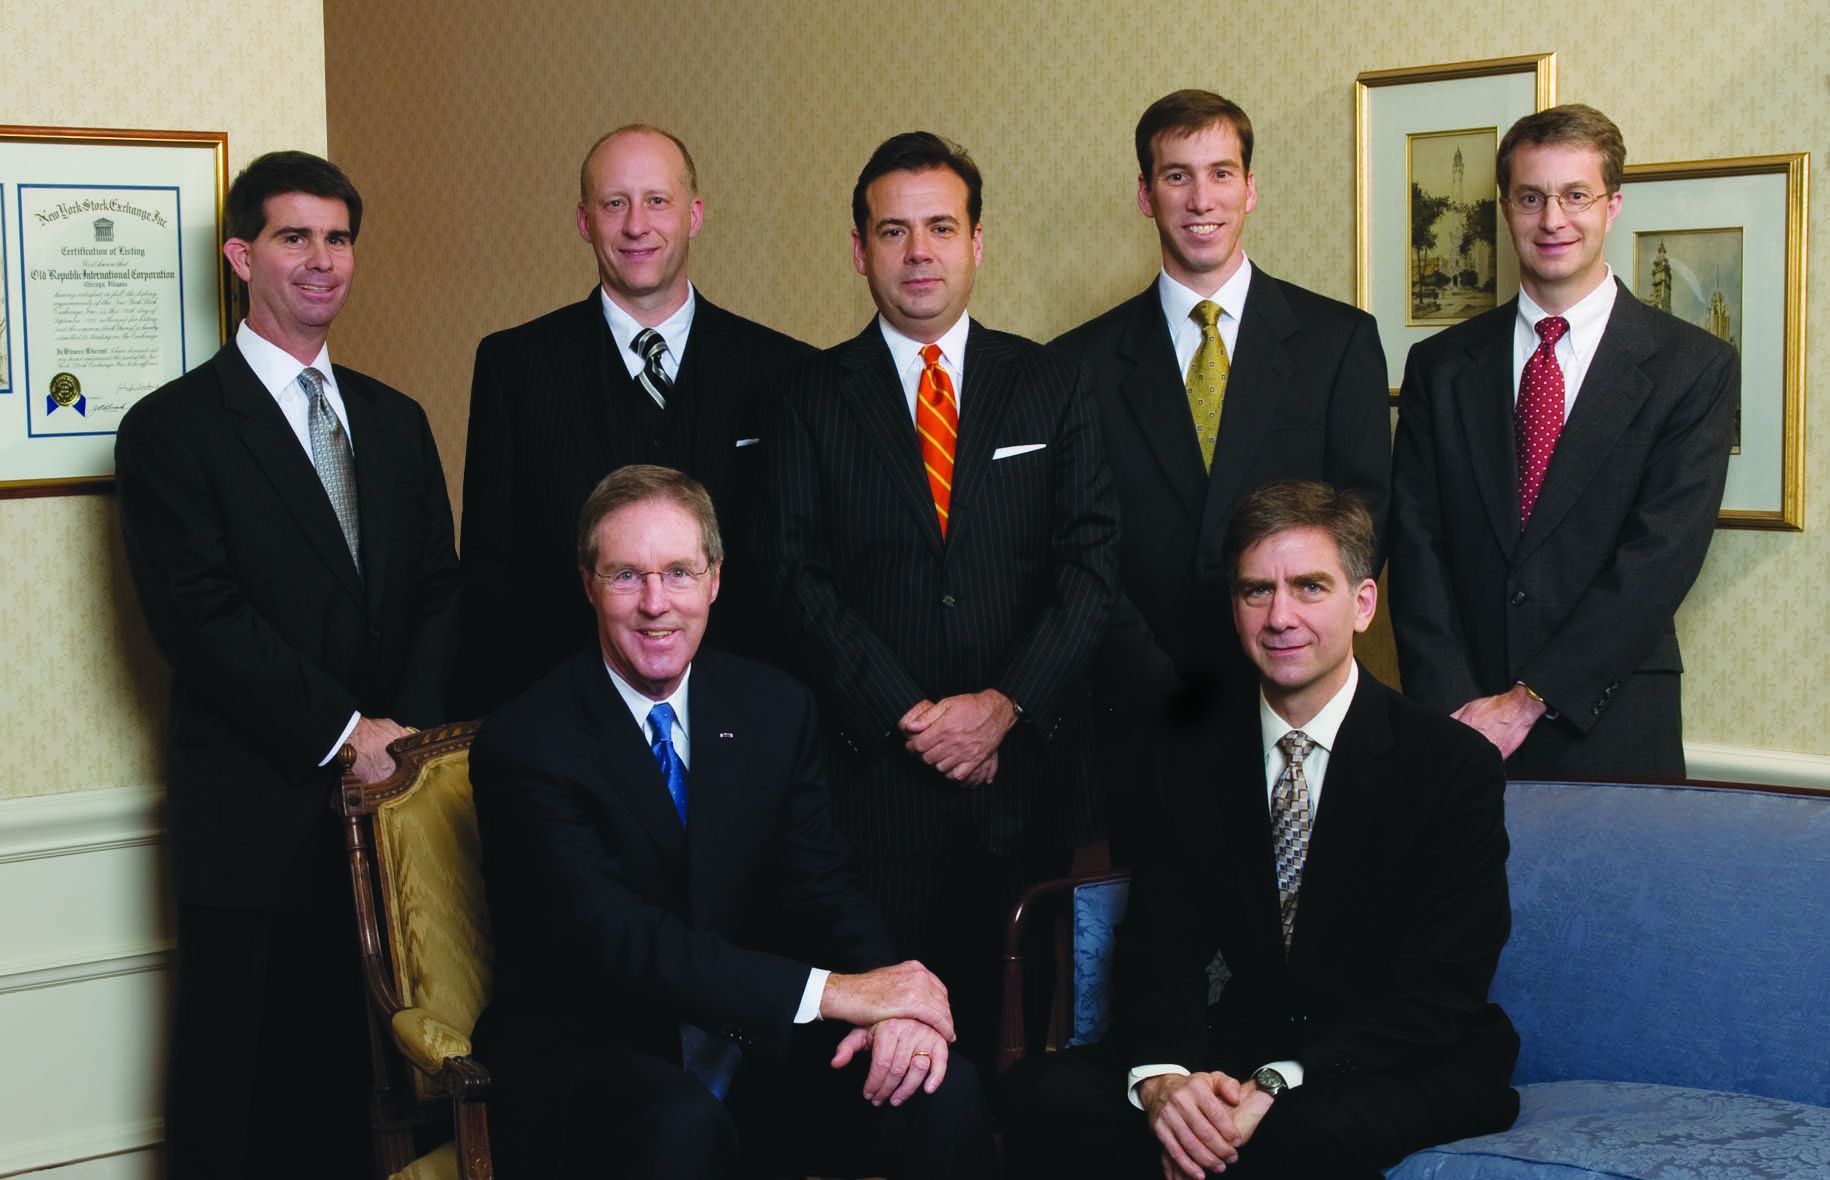
Mortgage insurance protects a lender when a borrower defaults. It is a business built on ordinary months and tested by extraordinary ones. In earnings calls during the financial crisis and its aftermath, Nard spoke in the clipped grammar of the trade: delinquency notices, initial reserves, claim pipelines, loan vintages and modifications. He corrected a questioner who used the word fraud, preferring “misrepresentation.” He distinguished the troubled loans of late 2005 through early 2008 from books written under newer standards. When asked what pricing might do, he offered a phrase admirably resistant to embroidery: “Time will tell.”
The restraint mattered. An insurance executive can make uncertainty sound dramatic or manageable; neither changes the file on the desk. Nard described the procedure. A loan reached a delinquency threshold. The insurer established a reserve. Reviews and discussions followed. His public answers rarely wandered from the mechanics. Even optimism arrived with paperwork attached.
Learning the obligation from both sides
Nard's route into that room began in consumer finance. His public professional history includes a marketing vice presidency at Strategic Mortgage Services in the mid-1990s, followed by more than eighteen years at Old Republic. By 2006, an annual report listed him as a senior vice president of the parent company and president and CEO of its mortgage-insurance companies. A 2009 succession announcement elevated him again: president and chief operating officer of Old Republic International, effective the following July, while he retained senior responsibility for mortgage guaranty.
Those titles placed him close to both the calculation and the consequence of housing risk. An insurer does not choose the kitchen tile or admire the closing-day photograph. It prices the chance that the cheerful beginning may become a claim. During the crisis, that vantage point supplied a severe education in underwriting eras, borrower affordability and the long tail of a loan book.
In October 2015, Nard crossed to a different seat. Citizens Bank hired him as president of mortgage, putting operations, sales and technology under his authority. The bank described him as a thirty-year industry veteran and emphasized his experience leading large organizations. Investor materials later showed the mortgage operation alongside billions in assets under management. Here the obligation was not merely insured. It was produced, processed and serviced.
One obligation, three vantage points
Nard left Citizens in 2018 to pursue other opportunities. By 2020 he was publicly identified as FortiFi's CEO. The product had changed. FortiFi administers financing for eligible property improvements such as energy efficiency, renewable energy, water conservation and storm protection. Instead of a conventional monthly loan payment, PACE financing is repaid through a property-tax assessment. Local authorization, contractor participation, financing capital and tax administration have to meet in the same arrangement. A bright idea for a more efficient house acquires a surprisingly crowded address book.
His formal business education predates every stop on that route. Nard attended the University of Richmond's Robins School of Business from 1981 to 1985. The timing is worth noticing. By the time Citizens introduced him in 2015 as a thirty-year mortgage veteran, his working life had traced much of modern consumer finance: the expansion of mortgage credit, the discipline imposed by a collapse, the rebuilding of bank operations and the arrival of financing products tied to energy and resilience.
Citizens also offers a clue to how he operates. The job combined operations, sales and technology, functions that can quarrel cheerfully in any lending business. Sales wants movement. Operations wants consistency. Technology wants a specification before either side changes its mind. Putting all three under one president makes that friction the president's daily calendar. Nard's next role at FortiFi widened the table again, adding contractors, local governments and tax collectors to the conversation.
The green upgrade meets the tax roll
PACE finance has an appealing premise. A building needs work. The work may lower energy or water use, or make the property more resilient. The cost can be spread over time and attached to the property. Yet every elegant premise eventually meets servicing. Who records the assessment? Who collects it? What does the homeowner understand? What happens during a sale? Which rule governs when agencies disagree?
Nard arrived with an unusual preparation for these questions. Mortgage insurance taught him to look at a pool of obligations after underwriting. Bank leadership put him inside the factory that creates and services them. FortiFi asks him to work where private capital, home improvement and public administration overlap. The career line bends, but it does not break.
His role also moved him into the policy network surrounding PACE. In 2020, PACENation elected Nard to its board as part of a twenty-two-member expansion that included lawyers, bankers, public-policy specialists and executives from other administrators. In 2023, he joined fellow PACE CEOs in asking the Consumer Financial Protection Bureau for more time to answer proposed Regulation Z changes. The request stressed a data-driven response using more recent California and Florida information. Regulation, in this corner of finance, is part of the product design.
“Generally we're notified when the loan has gone 60 days delinquent, and that's when we set up the first reserve.”Chris Nard, explaining mortgage-insurance procedure in 2010
The quote comes from an earlier industry and a different decade, but it captures the habit that follows him. First establish the trigger. Then describe the action. Then watch what the system does. There is little room for the heroic flourish because finance already contains enough fiction in its forecasts.
A career measured after closing day
Executive biographies like ascent: bigger title, larger institution, another polished announcement. Nard's story reads better sideways. At Republic, Citizens and FortiFi, he occupied a different station along the life of a property-related obligation. Each post sharpened a separate question. Can the risk be insured? Can the loan operation run? Can a public-private repayment channel remain intact?
That is why the county-commission appearance belongs at the center rather than the footnote. A chief executive came to discuss forty assessments, including the fraction already being paid directly and the fraction that was not. He spoke about liens, refinancing and selling a home. Grand strategy had narrowed to individual accounts. This was not a demotion of strategy. It was the moment strategy disclosed whether it had done its job.
The portrait from 2008 and the public microphone from 2026 make useful bookends. In the first, Nard stands amid an institution confronting a nationwide mortgage collapse. In the second, he asks local officials to repair one modest section of a repayment system. Between them lie a bank presidency, a clean-finance pivot and decades of consumer-credit experience. The scale changes. The obligation remembers.
For homeowners, that memory is the point. A roof keeps out weather. An efficient air conditioner lowers demand. A storm window faces the wind. Financing lives longer and less visibly, in due dates, assessments and records. Chris Nard has built a career in that invisible afterlife, where the paperwork either keeps its promise or returns to a public meeting asking for help.