The sound came from the alley behind an apartment in Santa Monica. It was 2015, and Caleb Morse and his future wife, Jaime, woke to a cat crying somewhere out of sight. They found her injured in a dumpster. The sensible decisions arrived in the wrong order: first, get the animal to an emergency hospital; later, confront what rescue costs. The number was $4,500. In the antiseptic arithmetic of an exam room, compassion had acquired a price tag.
They paid it. The cat survived and became Hobbes. Yet the bill left behind an unsettling counterfactual. What happens when the person who hears the crying cannot produce the money? A veterinary practice can provide the care. A pet owner can want it desperately. Between them sits a transaction, brisk and impersonal, with the power to veto both.
For Morse, that awkward middle was familiar territory. He had spent years around financial systems, first at Green Dot, the Pasadena company that helped move prepaid cards into the mainstream. He joined after Pomona College and eventually became senior director of banking operations. Finance, at that altitude, is less a matter of elegant equations than a discipline of making many small, regulated pieces behave in the correct order.
Later came an MBA at Stanford, graduate work in environment and resources, and a turn as CFO and head of business development at the home-staging company Meridith Baer Home. His résumé moved freely between scale and purpose. He also founded World Wide Impact, a nonprofit that worked alongside Kenyan agencies and residents of Ngomeni on an ecotourism resort, a vocational school, reforestation and other local projects. It was a varied education in a single question: how do good intentions survive contact with operations?
A reunion with a bill attached
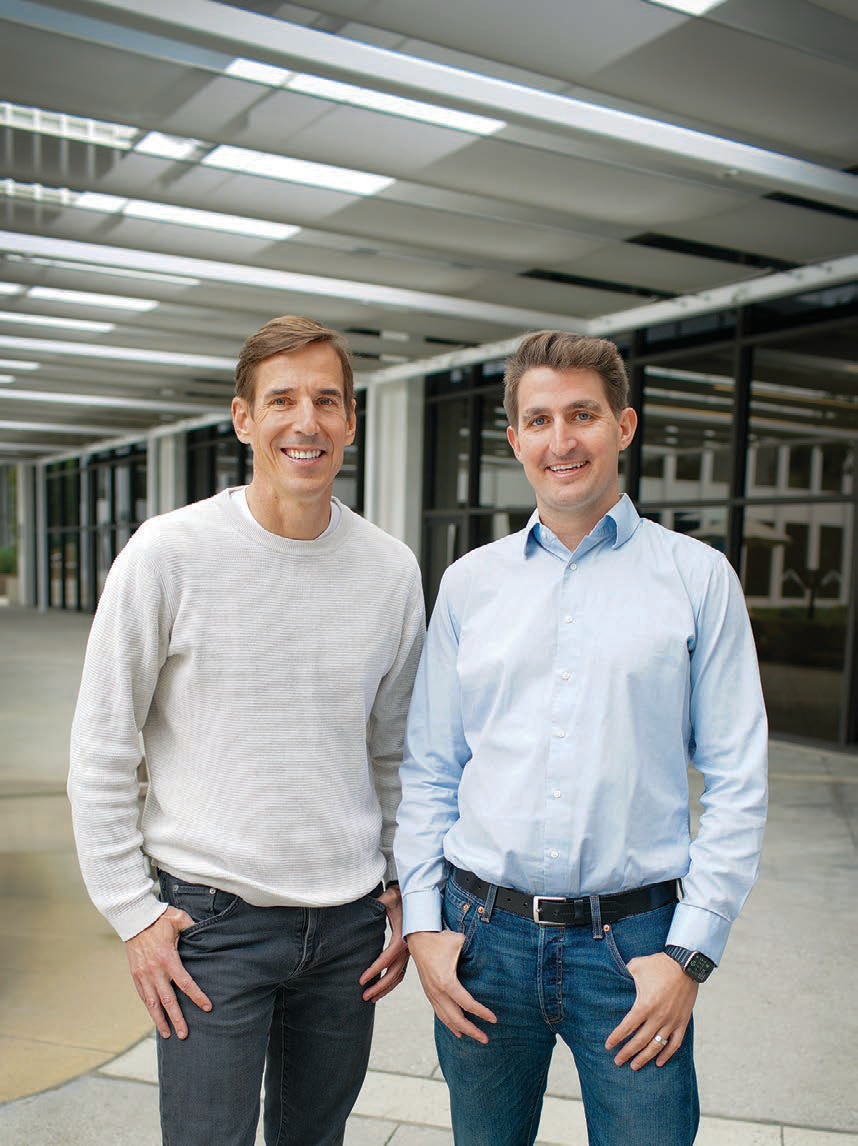
The cat story was still fresh when Morse reconnected with John Keatley later in 2015. They had known each other at Green Dot, though at very different points in their careers. Morse arrived just out of college; Keatley was the chief financial officer. Keatley later went to Sweden as CFO of Klarna, then an early force in what became known as buy now, pay later. Their reunion was not planned as a founding session. The idea arrived, as useful ideas often do, wearing the clothes of a recent annoyance.
Veterinary care had a peculiar payments problem. The need could be urgent, the amount substantial and the customer emotionally exhausted. Traditional revolving credit could be blunt and expensive. Clinic staff had little desire to become part-time loan officers. Morse and Keatley imagined financing tied to a particular treatment and a particular amount, delivered quickly enough to be useful while the owner was still in the clinic.
“When we first launched Scratchpay, our goal was to get more pet parents the care they needed using fair, affordable, and transparent payment plans.”
The phrase “quick decision” conceals an enormous amount of slow work. Consumer lending is regulated. Licenses must be obtained, underwriting must be designed and money must arrive where it is promised. Morse became a regular at California’s financial regulator while securing the necessary approval. The founders went without salaries for more than a year. Their savings paid for the product, the marketing and even the first loans.
There is a pleasing inversion here. Scratch was built to remove friction from a few minutes in a clinic, but its founders accepted friction in nearly every other part of their lives. They absorbed the complexity so the customer would not have to. A well-made financial interface is like a good waiter: present at exactly the necessary moment, then discreet enough to vanish.
The elegance of less
Within twelve months of launch, 500 practices were offering Scratch Pay. That speed makes more sense when viewed from the front desk. A practice needed no extra hardware. Staff did not have to mediate the application. Pet owners applied on their own phones and received a decision. Scratch paid the clinic, while the payment schedule remained between Scratch and the borrower.
In 2017, Morse carried the pitch directly to veterinary professionals at an industry conference. He told the story plainly: he and Jaime had found a cat in a dumpster, then spent thousands of dollars at emergency visits. Scratch offered plans of up to $10,000 at the time, with a short application and no penalty for paying early. The practice was paid the next business day. Each detail answered a different objection, and none asked the clinic to become a bank.
This was not technology performing a circus trick. It was technology declining to add another chore. At a veterinary practice, administrative time competes with every other task in the building. A product that required training, explanation and reconciliation would merely move the burden from one anxious person to another.
The customer experience also carried a deliberate boundary. Unlike a revolving line of credit, an early Scratch plan was approved for a specific amount and purpose. The distinction is not glamorous, which may be why it matters. A worried owner did not need another open-ended financial relationship. The immediate question was smaller: can this particular bill be divided into terms I understand? Good product design often begins by refusing to solve more than the customer has asked.
Morse’s particular contribution has been described as an obsessive attention to products that meet customer needs. Keatley supplied a steadier, opportunistic approach to financing innovation. The pairing sounds less like startup mythology than a sensible division of anxieties: one founder worries about what the customer touches, the other about what keeps the machinery funded.
From clinic counter to network
Publicly reported practice counts at key moments. Bars show relative scale, not annual continuity.
By 2019, Scratch had financed transactions for owners of more than 70,000 pets across over 5,000 hospitals. In 2020, it reported roughly 100,000 loans. By the time a $35 million Series C arrived in 2022, more than 10,000 veterinary and medical practices were using its tools, and the company expected to process nearly $1 billion in patient payments by year’s end.
The money changed the scale, but the product also changed shape. Scratch Checkout added cloud-based payment processing, including remote payments, digital invoicing and reconciliation. The company moved from helping with the exceptional bill to handling the ordinary stream of transactions around it. Scratch now says its products facilitate 20 percent of U.S. veterinary transactions and can be used at most veterinary offices in the United States and Canada.
A decade measured in decisions
Company origin stories are usually polished until the founders appear to have been walking toward destiny all along. Morse’s path is more interesting because it retains its contingencies. He studied economics, mathematics and politics. He worked in banking operations. He spent years on nonprofit projects in Kenya. He pursued environmental study, interned at a company developing nanotechnology-enabled supercapacitors and ran finance for a home-staging business. None is the obvious apprenticeship for veterinary payments. Together, they look like training in how systems meet ordinary lives.
Joins Green Dot and founds World Wide Impact.
Completes his Stanford MBA and becomes a finance chief in Los Angeles.
Rescues Hobbes, reconnects with Keatley and begins shaping Scratch.
Becomes president as Scratch closes a $35 million Series C.
Scratch adds a purchase facility to support further lending demand.
The company’s later years have brought the familiar honors of a business that endured its first awkward phase. Morse and Keatley were named Greater Los Angeles finalists in the Entrepreneur Of The Year program in 2024 and again in 2026. Scratch ranked No. 430 on the 2025 Inc. 5000. Partnerships extended its payment processing into larger veterinary networks and online pharmacy workflows.
In May 2026, Scratch announced a purchase facility with Victory Park Capital. Morse described the cost of care as a primary barrier keeping pet owners from approving treatment and said the facility gave the company more room to support clinics and families. It was finance speaking in finance’s native dialect, but the purpose remained legible: more capacity for the moment at the counter.
There is no perfect financial product for an imperfect day. A loan does not make a bill disappear, and speed does not make a difficult choice trivial. The honest ambition is narrower and more useful: clarity instead of bewilderment, options instead of a dead end, and a process that respects the customer’s urgency without exploiting it.
Hobbes supplied the founding anecdote, but also the standard. The transaction mattered because something alive waited on the other side of it. Morse has spent the decade since trying to make that transaction less forbidding. For all the licenses, funding rounds, payment terminals and underwriting models, Scratch’s story still returns to an alley in Santa Monica. Someone heard a cry. Then came the difficult arithmetic of answering it.